testata inforMARE página de inicio
Cerca
16 de noviembre de 2026 - Año XXX
Periódico independiente sobre economía y política de transporte
11:04 GMT+1
LinkedInXFacebook
FORUM de lo shipping y
de la logística


Shipping and Shipbuilding Markets in 2002

I N D E X


The dry bulk market in 2002


The freight market:
     Capesize - Panamax - Handymax & Handysize
The second-hand market:
     Capesize - Panamax - Handymax & Handysize
 

The dry bulk shipping market finished the year 2002 taking all sizes into account at levels that had not been seen since the end of 2000, at a time when the overall economic conditions were far more favourable. At the beginning of the year nothing indicated such a sprightly resurgence, and few analysts would have stuck their necks out to predict freight rates around $25,000 per day for modern Capesizes. As in other sectors of the shipping market, everyone was betting on a recovery of the American economy, and in its wake that of countries in the European Union, occurring during the course of the second half of 2002. This was by no means the case, and the uncertainties linked to the American intervention and their allies in Iraq, more than ever casts a pall over the world economy and the confidence necessary for a rebound. Japan is for its part still stuck in its quagmire which has been going on for several years.

The factors that have contributed to the rise in freight rates during the year, mainly with effect from September, are essentially:

  • a significant increase in raw materials into China, Japan and other South East Asian countries ; whilst total world growth has been flat the exception is China which registers annual increases in GNP of the order of 7,5 %.

  • a decrease in the number of newbuildings coming onto the market compared to previous years, at least as concerns the Capesizes and Panamaxes.

  • a steady increase in the cost of bunkers, which was caused initially by the policy of reducing OPEC production, and secondly by the fear of conflict in the Gulf.

  • at the end of the year, shutdown for maintenance of some Japanese nuclear power stations, resulting in a sizeable increase of steam coal imports.

We will attempt a rapid tour of the main events in the dry bulk market over the course of the past 12 months. For reference, the Baltic Dry index which began the year at 876 points ended at 1739, the highest level since November 2000.

Based on the statistics published by IISI at the end of January 2003, world crude steel production has totalled slightly over 900 million tons in 2002, an increase of 6,4 % over 2001. The lion's share of this rise is due to China producing 181 million tons, compared to 150 million in 2001, or an increase of 20,3 %. For comparison, in 1995 Chinese steel production was 95 million tons and was below that of Japan's 101 million tons. In 2002, Japanese production reached 107 million, an increase of 4,7 % compared to 2001, an impressive achievement if we consider the lethargy of the Japanese economy. Production in the E.U. only increased by 0,1 %, and to illustrate the contrasting situations, French production increased by 5,6 %, whereas Germany was only able to come up with a modest rise of 0,4 %. The restrictive measures taken by the U.S. seem to be taking effect since after months of declining production, American steel figures for 2002 finished with an increase of 2,5 % over 2001 with 92 million tons. Japanese and Korean steel producers who fed the Chinese market throughout the year, helped alleviate the American and European markets, thus allowing steel prices to find their levels of the first quarter 2000 after two years of decline. With steel production being the driving force of the Capesize market, the higher production levels were bound to have an influence on freight rates.

The healthy standing of the Capesize market was partly due to the growth in Chinese imports of iron ore. Based on provisional figures these should exceed 110 million tons in 2002, 20 million more than in 2001. In addition, the share of Chinese imports coming from Brazil should represent 27,1 % of the 2002 total, compared to 17,3 % in 1998, thereby stretching the ton/miles. If this trend continues, in a short time Chinese imports of iron ore will surpass that of the E.U. and of Japan. Still in the realm of raw materials, Japan was obliged to import nearly 6 million tons of additional steam coal over the period September 2002 to April 2003, following the shutdown of 9 nuclear power stations out of a total of 18, run by Tokyo Electric Co. which helped to sustain the Panamax market in the Pacific during the fourth quarter. In the case of cereals, Australia suffered one of its worst droughts in history and its crop was halved, thus redirecting imports from the South East Asian countries. Grain trade according to the International Grain Council should remain stable for the 2002-2003 season around 207 million tons.

In the industrial sector new mergers were formed in 2002. In Japan, NKK and Kawasaki Steel united forces in a new entity, JFE Steel, which initiates the first merger in the steel industry in the country and follows the example within the European scene which underwent a profound restructuring two years earlier. The combined production of the two companies totals some 28 million tons. At the same time, NSC, Sumitomo Metals and Kobe Steel have entered negotiations in view of getting together. And still within the steel sector, US Steel made a proposal to take over National Steel for $750 million but as yet unconfirmed. Also to be noted is the intended acquisition of the aluminium division of Corus by Pechiney.

Finally, at the end of the year, the IMO against the better judgement of certain countries, decided to impose double-hulls on vessels over 150 meters for all newbuildings. This ruling still has to be ratified within the context of the SOLAS convention by January 2004 at the latest. Certain owners having anticipated this decision, placed orders for double-hulled ships already during the course of the 2002.


Parallel to the increase in freight rates over the year, one should not forget the rise in bunker prices. The price of IFO 380 cst went from $100 per ton in January, basis delivery Rotterdam, to over $150 per ton in December, which corresponds for a Capesize to an increase of 50 cents on an average freight rate of $ 8,15 on a voyage Brasil ' Rotterdam.
 

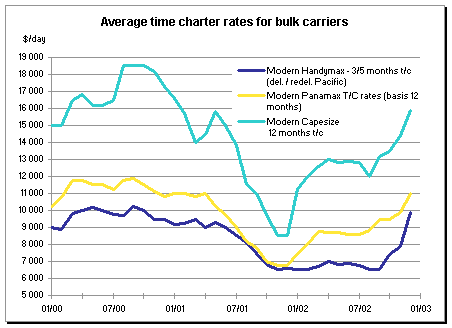
To appreciate the movement of freight increases in the Atlantic we can cite a few examples. On the iron ore route from Brazil to China, rates went from $ 6/ton in January to $ 7,50 on average from March to August, to finish the year at $ 13,50. Transatlantic cargoes took off from $ 4 at the beginning of the year to fix at over $8 twelve months later. This hike was also repeated within the coal market out of South Africa. At the start of 2002, cargoes were fixed to North Europe at under $ 5 per ton, to achieve $ 8 at the end of September, and finish the year at above $10. In the Pacific, there was a similar phenomenon despite the fact that the Atlantic market benefited with a premium over the Pacific basin. Freights on the iron ore route from Australia to China doubled between January and December. Backhaul routes however suffered from the drop in liftings of minerals from Australia to Europe. This strong rise in rates was even more pronounced on the time-charter market. Modern large ships, fixed for fronthaul trips with delivery Rotterdam to the Far East via Brazil were achieving $ 8,000 in January and ended the year above $ 26,000. Modern ships of 170,000 dwt chartered for 12 months witnessed their rates reach over $ 18,000 at the end of the year, some $ 7,000 more than they could expect in January 2002.
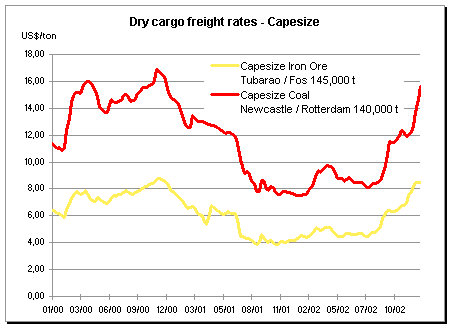

 
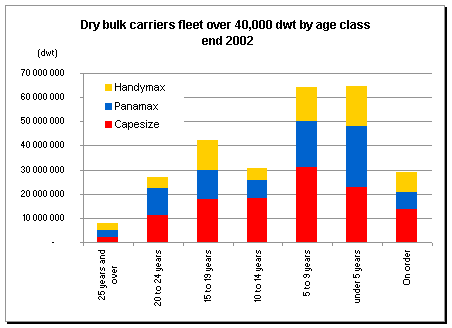
The Capesize fleet has remained relatively stable and delivery of new tonnage was limited in 2002. Twenty-five ships for 4 million dwt were delivered, against 34 in 2001, whereas 17 ships were scrapped (of which 8 were combined carriers). In 2003 additions to the fleet will stay limited, despite a small growth, due to the fact that there were very few major orders during the period 2000-2001. Thirty-two additional ships, for 5 million dwt, should come into service in the course of this year. However the sudden upsurge in freight rates during the second half of last year, linked to low construction costs, and the availability of early slots in certain Japanese shipyards, plus the creation of new building docks in China has contributed to a flood of orders to be delivered as from 2004. No less than 50 ships have been ordered in 2002, including several big carriers of 200,000 dwt for Japanese account.

In 2001 in line with large tanker owners, some of the principal players in the Capesize market have created the pool Cape International which combined some 80 ships. This unit had its difficulties in getting formed, since in October 2002 Zodiac who had the biggest contribution to the pool decided to withdraw. Elsewhere, the Capesize and Panamax fleet of two other major players in the dry bulk scene Coeclerici and Ceres Hellenic joined forces. At the end of the year the Belgian Cobelfret strengthened its position within the Capesize market by acquiring the 50 % held by BHP-Billiton in its affiliate Cobam.

The Panamax market began the year 2002 at depressed levels. Inter-zone rates for modern ships did not surpass $5,500-6,000 per day. The spread between the two basins, Atlantic and Pacific, have progressively widened. All newbuildings were delivered into the Pacific area, and the reduction of voyage times (ton/miles), quickly repositioning these ships into their original area of operation, weighed heavily on freight levels. As with the Capesizes, levels from the Atlantic to the Pacific rose during the first three quarters, with modern vessels obtaining daily returns rising from about $ 7,500 in January to nearly $13,000 end December. This situation lasted until the beginning of the fourth quarter when volumes of coal coming out of China primarily for Japanese destination helped push rates even higher. At the end of the year however the Pacific market went along with its alter ego in the Atlantic. Backhaul rates stayed low throughout the year, with owners having tonnage in the zone being prepared to make sacrifices in order to return to the more advantageous Atlantic.
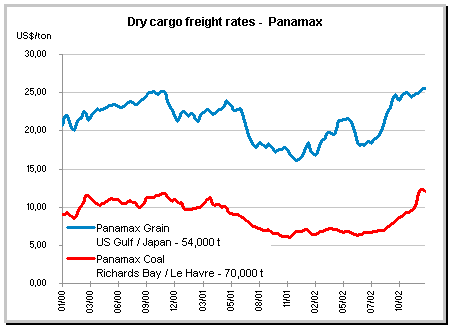
 

As with the Capesize fleet, the number of Panamaxes delivered in 2002 was down compared to the previous year. Fifty-five ships for 4,1 million dwt entered service, as against 116 in 2001. This drop in deliveries will be even more marked in 2003, as only 26 new ships for less than 2 million dwt, will come out of the Asian shipyards. For the same reasons as with the Capes, orders burgeoned during the second half, mainly with the Japanese yards and to a lesser extent with the Chinese. As a result, 76 orders were placed in 2002, with deliveries being spread out over 2004 and 2005. Scrappings remained modest, with only 29 units of which 4 combined ships removed from the fleet. Finally a new type of Panamax should be noted, the Kamsarmax, its name being derived from a port in Guinea and developed by the Japanese shipyard Tsuneishi, with a deadweight of 82,000 (length of 229 meters, width of 32,26 meters, draught of 14,35 meters) and capacity of 97,000 cbm and of which seven units have been ordered.

The bulk carrier market of Handymax and Handysize offers a more contrasted picture. On the one hand, the Pacific market has suffered for a long time from the high level of newbuildings being delivered, since on average nearly 3 ships per week have been coming onto the market in 2002. Conversely the Atlantic market has been well supported mainly with traffic to the Far East. Important volumes of steel, fertilisers, and cereals leaving the Black Sea, the Mediterranean and North Europe helped sustain freight rates for a good part of the year. Consequently large, modern Handymaxes have been able to obtain rates reaching up to $14,000 per day for voyages to the Far East. Satisfactory levels were seen throughout the year, with levels never falling below $10,000 per day after April. As with the Panamax, Handymax owners not wishing to go off into the Pacific zone at any price, were able to get premiums on these destinations. At the start of the year the Atlantic market was hesitant, with the grain trade out of South America being slow to get off the mark. For ships between 43,000 ' 45,000 dwt, daily returns for inter-Atlantic business averaged at $8,500 per day, the lowest being in January at below $7,000 per day, and the highest in December at around $10,000 per day. The Indian Ocean and the Middle East Gulf zones also benefited from a generally favourable market due to traffic into India or China. The Pacific market remained depressed for the first three quarters of 2002, with levels for inter-zone voyages rarely going over $ 6,000 per day. During the last quarter freight rates firmed up steadily to the point of reaching Atlantic levels right at the end of the year.

Handysize ships traditionally enjoy a less volatile market and started the year below $6,000 per day for short periods reached levels near $7,000 during the last quarter. The Handysize fleet is old and should therefore diminish progressively over the coming years, and with no new units coming in to replace those leaving the fleet bringing about changes mainly in the sugar and fertiliser trade.

The decrease in deliveries of Handymax and Handysizes in 2002 compared to 2001 had less of an affect on the large size of dry bulk carriers, but the persistent flow of nearly 3 ships per week coming out of the Asian yards put continuous pressure on the Pacific market. 148 ships for 6,2 million dwt came into service compared to 155 the previous year. With the same causes producing the same effects, orders were extremely high in 2002.

About 160 new contracts were signed with confirmation this year of the attraction for Super Handymaxes, ships over 50,000 dwt, for which an increasing number was ordered with Japanese and Chinese shipyards. Against these deliveries, there was an offset of 123 old units which went to scrap. But contrary to the Capesize and Panamax, the volume of deliveries will continue to be felt in 2003 since nearly 130 ships should be delivered.

The new year's prospects are similar to those at the end of 2002. Iron ore and coal volumes are on an upward trend. Moreover, concerning the Capesize and above all Panamaxes, new deliveries will be very restricted in 2003, giving a welcomed respite for owners. Two uncertainties remain however : during the course of the year will the hopes of a world economic revival, repeatedly delayed, give an additional stimulus to the dry bulk movements? Will China, the driving force in the dry bulk market, continue to charge ahead at full speed and for how long? The American military intervention in Iraq, even of short duration, will put back this recovery and would bring about repercussions which nobody can precisely foresee.

* * *

The future is always right!


The second-hand market
 
The Capesize second-hand market (80,000 dwt and over)

Following as always the freight market with a certain variation both in time as well as intensity, the second-hand Capesize market globally tracked the drop in the last months of 2001 before picking up at the beginning of 2002.

This increase continued until March / April. Prices then remained stable before firming up significantly again as from September. The year finished on a very strong upbeat.
We have noted some 36 sales for further trading (17 comprising ships delivered between 1990 and 2002, and 19 Capesize built between 1981 and 1989). Nine ships built between 1971 and 1982 were scrapped this year, roughly 1.14 million dwt, whereas 26 ships were delivered amounting to 4.25 million dwt.

Owners lured by a modest orderbook (about 9.3% of the existing fleet at the end of 2001), reasonable prices for construction and historically low dollar interest rates, were unable to resist the temptation to order on a massive scale.

There have been about fifty firm orders placed in the course of the year 2002, for a total capacity of 8.5 million dwt, figures which are worth comparing with the 20 orders of 2001 representing a total tonnage of 3.37 million dwt.

The strong rise in freight rates during the last quarter has however benefited primarily to second-hand ships available on a prompt basis.

Based on construction in a good shipyard, fully classed and in good condition, the following prices apply:


January 2002


December 2002

150 000 dwt

built in 1990

about $14 / 14.25 m

about $ 17.25 / 17.5 m

150 000 dwt

built in 1995

about $18.5 / 19 m

about $ 24.5 m

There are some encouraging signs at the end of 2002 and optimism is in the air, even if some of uncertainties cloud the market, such as the collateral effects of the war in Iraq, new regulations being studied for the introduction of double-hulls for bulk carriers, etc.

One should also not forget that the tonnage on order has to be absorbed by the market. In 2003, there will be some 5.0 million dwt added, followed by a further 6.4 million dwt in 2004 and with the firm orders recorded so far, over 2.0 million for 2005.
  

The Panamax, Handymax & Handysize bulk carriers second-hand market

Predicting what the future may bring can be dangerous, whereas if a prediction proves to be correct then whoever was bold enough to make it, can but refer to it.

In our last year's annual review covering these sizes we were of the opinion that 'values had bottomed out' and that anyone interested in investing in these sizes should be inspecting and offering as soon as possible as we felt that in the near future prices would increase. In the case of Panamax and Handymax size we were in fact cautioning prospective buyers of a possible 'stampede', which would in turn cause prices to climb faster and without any real logic.

It seems that this is what more or less happened.

Freight rates were rather stable for the first part of the year but the feeling that prices had reached the bottom fuelled competition amongst prospective buyers resulting in higher prices than the last comparable sales. Then as soon as buyers started to cool down the freight markets started to firm-up resulting in very good chartering returns for dry bulk owners, which was the perfect reason for any potential buyer to go out hunting again.

Prices across the board increased about 10 / 15 % within a few months, whereas the overall price increase at the end of 2002 reached a very healthy 25 % and in some cases has exceeded 30 % when compared to the beginning of 2002 / end of 2001. Once this trend was firmly established in buyer's minds, it caused a flurry of activity in the sale & purchase market.

A total of about 330 ships reportedly changed hands during 2002, this is about double the number of ships when compared to 2001. A 100 % increase in the number of transactions.
Looking closer at the three size segments, we note that when compared to the previous year there was an increase in the reported number of sales as follows:

75 % more Panamax sales

(2002 : 70 ships / 2001 : 40 ships)

144 % more Handymax sales

(2002 : 117 ships / 2001 : 48 ships)

86 % more Handysize sales

(2002 : 143 ships / 2001 : 77 ships)

It would seem that the Greek shipping community was quick to realise this trend and actively participated in purchasing vessels thus keeping the leading role amongst the buyers of second-hand bulk tonnage. Greek buyers bought about 165 vessels representing about 50 % of the reported sales in the three size categories under consideration.

Favourite amongst the Greek buyers proved to be the Panamax size for which they picked up about 64 % of the ships sold during the year, the Handymax category coming second with about 58 % of all transactions reported to Greek buyers, leaving the Handysize in the third place but with a respectable 35 % of the sales being reported to Greeks.

Chinese buyers were always present especially in the Handymax and Handysize segments the latter being their favourite 'hunting ground'.

Korean buyers where more active than in the past few years, especially in the latter part of 2002 going after ships in all three categories, although early 1980's built Panamax and Handymax ships seemed to have been what they were most keen on.

As one would expect when looking at sales for demolition, the number of ships reported sold for recycling during 2002 is significantly less than those sold during the previous year.

  • Panamax: about 0.9 million dwt was removed this year, 13 vessels, representing a decrease of about 60 % over 2001 figures.

  • Handymax: about 0.86 million dwt was removed during 2002, 20 vessels, representing a decrease of about 24 % over 2001 figures.

  • Handysize: about 2.12 million dwt were removed this year, 78 vessels, representing a decrease of about 15 % over 2001 figures.

Less ships going for recycling resulted in a sharp increase of prices obtained per light ton displacement from buyers of such tonnage which at the end of 2002 for a bulk carrier stands at about US$ 170-175 per ton.
 

  • Panamax

    A total of 70 ships were reported sold during 2002 and among these:

    • 1 ship was built in 1977 - she was sold for further trading to Indian buyers,

    • 49 ships were built in the 1980's (70 % of the reported sales), of which 14 were over 20 years old, 28 were 15-20 years old, 7 were 10-15 years old,

    • 19 ships were built in the 1990's (27 % of the reported sales), of which 14 were less than 10 years old,

    • 1 vessel was built in 2000 ' she was sold to Greek buyers.

    At the end of 2002 a 10 years old Panamax bulk carrier worth about US$ 11.75 / 12.0 million, representing an increase of about 30 / 33 % over a period of 12 months, a 5 years old Panamax bulk carrier worth about US$ 17.0 / 17.25 million, which represents about 28 % appreciation when compared to the value one year earlier in December 2001.

  • Handymax (35 000 ' 52 000 tpl)

    A total of 117 ships were reported sold during 2002 and among these:

    • 11 ships were built in the 1970's (about 9.5 % of the total Handymax sales), the oldest being a 1976-built vessel sold for further trading to Turkish buyers,

    • 67 ships were built in the 1980's (about 57 % of the total Handymax sales),
      ' 3 ships were over 20 years old,
      ' 59 ships were 15-20 years old,
      ' 5 ships were built 1988-1989,

    • 35 ships were built in the 90's (about 30 % of the total Handymax sales),
      ' 27 ships were 5-10 years old,
      ' 8 ships were 5 years old or younger,

    • 4 ships were built in 2000 representing about 3.5 % of the total Handymax sales.

At the end of 2002 a 10 years old Handymax bulk carrier worth about US$ 10.5 / 11.0 million, representing an increase of about 20 / 22 % over a period of 12 months, a 5 years old Handymax bulk carrier worth about US$ 14.25 / 14.5 million which represents a 16 % appreciation when compared to one year earlier in December 2001.

  • Handysize (18 000 ' 35 000 tpl)

    A total of 143 ships were reported sold during 2002 and among these:

    • 28 ships were built in the 1970's (about 19.6 % of the total Handy sales).

    • 86 ships were built in the 1980's (about 60 % of the total Handy sales)

    • 26 ships were over 20 years old,

    • 55 ships were 15-20 years old,

    • 5 ships were built 1988 / 89.

    • 28 ships were built in the 1990's (about 19.6 % of the total Handy sales)

    • 3 ships were over 10 years old,

    • 18 ships were 5 / 10 years old,

    • 7 ships were 5 years old or younger.

    • 1 ship was built in 2001, she was sold to Cuban interests.

    At the end of 2002 a 10 years old Handy bulk carrier worth about US$ 8.0 / 8.25 million, representing an increase of about 15 % over a period of 12 months, a 5 years old Handy bulk carrier worth about US$ 11.25 million, which represents a 7 % appreciation when compared to one year earlier in December 2001.

* * *

Concluding this review of the second-hand Panamax, Handymax and Handysize bulk carrier market and looking ahead, a lot will obviously depend on which way the freight markets will be heading for, but at the end of the year the feeling is that the dry bulk market maintains it's momentum and this should be felt on vessels' prices.

We would therefore expect values to remain firm with a slight upward trend over the next few months.
 

›››Archivo
DESDE LA PRIMERA PÁGINA
Puerto de Civitavecchia: El número de pasajeros de cruceros aumentó un 10,8% en el tercer trimestre; disminuyen los retrasos en la carga y el tráfico de buques ro-ro.
Civitavecchia
En los primeros nueve meses de 2026, el sistema portuario, con Fiumicino y Gaeta, cerró en 9,84 millones de toneladas (-1,3%).
En el tercer trimestre, los ingresos de la empresa francesa CMA CGM crecieron un +31,1%.
Marsella
El beneficio neto se triplicó. La flota transportó un número récord de contenedores.
Los puertos de Nápoles y Salerno registraron un aumento en el volumen de contenedores durante el segundo trimestre.
Nápoles
Se gestionaron 283.000 TEU (+7,8%). El total de carga aumentó un 4,7%. El tráfico de buques ro-ro se ralentizó y el tráfico de cruceros disminuyó.
Evergreen y WHL registran un fuerte crecimiento de sus ganancias trimestrales.
Taipéi
Las dos empresas taiwanesas han encargado 83.300 y 110.050 contenedores nuevos, respectivamente.
Los operadores de terminales se enfrentan: HHLA se ralentiza en el tercer trimestre, ICTSI acelera.
Hamburgo/Manila
La empresa alemana registró una caída del 8,5% en el tráfico de contenedores. ICTSI informó de un aumento del 8,1% (-1,8% en términos comparables).
Puerto de Hamburgo: El movimiento de contenedores se mantuvo estable en el tercer trimestre.
Hamburgo
Disminución del transporte de carga a granel. En los primeros nueve meses de 2026, el tráfico ascendió a 84,5 millones de toneladas (-2,6%).
Los pedidos de Fincantieri ascendieron a 3.570 millones de euros en el tercer trimestre, lo que supone un aumento del 180%.
Trieste
Los ingresos disminuyeron un 6%, hasta los 2.020 millones de euros, pero el EBITDA aumentó un 7%, hasta los 161 millones de euros.
Hapag-Lloyd registra un crecimiento trimestral de los ingresos del 27,9%, con un volumen de contenedores prácticamente sin cambios.
Hamburgo
La tarifa media de flete aumenta un 27,9% y respalda los resultados de la empresa alemana, que mejora aún más sus previsiones anuales.
HMM registra un tercer trimestre muy positivo tanto en el segmento de contenedores como en el de graneles.
Seúl
Durante ese período, la flota transportó 1,1 millones de contenedores (+8,4%).
La reforma que debía reducir la fragmentación de los puertos
Taranto
Desde la transición de 24 autoridades portuarias a 15 proveedores de servicios de publicidad (AdSP) hasta la entrada de Gallipoli en el sistema de Taranto: Italia continúa sumando puertos.
El puerto de Génova cerró el tercer trimestre con crecimiento, mientras que el tráfico de mercancías se mantuvo estable en Savona-Vado.
Génova
Puerto de Ravenna, septiembre ralentiza el ritmo
Rávena
En los primeros nueve meses de 2026, el tráfico de mercancías se mantiene por encima de los niveles del año pasado.
Estrecho del Bósforo: El tránsito de buques se desploma un 23,2%.
Ankara
El tráfico de buques graneleros se redujo a la mitad en el tercer trimestre. El descenso en los Dardanelos fue más moderado (-12,8%), mientras que el de buques portacontenedores se mantuvo estable.
En el tercer trimestre, las terminales de Eurokai gestionaron un tráfico récord de 3,9 millones de contenedores (+9,4%).
Hamburgo
En los primeros nueve meses de 2026, el total superó los 11,3 millones de TEU (+8,7%).
Sistema de comercio de derechos de emisión marítimos: Bruselas afirma que el sistema funciona. Los puertos temen la fuga de tráfico.
Bruselas
El último informe de la Comisión correspondiente a 2025 recoge una caída del 4 % en las emisiones y un cumplimiento superior al 99 %. Sin embargo, no aporta nuevos datos sobre el riesgo de evasión fiscal.
Los ingresos de Yang Ming crecieron un 52,4% en el tercer trimestre.
Keelung
Se prevé que las condiciones favorables para el transporte marítimo continúen durante la segunda mitad de 2026.
La flexibilización de las relaciones comerciales entre Estados Unidos y China también incluye puertos y astilleros.
Pekín
Pekín prorroga la suspensión de las tasas portuarias a los buques estadounidenses y la investigación sobre el impacto de las medidas estadounidenses en su industria marítima.
Alfa Laval adquiere Navtor por 700 millones de dólares.
Lund/Egersund
La empresa noruega que ofrece soluciones digitales para el transporte marítimo se integrará en la división Ocean del grupo sueco.
Boluda Towage adquiere la empresa holandesa de remolque Muller Dordrecht.
Dordrecht/Valencia
Cuenta con una flota de 16 remolcadores y ocho barcazas.
El mes pasado, el tránsito de buques por el Canal de Suez aumentó un 32,1%.
El Cairo
Crecimiento del +86,8% en tonelaje y del +94,1% en derechos de tránsito.
El ferrocarril, el espacio y el medio ambiente figuran entre las prioridades que surgen de las reuniones sobre el nuevo Plan de Ordenación Portuaria para los puertos de Génova y Savona-Vado.
Génova
La primera fase del proceso de consulta del AdSP ha concluido con 65 audiencias y la participación de más de 120 partes interesadas.
Fincantieri firma acuerdos con JA Solutions, Navantia y Naval Group.
París
Colaboración intensiva con la empresa danesa en el campo de los sistemas modulares y en contenedores avanzados para unidades navales reconfigurables.
Menos contenedores, más ingresos: la división marítima de Maersk crece al ritmo de las tarifas de flete.
Copenhague
En el tercer trimestre, los volúmenes cayeron un -0,8%, pero las tarifas y la congestión elevaron el EBIT de Ocean a 2.600 millones.
De Egipto a Marruecos, pasando por Gioia Tauro: ¿el ETS desvía los contenedores a puertos fuera de la UE?
Bruselas
Un estudio promovido por Assarmatori detecta indicios de transferencia ya en marcha y exige correcciones.
ONE buques transportaron volúmenes récord de contenedores en el tercer trimestre.
Singapur
Los ingresos aumentaron un 36,5%. Este desempeño se vio impulsado por la demanda de envíos transpacíficos.
Wallenius Wilhelmsen registra un tercer trimestre con ingresos récord que, sin embargo, crecen menos que los costos.
Lysaker
Ligera disminución en el volumen de vehículos transportados por la flota.
Canal de Suez: Señales de recuperación del tráfico marítimo en septiembre
Ismailia
Sin embargo, las repercusiones de la crisis en el Mar Rojo persisten.
En Taranto, la crisis del acero sigue lastrando el puerto.
Taranto
El transporte de carga líquida a granel está manteniendo los volúmenes, pero el tráfico general ha disminuido un 5,7 % en los primeros nueve meses de 2026. El tráfico de contenedores sigue siendo volátil.
Aranceles portuarios estadounidenses a buques chinos, coalición comercial pide suspensión permanente
Washington
Cientos de asociaciones han escrito a Greer antes de la fecha límite del 9 de enero de 2027. Entre ellas se encuentra el Consejo Mundial del Transporte Marítimo.
T&E: El ETS debería convertirse en el motor de las inversiones en combustibles sintéticos para aeronaves y buques.
Bruselas
Las exigencias de la organización para la reforma del ETS: más recursos europeos, un fondo específico y subastas bilaterales.
En el primer semestre de 2026, el tráfico de mercancías en el puerto de Livorno cayó un -3,6%.
Livorno
Los puertos de Elba también experimentaron un descenso (-3,3%). El puerto de Piombino, en cambio, se desmarcó de esta tendencia con un aumento del +5,7%.
El volumen de carga disminuyó en los puertos del sur del Adriático durante el primer semestre de 2026.
Bari
El sistema pierde 676 mil toneladas en comparación con 2025, casi todas entre los dos puertos más grandes.
En el tercer trimestre, el tráfico marítimo en el Canal de Panamá se mantuvo estable.
Panamá/Balboa
Sin embargo, el tonelaje de los buques y el volumen de mercancías en tránsito están aumentando.
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
El sistema marítimo de comercio de derechos de emisión (ETS) y FEPORT apoyan las medidas contra la evasión fiscal relacionadas con la carga.
Bruselas
Es la solución más eficaz —afirma la federación de operadores de terminales europeos— para proteger la competitividad de los puertos de la UE.
COSCO Shipping, ingresos +29% y beneficios +82%: el mérito se debe a las tarifas de flete, más que a los volúmenes.
Hong Kong
El mercado transpacífico es el motor que impulsa las cuentas del grupo chino.
Norwegian Cruise Line Holdings registra un aumento en sus ingresos netos, pero una disminución en sus márgenes durante el tercer trimestre.
Miami
APM Terminals firma una nueva fase de expansión para el puerto marroquí de Tánger Med.
Rabat
Se prevé una inversión de más de 800 millones de dólares para construir 1,2 kilómetros de muelles.
El puerto de Barcelona lanza un proyecto para reducir las terminales de cruceros de siete a cinco.
Barcelona
Revisión de la concesión de Creuers del Port de Barcelona
Boluda y Samskip, una nueva fusión en el transporte marítimo de corta distancia europeo.
Valencia/Róterdam
El grupo español ha firmado un acuerdo para adquirir todas las actividades del grupo holandés y ampliar su plataforma multimodal.
Astilleros indios en la lista de reciclaje de buques de la UE, ECSA pide a los eurodiputados que la aprueben.
Bruselas
Llamamiento para rechazar una moción que se opone a la propuesta de la Comisión.
CVC DIF ha adquirido una participación mayoritaria en el astillero español Cernaval.
Schiphol
La empresa ibérica emplea aproximadamente a 275 personas.
Contship Italia adquiere el grupo Tarros.
Melzo/La Spezia
Todas las actividades y activos que conforman el sistema de servicios integrados del grupo La Spezia cambian de manos.
El crucero residencial de Villa Vie Residences fue suspendido.
Fort Lauderdale/Sihanoukville
La compañía atribuye el encallamiento del buque al aumento del precio del combustible y está trabajando en un plan de reestructuración y recapitalización.
Wallenius Wilhelmsen encarga cuatro PCTC de 9.900 CEU más ocho opciones.
Lysaker
Acuerdo con el astillero chino Jinling Shipyard (Jiangsu)
Royal Caribbean registra ingresos trimestrales récord de 5.590 millones de dólares. Se revisan al alza las previsiones para el año completo 2026.
Miami
EBITDA de 2.530 millones y 2,68 millones de pasajeros en el período julio-septiembre
La seguridad marítima, el sistema de transporte de emisiones (ETS), los pabellones y el empleo son los temas centrales del informe del presidente de Confitarma.
Roma
Zanetti aboga por una alianza europea para la libertad de navegación, un pacto nacional para la transición y menos burocracia para la bandera italiana.
Global Ports Holding firma un acuerdo de concesión para el puerto de cruceros de San Vicente.
Estanbul
El acuerdo tiene una duración de 30 años.
La familia Sunde vende Color Line a Stena.
Gotemburgo
Un grupo sueco de ferris adquiere la mayor compañía de ferris de cruceros de Noruega.
Puertos chinos, la carrera se está ralentizando.
Pekín
Tras 25 años de crecimiento, el tráfico de mercancías está prácticamente paralizado, pero los contenedores siguen batiendo récords.
Lorenzo Sanna es el nuevo presidente de ANPAN
Sestri Levante
Parmigiani: En lo que respecta al Protocolo de Alta Mar, deberíamos retomar la declaración escrita del comandante.
2027 volverá a ser un año récord para la industria italiana de cruceros.
Livorno
Se prevé la llegada de aproximadamente 16 millones de pasajeros, con un crecimiento del +4%.
Reforma portuaria: la Comisión debate la posibilidad de reservar y rechazar únicamente buques.
Roma
La Cámara de Diputados no ha aprobado ninguna enmienda en tres semanas. La única excepción es el personal de la Autoridad Portuaria.
Transporte por carretera, tregua inminente. El gobierno libera fondos para combustible diésel y reformas estructurales.
Roma
Se aprueba un decreto de emergencia con créditos fiscales, prohibición de arrendamiento y protección contra el recargo por combustible.
La flota de portacontenedores y buques de transporte de automóviles de combustible dual supera las 500 unidades.
Washington
Un incremento del 41% en comparación con septiembre de 2025. Las inversiones del sector han superado los 200.000 millones de dólares.
Corredores marítimos verdes: China lidera la carrera.
Llevar a la fuerza
Casi una quinta parte de los proyectos de desarrollo a nivel mundial involucran un puerto chino. El informe del Foro Marítimo Global destaca el combustible y la colaboración como puntos fuertes, mientras que la demanda sigue siendo débil.
En el tercer trimestre, el tráfico de mercancías en los puertos españoles creció un +2,1%.
Madrid
La carga a granel está marcando la tendencia. La carga en contenedores se mantiene estable.
La UE invierte en la revolución verde de los mares.
Bruselas
Desde el amoníaco hasta el e-metanol, desde los transbordadores eléctricos hasta la captura de CO2: proyectos que están transformando el futuro del transporte marítimo europeo han recibido financiación.
Las asociaciones de transporte por carretera piden que se ponga fin a los bloqueos de carreteras en el sur del país.
Roma/Módena
Tras la reunión con Salvini, los sindicatos instaron a Piantedosi a intervenir. Ruote Libere respondió: escuche a los manifestantes, no los reprima.
APM Terminals y Hateco firman un acuerdo para desarrollar una red de terminales de carga ferroviaria en el norte de Vietnam.
Copenhague
La inversión inicial se estima en alrededor de 3.500 millones de dólares.
IFM Investors adquirirá las participaciones de CPPIB y OMERS en Associated British Ports.
Londres
Se ha alcanzado un acuerdo para la transferencia del 63,9% del capital del grupo portuario británico.
Los sectores de transporte marítimo y aéreo, y logística contractual impulsan el tercer trimestre, mientras que el transporte por carretera se ralentiza.
Copenhague
La división de carreteras sufre problemas tras la integración de Schenker.
Descarbonización del transporte marítimo: El Reino Unido debería aprender de los errores de FuelEU Maritime.
Londres
La Cámara Naviera del Reino Unido presenta al gobierno un documento con las lecciones aprendidas de los dos primeros años de aplicación del reglamento europeo.
El puerto de Amberes-Brujas vuelve al crecimiento en el tercer trimestre, con un aumento del 2,5% tras dos trimestres de descenso.
Amberes
Los contenedores, el transporte ro-ro y el transporte de graneles secos están impulsando la recuperación, mientras que el acero y los productos energéticos siguen atravesando dificultades.
El tráfico de contenedores en el puerto de Hong Kong aumentó un 12,9% en octubre.
Hong Kong
En los primeros diez meses de 2026 se gestionaron 11,15 millones de TEU (+3,5%).
Gulftainer y TiL construirán una terminal de contenedores en el puerto indonesio de Marunda.
Sharjah
Acuerdo con el PT indonesio Karya Citra Nusantara
Rosetti Marino firma un nuevo contrato para operaciones en alta mar en el mar Mediterráneo.
Rávena
El contrato está valorado en más de 400 millones de euros.
El sistema portuario de Liguria con Liguria International en Logitrans en Estambul
Estanbul
Se destacan servicios y proyectos para fortalecer las conexiones logísticas entre Turquía y el sur de Europa.
Boluda Towage adquiere la empresa ecuatoriana de remolque Cititug.
Valencia
La transacción incluye la transferencia de propiedad de cinco remolcadores.
El puerto de Los Ángeles establece un récord de tráfico de contenedores en octubre.
Los Ángeles
En los primeros diez meses de 2026 se gestionaron 9,11 millones de TEU (+5,1%).
En 2027, el puerto de Rávena prevé recibir 365.000 pasajeros de cruceros.
Rávena
Hasta la fecha, hay programadas 115 escalas de cruceros.
Giosuè Vezzuto nombrado director general de RINA Services
Génova
Los resultados financieros trimestrales de Finnlines muestran un fuerte crecimiento.
Helsinki
Los ingresos aumentaron un 26,2% en el período de julio a septiembre. Las ganancias aumentaron un 81,6%.
El Puerto de Tarragona ha ganado el Premio ESPO 2026.
Bruselas
El área que rodea la sede de la Autoridad Portuaria se ha convertido en un espacio sostenible, resiliente e intergeneracional.
En el tercer trimestre, el tráfico de carga en los puertos croatas creció un +18,5%.
Zagreb
El número de pasajeros de vuelos regulares se mantuvo estable, mientras que el de pasajeros de cruceros aumentó un 6,2%.
Tardino ha sido nombrado presidente del Comité de la ESPO para las Regiones Ultraperiféricas e Islas
Palermo
En Bruselas, reunión con Raffaele Fitto sobre cuestiones estratégicas de los puertos italianos.
La empresa danesa DFDS registra ingresos trimestrales récord
Copenhague
En el período julio-septiembre, los buques del grupo transportaron 10,1 millones de metros lineales de material rodante y 2,1 millones de pasajeros (-3,6%).
En los puertos montenegrinos, el volumen de carga está disminuyendo mientras que el de pasajeros está aumentando.
Podgorica
El tráfico con Italia está disminuyendo.
Ansis Zeltins ha sido reelegido presidente de la Organización Europea de Puertos Marítimos.
Bruselas
La Asociación de Puertos de Islandia se ha unido a ESPO.
Este año, Blu Navy registró un crecimiento del +12% en el número de pasajeros transportados.
Portoferraio
El número de vehículos transportados también aumentó (+11%).
El 17 de noviembre tendrá lugar en Rávena una conferencia sobre el presente y el futuro de las Autopistas Marítimas en Italia.
Rávena
En 1991 comenzó la línea marítima Ravenna-Catania.
Se celebra el compromiso del Partido Demócrata con las enmiendas relativas a las obras portuarias y marítimas.
Roma
Es la única fuerza política —subraya el sindicato— que ha respondido hasta ahora a nuestras solicitudes de reunión.
En los primeros nueve meses de 2026, el tráfico de contenedores en el puerto de Gioia Tauro creció un +1,7%.
Roma
Actualización económica del Banco de Italia sobre la economía de Calabria
FS Engineering y Sogesid han firmado un acuerdo para desarrollar proyectos de infraestructura en Italia y en el extranjero.
Roma
Enfoque nacional en la infraestructura portuaria, los sistemas logísticos y la infraestructura relacionada con la movilidad.
El Tribunal Administrativo Regional (TAR) del Lacio ha suspendido el aumento de las tasas de los centros de formación marítima.
Roma
Se ha concedido la solicitud de medidas cautelares presentada por CONFORMAR y ANIFORMAR. La audiencia sobre el fondo del asunto está programada para el 16 de marzo.
Los ingresos de Global Ship Lease aumentaron un 4,5% en el tercer trimestre de 2026.
Atenas
Nueva línea de crédito de 1.000 millones de dólares para financiar 15 nuevos buques portacontenedores.
El curso Papagno de Assagenti ha formado a más de mil jóvenes agentes y corredores marítimos.
Génova
Se ofrece a nivel nacional desde 2017.
AIRIDEA, una nueva conexión aérea entre Génova y Marsella con el apoyo de Genova Industrie Navali.
Génova
Servicio diseñado para facilitar los viajes relacionados con el trabajo entre las dos ciudades.
Fincantieri y Republikorp forman una empresa conjunta para fortalecer la industria de construcción naval de Indonesia.
París
El Propeller Club Port of Sardinia se fundó hoy en Cagliari.
Génova
Es el club número 27 de la asociación nacional, que cuenta con más de 1.600 miembros.
La empresa india Adani Ports adquiere al operador de terminales holandés Evos.
Ahmedabad/Ámsterdam
Transacción por valor de 2.560 millones de euros.
Hapag-Lloyd ha completado la adquisición de una participación del 25% en APM Terminals Maasvlakte II.
Hamburgo
La junta directiva de Interferry ha sido renovada.
Victoria
Nombramientos en la conferencia del 50 aniversario de la asociación en Bangkok.
DIS reporta un crecimiento en sus ganancias durante el tercer trimestre de 2026.
Luxemburgo
Tras el auge del segundo trimestre, la rentabilidad se mantiene en niveles altos.
Arsenio Domínguez seguirá al frente de la OMI hasta finales de 2031.
Londres
El Consejo ha tomado una decisión. El nombramiento debe ser ratificado por la asamblea.
DHL experimentó un crecimiento en el tercer trimestre, impulsado por los servicios de mensajería urgente y transporte de mercancías, que generaron ingresos y beneficios.
Bonn
Ingresos de 22.700 millones de euros (+12,6%) y EBIT de 1.700 millones de euros (+16,2%).
El Tribunal General de la UE ha anulado la retirada del reconocimiento del registro naval ruso.
Luxemburgo
La prohibición de inversiones y la prohibición de transacciones siguen vigentes.
El bioGNL italiano busca hacerse un hueco entre el ETS, FuelEU y los incentivos nacionales.
Rimini
Assogasliquidi solicita procedimientos de certificación más sencillos y medidas para que la producción nacional sea competitiva.
Fincantieri y Leonardo llegan a un acuerdo para reforzar el papel de Orizzonte Sistemi Navali.
Trieste/Roma
Las empresas pretenden consolidar el papel industrial y comercial de la empresa conjunta.
Puerto de Rijeka: Diversas cargas impulsan el avance de Luka Rijeka, mientras que la terminal de contenedores Adriatic Gate pierde terreno.
Rijeka
En los primeros nueve meses de 2026, el tráfico total cayó un -15% hasta los 3,83 millones de toneladas.
Confetra: El gobierno quiere abolir el impuesto sobre las parcelas pequeñas.
Roma
Satisfacción con las decisiones del gobierno en el proyecto de ley de presupuesto.
Se ha establecido una comunidad portuaria de energías renovables en Taranto.
Taranto
Entre los objetivos, destaca el desarrollo del puerto de Apulia como centro energético.
Filt y Uilt, el sistema de trabajo portuario temporal no es anacrónico.
Roma
Definirlo de esta manera —denuncian los sindicatos— significa distorsionar la naturaleza y la función del artículo 17 de la Ley 84/94.
Nuevo récord trimestral de tráfico de mercancías en los puertos albaneses.
Tirana
En el período julio-septiembre, el número de pasajeros disminuyó un -5,4%.
PROXIMAS SALIDAS
Visual Sailing List
Salida
Destinación:
- orden alfabético
- nación
- aréa geogràfica
Los beneficios de FedEx están aumentando, pero el beneficio neto cae un 68%.
Memphis
La pérdida de capital no monetaria relacionada con la escisión de FedEx Freight pesa mucho
Kalmar registró un crecimiento del 22% en nuevos pedidos en el tercer trimestre.
Helsinki
Facturación estable. Beneficio neto un 14% inferior.
En el tercer trimestre, las ventas de contenedores producidos por CIMC aumentaron un 30%.
Hong Kong
La actividad comercial se vio impulsada por los contenedores secos (+36%). Las unidades refrigeradas disminuyeron un 28%.
Puertos, nuevas inversiones en Toscana y Cerdeña
Livorno/Cagliari
Se han aprobado los presupuestos para 2027 de las dos autoridades portuarias. Entre los proyectos más destacados se incluyen el muelle de Piombino, las obras en Livorno y los proyectos de dragado y electrificación en los puertos de Cerdeña.
Encontrar personal cualificado en los puertos italianos es cada vez más difícil.
Nápoles
Un análisis realizado por Randstad Research de 13 perfiles profesionales también pone de manifiesto un marcado desequilibrio de género.
COSCO Shipping Ports registra ingresos récord en el tercer trimestre.
Hong Kong
En el período de julio a septiembre, el beneficio neto fue de 102,5 millones de dólares (+3,4%).
Aprobación del presupuesto previsto para 2027 y del Plan Operativo de Transporte (POT) para el periodo 2027-2029 de la Autoridad Portuaria del Sur del Mar Tirreno y Jónico.
Gioia Tauro
El documento de previsiones muestra unos ingresos de aproximadamente 24 millones de euros y unos gastos de aproximadamente 88 millones.
Bongiovanni, natural de Ravenna, ha sido confirmado como presidente del Comité Juvenil de la Federación.
Roma
Renovación de la junta directiva de la federación
Se ha aprobado el Plan Operativo Trienal 2027-2029 para el Sistema Portuario del Adriático Central.
Ancona
Se prevén inversiones por valor de 308 millones de euros, de los cuales 218 millones se destinarán a la región de Las Marcas y 91 millones a Abruzzo.
Se ha aprobado el presupuesto previsto para 2027 de la Autoridad Portuaria de Liguria Occidental.
Génova
El nuevo recargo sobre los productos se pospone hasta 2028.
DP World inaugura un almacén con temperatura controlada cerca de Bolonia.
Bolonia
Superficie de 22 mil metros cuadrados
Saipem gana dos nuevos contratos de perforación en alta mar.
Milán
El valor total de los pedidos asciende a aproximadamente 121 millones de dólares.
Hanwha pone el astillero naval de Filadelfia bajo el control de la División de Defensa.
Arlington
El objetivo es integrar la construcción de buques comerciales y militares.
Los puertos de La Spezia y Carrara aprueban el Programa Trienal de Obras Públicas 2027-2029 y el Presupuesto 2027.
La Spezia
Pisano: PTLP concreto y coherente con los recursos actualmente disponibles.
Concesiones portuarias: El Tribunal Administrativo Regional (TAR) bloquea el aumento de tarifas de 2025.
Roma
Se ha aceptado el recurso presentado por Assiterminal y dieciséis empresas portuarias.
Wärtsilä registra aumentos trimestrales en los pedidos, pero no en el segmento marítimo.
Helsinki
En el periodo julio-septiembre la empresa registró un beneficio neto de 125 millones de euros (-31%).
Montaresi fue nombrado secretario general de la Autoridad Portuaria del Mar de Liguria Oriental por otros cuatro años.
La Spezia
Renovación del mandato a propuesta del Presidente Pisano
Doble ceremonia para dos barcos de Explora Journeys en el astillero Fincantieri en Génova.
Génova
Lanzamiento del "Explora V" y ceremonia de colocación de la primera moneda del "Explora VI".
La empresa italiana CMD pasa a estar bajo el control del grupo emiratí EDGE.
Abu Dabi/Roma
Los primos Mariano y Giorgio Negri conservan una participación significativa.
La Autoridad Portuaria del Tirreno Septentrional presenta el nuevo diseño del puerto de Piombino.
Livorno
Gariglio: Un paso concreto hacia la reconversión industrial y el futuro de Piombino.
FS Logistix ha adquirido seis nuevas locomotoras CZ LOKO para servicios de transporte de mercancías y maniobras.
Roma/Praga
Este es el cuarto pedido de este tipo que recibe la empresa checa en diez años.
Puerto de Bremerhaven: El crucero Mein Schiff 3 colisionó con dos buques portacontenedores.
Bremen
No hubo heridos. El crucero fue cancelado.
Paolo Moretti ha sido nombrado consejero delegado de RINA Spa.
Génova
Giosuè Vezzuto ha asumido el cargo de director ejecutivo de RINA Services.
HD Hyundai y Kiewit establecerán una empresa conjunta en un nuevo astillero en Estados Unidos.
Houston/Seúl
Está prevista la construcción de buques tanto militares como comerciales.
Los pedidos trimestrales de equipos portuarios de Konecranes disminuyen a medida que aumentan los ingresos.
Helsinki
El tercer trimestre de Kuehne+Nagel fue muy positivo.
Schindellegi
Crecimiento de los resultados económicos y operativos en todos los segmentos de negocio.
La apuesta de Wildcat por la defensa estadounidense: acuerdo exclusivo con el histórico astillero de Fraser.
Superior
El funcionamiento del fondo de Miami Beach forma parte del plan del gobierno para relanzar la industria naval estadounidense.
Puerto de Ancona: Se emite la primera autorización ZES individual.
Ancona
Se ha desbloqueado una inversión de tres millones de euros en la construcción de yates.
PUERTOS
Puertos italianos:
Ancona Génova Rávena
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Liorna Taranto
Cagliari Nápoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venecia
Interpuertos Italianos: lista Puertos del mundo: Mapa
BANCO DE DATOS
Armadores Reparadores navales y astilleros
Expedicionarios Abastecedores de bordo
Agencias marítimas Transportistas
MEETINGS
El 17 de noviembre tendrá lugar en Rávena una conferencia sobre el presente y el futuro de las Autopistas Marítimas en Italia.
Rávena
En 1991 comenzó la línea marítima Ravenna-Catania.
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
››› Archivo
RESEÑA DE LA PRENSA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Reseña de la Prensa Archivo
FORUM de lo shipping y
de la logística
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› Archivo
El acceso al puerto de Ravenna está autorizado para buques con un calado máximo de 11,00 metros.
Rávena
Benevolente: es un paso fundamental para el desarrollo económico y estratégico del aeropuerto.
El puerto de Génova extiende la autorización de inspección de alimentos a la terminal PSA SECH.
Génova
La disposición del Ministerio de Salud amplía las categorías de productos que pueden estar sujetos a control.
El jueves, la Unione Interporti Riuniti presentará el proyecto ELODIE en la Cámara de Diputados.
Roma
El objetivo es crear una federación digital de interpuertos.
ABB registra pedidos récord por valor de 12.000 millones de dólares en el tercer trimestre.
Zúrich
Los ingresos y las ganancias también aumentaron, mientras que el grupo anunció una empresa conjunta con Mitsubishi Electric.
En el tercer trimestre de 2026, el volumen de contenedores en el puerto de Barcelona disminuyó un -9,2%.
Barcelona
El descenso se debió a una reducción del 19,9% en el tráfico de transbordo.
Las terminales de COSCO Shipping Ports establecen un nuevo récord trimestral de procesamiento de contenedores.
Hong Kong
En el período julio-septiembre también los volúmenes manejados por CMPort
En agosto, los puertos de Liguria Occidental gestionaron 5,2 millones de toneladas de mercancías (+1,6).
Génova
En Génova se registró un aumento del +6,1%, mientras que Savona-Vado Ligure sufrió un descenso del -10,0%.
Raben Italia abre un nuevo almacén en Pomezia.
Milán
El objetivo es consolidar el posicionamiento y la expansión territorial en el transporte por carretera.
El puerto de La Spezia firma un acuerdo para desarrollar proyectos de economía azul y seguridad.
La Spezia
Fue firmado por la AdSP y la Fundación del Centro Nacional de la Dimensión Subacuática.
El puerto de Long Beach celebra un nuevo récord mensual de movimiento de contenedores.
Playa larga
Nuevo máximo histórico también en el trimestre de julio a septiembre.
Se ha abierto la licitación para la demolición parcial del muelle norte del puerto de Ancona.
Ancona
La intervención incluye la regularización de los fondos marinos correspondientes.
HMM invierte más de 1.600 millones de dólares en 12 nuevos buques portacontenedores.
Busan
Para 2029, se entregarán ocho buques de 13.000 TEU, tres buques de 2.800 TEU y un buque de 1.700 TEU.
Paolo Pessina confirmado como presidente de Federagenti
Roma
Votación unánime de la asamblea de la Federación
Han comenzado las negociaciones para renovar el convenio colectivo único del sector naviero.
Roma
Las partes han acordado un intenso calendario de reuniones.
Formación marítima: Apelación ante el Tribunal Administrativo Regional (TAR) contra el aumento de tarifas de la Autoridad Portuaria.
Roma
El tráfico de contenedores en el puerto de Hong Kong creció un 15,1% en el tercer trimestre.
Hong Kong
En septiembre el aumento fue del +25,0%.
El Grupo Spinelli ha inaugurado un nuevo depósito de contenedores vacíos en Novi Ligure.
Génova
Inversión por valor de 14 millones de euros.
Rhenus integra sus servicios logísticos en un único centro logístico en el Interporto de Padua.
Padua
El complejo reunirá transporte por carretera, transporte aéreo y marítimo, almacenamiento y servicios especializados.
- Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA
tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Director: Bruno Bellio
Prohibida la reproducción, total o parcial, sin el explicito consentimento del editor
Búsqueda en inforMARE Presentación
Feed RSS Espacios publicitarios

inforMARE en Pdf
Móvil