testata inforMARE
Cerca
14. Oktober 2026 - Jahr XXX
Unabhängige Zeitung zu Wirtschaft und Verkehrspolitik
00:45 GMT+2
LinkedInXFacebook
FORUM über Shipping
und Logistik


Outlook

In our previous report, we anticipated that freight levels would hold for 2001 and 2002 before a probable dropping off in 2003 given the massive number of newbuildings then appearing.

With the world economic climate suddenly wavering between stagnation and depression, and an America unexpectedly facing the woes of unemployment, compounded by terrorist attacks putting at stake its supremacy, freight rates have got sucked into a downward spiral which is certainly overdone.

The question is to know whether this is a mechanical phenomenon which is justified and long lasting or, on the contrary, simply a strong reaction which will enable the market to recover a healthy balance quicker than expected. We think this second hypothesis to be more likely.

Many experts believe that the United-States will recover from the dramatic events of September 11th stronger than before, and that growth will pick up again after the second quarter of 2002. The role that the world's most important economic power plays in terms of energy consumption will be confirmed and it is likely in addition that we shall see a decline in the use of nuclear energy.

Despite efforts of producing countries to push up oil prices, the world producing capacity today is such that the oil price is unlikely to go over $25 per barrel. This is another factor in favour of a rapid economic recovery.

The high freight rates registered in 2000 and in the beginning of 2001 acted as a brake for any voluntary scrapping of the oldest vessels. However, faced with depressed rates such as we have currently, their employment should be increasingly dubious.

Given that today we have already witnessed a serious decline in the number of orders of newbuildings for the three main categories of tankers, we should see an increase in the number of vessels over 20 years heading for the scrapyard. The return of a better balance between supply and demand could therefore occur in a far shorter time than predicted by many.

The second-hand oil tanker market 

Last year's revue concluded by drawing the reader's attention to the trend towards a slowing down in world growth and the repercussions that this would have on the value of ships built in the 70's and 80's. This perception was revealed to be accurate, or more honestly partially so, as in fact all ages of ships suffered a drop in value even if older ships were the most affected.

The year 2001 saw an impressive number of transactions, at the end of the year we have listed about 140 second-hand sales of ships for navigation or transformation (and thus excluding demolition). In comparison, the total of ships transacted in 2000 was 126 and in 1999 only 98. This figure of 140 is however slightly misleading as a considerable number of transactions were done "en bloc" and it is primarily by this yardstick that one can measure the effects of mergers and regroupings within the shipowning world.

Values have declined due to a drop in ships' revenues for all sizes, the systematic compressing of construction costs offered by yards, and by charterers taking a control of the market at the expense of owners. Just as at the end of 1998 and during 1999, charterers can again pay themselves the luxury of deciding arbitrarily whether to reject older ships without risk of paying a heavy premium for a modern ship. It is for this reason that no matter what the size, ships of the 70's and 80's have seen their value drop by more than 45 % during the course of the year, whereas modern units and double-hulls have lost between 20 to 25 % of their value.

Prices remained firm at the beginning of the year but collapsed as the steady decline in daily revenues was being realised and slipped further after the events of September. We should like to point out certain tendencies which characterise this sector but which are also present in other types of tonnage:

  • The cyclical rise and fall of values are getting shorter not only because of the instability of our economies but also due to the shorter reaction time of the players be they owners, charterers, or builders.
  • If the concentration of tonnage in the various pools helps push the market on its way up, they do not seem capable of slowing it down on the falls.
  • Different types of owners exist and their varying time horizons contradict their objectives, which are equally different. Consequently, those who are under obligation to always produce profits in the short term, tend to amplify the movements of the market.
  • The sellers' ability to resist their counterparts when values are declining seems stronger than the resistance of buyers when values are rising.

The year 2002 appears to be starting out as difficult times for owners. The asset worth has fallen to levels of 1999 and a large number of ships are due to come into service for the Aframax and the Panamax fleets. The demolition of the oldest units is inevitable in the short-term, but the revenues of the old ships are often the means of financing the costs of their new ships.

Experience shows that the tonnage on offer has not and should not be the problem. The really essential factor is demand and it is this demand that we should try to determine as best as possible. Although we can not be categorical in our forecasts, we would nonetheless give some suggestions to potential investors:

  • with modern ships, to seriously look at the possibility of buying "resales" (with equivalent specification) rather than systematically ordering new ships,
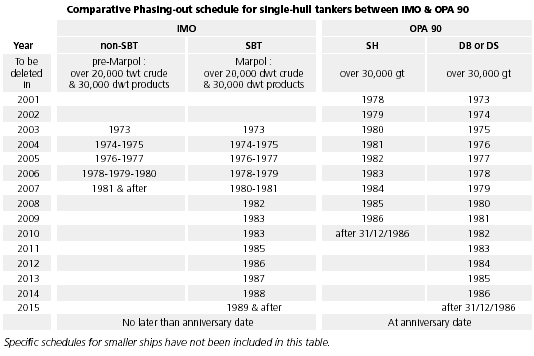
  • with older ships, to keep in mind the comparative table of phasing-out given above.
  • phasing-out
     
     The second-hand market for VLCCs

    This sector of the market saw 37 units change hands, namely five times more than last year. The main player in this was Frontline (directly or via the Tankers International pool), since it seems that 13 ships out of the 37 involved this owner. The fluctuating values allowed certain to realise brilliant operations in terms of timing. For example Bergesen was able to sell for nearly $78 million per unit, several of his ships which he had bought for less than $65 million a year before. As mentioned above, a number of sales were done "en bloc", 17 ships out of the total 37 transactions changed hands in this manner. The most noteworthy without doubt being the sale of four - m/t ‘Hellespont Burnside', m/t ‘Hellespont Elmere', m/t ‘Hellespont Holly', m/t ‘Hellespont Sheridan' of 305,000 dwt built by Samsung, for delivery in 2001 and 2002 to the National Shipping Company of Saudi Arabia for a price of $82.5 million per vessel.

    Out of 18 ships sold this year, built after 1990, all except four were double-hulled and were less than three years (newbuilding resales included). Among the four single-hulled, was the sale "en bloc" of the m/t ‘Front Tarim' and the ‘Front Tartar' of 306,902 dwt built in March 1993, for a combined price of $104 million with three years charter at $38,000 per day.

    Ten ships built between 1980 and 1989 changed hands and to illustrate the drop in prices, we can cite the sale of the single-hulls with the m/t ‘Isuzugawa Maru' of 247,392 dwt built in 1987 for $28.5 million in February, whilst the m/t ‘Cosmo Jupiter' of 248,965 dwt built in 1986 achieved $18.9 million in October. Owners of ships in good running order and built in the 70's have managed to survive with honours in the current skirmishing. Out of the nine ships sold from this decade, seven were converted into FSO or FPSO. Thus the t/t ‘Stena Companion' allowed her owners to obtain over twice the price of her scrap value, achieving nearly $15 million in September.

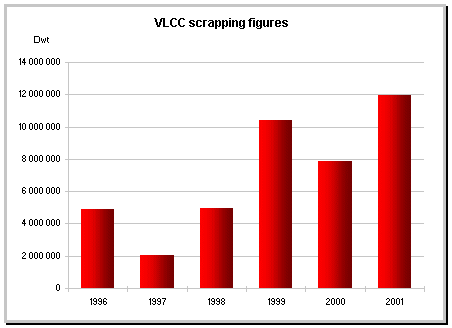
    Although a final reckoning still remains to be done, it seems that at time of press, around 30 ULCC/VLCC have been sold for demolition. It is worth pointing out however that the rhythm of scrapping has been increasing in pace over the past months and that in the last two months of this year the activity was hectic. This tendency should continue even to accelerate right throughout 2002, and in any case to last at least as long as rates are under pressure. The price per light ton has also diminished and while it was possible to obtain about $170 per light ton at the beginning of the year, it finished at the end of the year at somewhere near $135 per ton.

    Vlcc scrapping

     The Suezmax second-hand market

    The volume of activity during these last years has remained extremely stable for this type of ship. We noted 23 transactions per year for 1999 as well as 2000, and this year the number changing hands has been 24. In the same way as with VLCCs, the number of ships sold "en bloc" was also significant, since a third of the 24 ships (namely eight) were subject to two grouped sales. The more important of the two was that which consisted of five resales, the ‘Hyundai 1351', ‘Hyundai 1350', ‘Hyundai 1336', ‘Hyundai 1335', ‘Hyundai 1334', and ‘Hyundai 1333' for delivery in 2002 / 2003 and sold during the summer for $330 million en bloc.

    We have seen however that activity is essentially concentrated on very modern ships. Ten resales, added to five ships built between 2000 and 2001, then a single unit built in 1993, represented two-thirds of the sale and purchase deals in this sector. Several of these units have changed hands with charter back attached, such as the m/t Four Smile' 160,573 dwt built in 2001, which was sold for a price of about $60 million with a five year charter back at $27,500 per day. To our knowledge the only ship sold from the 90's was the m/t ‘Polysymphony' 150,038 dwt built in 1993, which went at the beginning of the year for $41 million.

    No ship built between 1980 and 1989 was sold and the remaining transactions were for units built in the 70's. As in the VLCC category, with freight rates collapsing during the year, buyers were especially active at the beginning of the year since five of the seven transactions were done in the first half of 2001. Thus the m/t ‘Enalios Thetis' of 149,992 dwt built in 1979 was able to achieve a price of $6.5 million in February whereas in mid- November the m/t ‘Elfwaihat' built in 1976 was sold at a level very close to its scrap value, of about $3.2 million.

    The demolition figures were impressive, as 28 ships were taken off to the Far East. This is a level comparable to that of 1999 in which 26 ships were withdrawn from the market. The attractive freight rates in 2000 only produced 16 demolitions. As with all size of tankers for this year, sales of Suezmax for scrapping became more numerous as the year progressed.

    The second-hand market for Aframax et Panamax

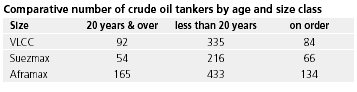
    In the Aframax market we have seen in 2001 a similar volume of activity to that of last year's, namely 34 sales as compared to 36, which pales against the figure of 50 achieved in 1999. This figure is relatively small if we take into account the total number of ships comprising the active fleet namely 540 units. As a matter of fact, the division by age which has been relatively stable and balanced since the 70's up till now, should allow greater movement and flexibility in this market, in contrast to the VLCC and Suezmax categories which suffer from a lack of tonnage built in the 80's.

    The sale of modern ships played a significant part as 16 of the 34 deals concerned ships under 10 years, all double-hulled bar one. Several sales "en bloc" were also achieved of which the m/t ‘Astro Saturn' and the m/t ‘Astro Maria' of 105,690 dwt, both built in 1999, went for a price of $45 million per ship in May. In comparison and to illustrate the progressive drop in the market all through the year, we can mention the sale of the ‘resale' ‘Samho S141' for delivery 2002, which changed hands in November for a price of $39.5 million.

    Fourteen units built between 1980 and 1991 were sold and once again those with SBT were able to extract a higher price. The value of these ships has nonetheless been badly hit. We have seen the sale of the m/t ‘Magnolia', 84,656 dwt built in 1983, for a price in the region of $11.7 million in January, whereas a seller had to accept in November a price of $7 million for each of the m/t ‘Winamac', m/t ‘Wapello' and m/t ‘Waneta', in addition to taking them back under charter for a three year period at a reported rate of $14,000 per day. Only five ships built between 1975 and 1979 changed hands to continue employment. The last to date as we write has been the m/t ‘Orapin Ocean' of 81,269 dwt built in 1976 who had her classification renewed in January of this year and which achieved a price of $3 million in December.

    We have counted 19 Aframax which have been sent to the scrapyard. Unlike the VLCC and Suezmax, demolition figures show no noticeable change over 2000, which saw 18 and 1999 with 20. This is hardly surprising as this category of ship has been able to weather the lowering of freight rates better than others and even the older units give respectable daily returns East of Suez.

    As to the Panamax sector there is renewed life and vitality, but above all it is the favourite of second-hand buyers. We wish that this trend will last, as the orderbook for newbuildings has seen on its side a substantial increase with 42 ships in 2001 against only 13 last year. The volume of sales reached 27 ships of 50,000 to 75,000 dwt this year, some 11 more than in 2000. It should be pointed out that five of these 27 Panamax had a width over 32.2 metres. The breakdown of sales by age bracket was relatively balanced. Thus seven of less than ten years were sold, and the most noteworthy sale without doubt was that of the m/t ‘Maya', m/t ‘Aztec', and the m/t ‘Inca' of 68,467 dwt built in 2001, for a price per ship of $42 million in July.

    Ten other units built between 1980 and 1989 changed hands. For example in May the m/t ‘Minerva' and the m/t ‘Andromeda' of 63,953 dwt built in 1984 were sold en bloc for a total price of $26 million. The other ten remaining sales related to ships built in the 70's, and the last to date was that of the m/t ‘Sealion I' of 59,250 dwt built in 1977, which obtained a price in the order of $3.7 million, having passed her special survey. There were only seven ships sold for demolition in this category in 2001, as compared to eight last year and this was a satisfactory figure given that only four new units entered the fleet in 2001. The challenge is of another order for next year.

     The second-hand market for OBOs

    With 11 ships sold during the course of the year, the volume of sales in this category has remained stable since 10 ships changed hands last year. No less than seven of these, the ‘SCF Spirit', ‘SCF Trust', ‘SCF Star', ‘SCF Champion', ‘SCF Endurance', ‘SCF Challenger', and ‘SCF Trader' of 95,000 dwt built between 1991 and 1992, were sold en bloc for a total sum of $210 million during the summer to the great satisfaction of the sellers (and that doubtless only possible) due to the thinness of the market. The four other ships sold, date all from 1981 or 1982, and we can give as example the sale of the ‘OBO Panoil' of 70,637 dwt built in 1981, in June at a price of $5.5 million.

    Elsewhere, 11 OBO ships were demolished this year, their sizes ranging from 72,000 dwt to 172,000 dwt, having been built between 1974 and 1978. Currently some 140 ships of this type whose tonnage exceeds 50,000 dwt remain in service, even if not all have the ability to carry oil products in their present state.


    Shipping and Shipbuilding Markets in 2001

    I N D E X

    ›››Archiv
    Emanuele Grimaldi ist der neue Präsident der Malta International Shipowners Association.
    Valletta
    Sie übernimmt das Amt von Marily Frangista, die den Verband seit April 2022 geleitet hat.
    Die vierte Ausgabe der Green Logistics Expo startet morgen früh in Padua.
    Padua
    Es werden über 300 Aussteller teilnehmen und 30 Konferenzveranstaltungen stattfinden.
    Im dritten Quartal dieses Jahres ging der Güterverkehr in türkischen Häfen um 1,1 % zurück.
    Ankara
    Das Frachtaufkommen von und nach Italien stieg um 6,2 %.
    Assiterminal, die Flexibilität der PRPs sollte den jeweiligen Markt berücksichtigen, in dem die Häfen tätig sind.
    Genua
    Cetus Maritime plant einen Börsengang an der Euronext Growth Oslo.
    Hongkong
    Erwerb von 16 Schiffen in Vorbereitung auf den Börsengang
    Am Samstag kollidierte ein US-amerikanisches Kampfflugzeug mit einem Massengutfrachter im Golf von Oman.
    Tampa
    Centcom: Das Schiff hatte versucht, eine Seeblockade gegen den Iran durchzusetzen.
    Schiff in der Nähe der Straße von Hormuz gerammt
    Southampton
    Eine Kugel löste ein Feuer aus, das später gelöscht wurde.
    OOCL meldet ein Wachstum des Schiffsfrachtvolumens um 9,0 % im dritten Quartal.
    Hongkong
    Der Anstieg der Seefrachtraten führt zu einem Umsatzanstieg von +45,1 %.
    HD Hyundai Marine Solutions übernimmt das amerikanische Unternehmen Goldens Worldwide
    Dubai/Seongnam
    Das Unternehmen befasst sich mit der Reparatur und Wartung von großen Schiffsmotoren und Industriemaschinen.
    UNATRAS an die Regierung: Geben Sie unverzüglich die Maßnahmen zur Senkung der Dieselpreise frei.
    Rom
    Die Verbände des Straßenverkehrs berichten von Verzögerungen und Unsicherheiten bei der Umsetzung des Abkommens vom 22. Mai und fordern ein dringendes Treffen.
    Hafen von Taranto: Gugliotti erneuert seine Forderung an die Regierung nach finanzieller Unterstützung für den Windpark des Hafens.
    Taranto
    Das Projekt – so betonte er – könne weder verkleinert noch verschoben werden.
    Angriff auf ein Schiff mitten im Persischen Golf
    Southampton
    Die UKMTO berichtete, dass mehrere Geschosse zu Opfern unter den Besatzungsmitgliedern geführt hätten.
    Gioia Tauro: Nachtrag zum aktualisierten Hafenplan genehmigt
    Gioia Tauro
    Die Analyse wird es uns ermöglichen, den Personalbedarf der Hafenbehörde zu ermitteln.
    Schiffe in der Schlange, Treibstoffverschwendung: Wie Sie durch Warten vor Anker Geld sparen können.
    Kopenhagen
    Das Global Maritime Forum veröffentlicht die Testergebnisse von Cargill aus 16 realen Seereisen. Langsameres Fahren und Anlegen bei freiem Liegeplatz reduzieren Treibstoffverbrauch und Emissionen.
    ZIM hebt Prognose für das Gesamtjahr 2026 an
    Haifa
    Das bereinigte EBITDA und EBIT werden voraussichtlich 2,7 Milliarden US-Dollar/3,0 Milliarden US-Dollar bzw. 1,4 Milliarden US-Dollar/1,7 Milliarden US-Dollar betragen.
    Gabriele Sangiorgi wurde zum amtierenden Generalsekretär der Hafenbehörde von Ravenna ernannt.
    Ravenna
    Die Amtszeit von Fabio Maletti ist abgelaufen.
    Hafen von Genua: Die Arbeiter des Messina-Terminals streiken seit einem Monat eine Stunde lang.
    Genua
    Das Unternehmen meldet, dass eines der Gewerkschaftsmitglieder bei der letzten Sitzung nicht erschienen ist, obwohl dies Teil des im nationalen Tarifvertrag vorgesehenen Abkühlungsverfahrens ist.
    Hafen von Taranto, Vereinbarung zur Beteiligung an der Entwicklung des Valbasento Interporto in Ferrandina.
    Matera/Taranto
    Innerhalb von 180 Tagen wird ein logistisch-funktionaler Masterplan entwickelt.
    In Attika wird das Defizit hauptsächlich dank Kapitalgewinnen und Deckungszuwächsen reduziert.
    Kallithea
    Erste Jahreshälfte mit weniger Überfahrten und leicht steigenden Einnahmen
    Seit Jahresbeginn haben sich die Passagier- und Güterbeförderung auf den Schiffen von GNV um 2 % bzw. 5 % erhöht.
    Marrakesch
    Dreijährige strategische Partnerschaft mit dem Office National Marocain du Tourisme
    Escola Europea – Intermodal Transport feiert ihr 20-jähriges Jubiläum
    Barcelona
    Eine Mittelmeerreise zwischen Barcelona, Civitavecchia, Palermo und Genua.
    Filt Cgil erkennt die Arbeit in der Schifffahrt und im Hafen als anstrengend an
    Rom
    Die Gewerkschaft fordert, dass eine klare Regelung in das nächste Haushaltsgesetz aufgenommen wird.
    Tanker in Hormuz angegriffen
    Southampton
    Das Gerät setzte seine Navigation regelmäßig fort.
    FS Logistix und Interporto Bologna präsentierten den ersten italienischen experimentellen DAC-Zug
    Assologistica-Veranstaltung zur Diskussion der Mittelmeerstrategie für die italienische Wettbewerbsfähigkeit
    Rom
    Es findet am 30. Oktober nächsten Jahres in Neapel statt.
    Sanilog startet eine spezielle Kampagne zur Krebsprävention.
    Rom
    Drei neue Bereiche widmen sich der Prävention von Kopf-Hals- und Mundhöhlenkrebs sowie der Beurteilung des Gefäßrisikos.
    Der Auftrag für die Ausbaggerung und die Fertigstellung der Elektrifizierung der Docks im Hafen von Gioia Tauro wurde vergeben.
    Gioia Tauro
    Sie werden jeweils von Dravo und RTI Saet-Suardi durchgeführt.
    Preis für studentische Schiffsarchitektur in Genua verliehen
    Genua
    Die d'Amico Group und die Royal Institution of Naval Architects zeichnen herausragende Leistungen im Schiffbau aus.
    Der Gütertransport ist für Malta teurer: 35 Millionen Euro pro Jahr zwischen ETS, FuelEU und BAF.
    Zebbug
    Der Speditionsverband fordert die Regierung auf, eine für den Kontinent konzipierte europäische Politik in Frage zu stellen.
    CMA CGM hat die Übernahme von FedEx Supply Chain abgeschlossen.
    Marseille/Atlanta
    Durch die Transaktion hat sich die Präsenz von CEVA Logistics in Nordamerika verdreifacht.
    NÄCHSTE ABFAHRSTERMINE
    Visual Sailing List
    Abfahrt
    Ankunft:
    - Alphabetische Liste
    - Nationen
    - Geographische Lage
    Contships bestellt 10 Zubringerschiffe mit Optionen auf weitere 10+10.
    Athen
    Absichtserklärung mit der chinesischen Hubei Guangji Green Energy Shipbuilding Group Co.
    DP World unterzeichnet Abkommen zur Entwicklung eines Tiefseehafens im nigerianischen Bundesstaat Ogun.
    Dubai
    Das Projekt umfasst rund vier Kilometer Docks.
    Neue Hafenbestimmungen für Civitavecchia, Fiumicino und Gaeta wurden verabschiedet.
    Civitavecchia
    Die Verfahrensvereinbarung mit Interminal in Gaeta wurde genehmigt.
    Kotug erwirbt Mehrheitsbeteiligung an Vortex Offshore
    Rotterdam
    Das in Dubai ansässige Unternehmen bietet maritime Dienstleistungen für die Offshore-Industrie im Nahen Osten an.
    Über 1,9 Milliarden Euro in Spanien zur Verbesserung der Straßen- und Schienenverbindungen zwischen den Häfen
    Madrid
    Die Hafenbehörden werden 875,1 Millionen Euro beisteuern.
    Attica Holdings verkaufte das Ro-Pax-Schiff Levka Ori für 8,3 Millionen Euro.
    Kallithea
    Die Fähre wurde 1987 gebaut.
    Der RoRo-Dienst Triest-Damietta von DFDS wird ab Mitte Oktober alle zwei Wochen angeboten
    Kopenhagen
    Ein zweites Schiff in die Route einführen
    Die italienische Handelsmarineakademie verstärkt die Zusammenarbeit mit dem Hafen von Durrës.
    Genua
    Eine Absichtserklärung wurde unterzeichnet
    Am Freitag wird in Livorno ein Buch über die Geschichte des toskanischen Hafensystems vorgestellt.
    Livorno
    Ein Vergleich der Akteure im Hafensektor: von den Reformen der 1990er Jahre bis zu den Herausforderungen der Zukunft.
    Suardiaz übernimmt einen mit LNG betriebenen Autotransporter für 5.000 Fahrzeuge.
    Madrid
    Ein zweites PCTC-Schiff wird Mitte 2027 erwartet.
    Hapag-Lloyd hebt seine Prognose für 2026 weiter an
    Hamburg
    Die starke Nachfrage und die steigenden Spotfrachtraten veranlassen das Unternehmen dazu, seine EBITDA- und EBIT-Prognosen deutlich anzuheben.
    Die öffentliche Versammlung der UNIPORT findet am 6. Oktober in Rom statt.
    Rom
    Debatte über die Hafenreform und andere relevante Aspekte des Sektors
    Pilotprojekt zur Produktion und Nutzung von grünem Wasserstoff im Hafen von Savona
    Savona
    Paroli (Westligurische Hafenbehörde): Ein Hafengebiet wurde für Arbeiten identifiziert.
    Tarros und Nurminen Logistics starten neuen skandinavisch-mediterranen intermodalen Service
    La Spezia/Helsinki
    Die Landroute verbindet Örebro, Parma und La Spezia.
    Der erste Senkkasten für den Wellenbrecher zum Schutz der Regasifizierungsanlage vor der Küste von Ravenna wurde gelegt.
    Ravenna
    Die maritimen Bauarbeiten werden etwa 900 Meter lang sein.
    Fincantieri und PT PAL unterzeichnen Abkommen zur Modernisierung eines Schiffes der indonesischen Marine
    Triest
    Dies ist die Einheit "Kri Sriwijaya" (ehemals "Giuseppe Garibaldi")
    In Italien hat die blaue Wirtschaft einen Wert von 225 Milliarden, und allein die nautische Industrie erzielt Exporte von über 10 Milliarden.
    Rom
    SACEs Fokus auf die Bootsmesse in Genua
    Feuer an Bord des Ro-Ro-Schiffes Blue Carrier 2 von Blue Star Ferries
    Kallithea
    Die 29 Personen an Bord wurden evakuiert.
    Die Kosten und der Zeitaufwand für den Wiederaufbau der vier US-Marinewerften steigen exponentiell.
    Washington
    Wenn man im Jahr 2018 mit 21 Milliarden Dollar und 20 Jahren Arbeit rechnete, liegt die Schätzung heute bei 200 Milliarden und mindestens 50 Jahren.
    Die Schifffahrt steht vor einer dreifachen Herausforderung: Dekarbonisierung, Geopolitik und die neue Geografie der Automobilindustrie.
    Spreu
    Auf der Euromed-Konferenz in Grimaldi beschäftigt sich die Branche mit neuen Umweltauflagen, zunehmend exponierten Verkehrswegen und der Verlagerung der Automobilproduktion nach Südostasien.
    Orizzonte Sistemi Navali unterzeichnet einen 3,7 Milliarden Euro schweren Vertrag über zwei Zerstörer
    Triest
    Das PPA-System "Domenico Millelire" wurde an die Marine ausgeliefert.
    Livorno: Der Oberste Kassationsgerichtshof hebt die Verurteilungen im Fall der Darsena-Toscana-Hafen auf.
    Rom
    Das Berufungsurteil hob den Freispruch des Gerichts auf und verurteilte drei Angeklagte wegen ideologischer Urkundenfälschung.
    Der Hafen von Rijeka rechnet damit, das Jahr 2026 mit einem Rekord-Containerumschlag von 800.000 TEU abzuschließen.
    Fluss
    Mit dem neuen Terminal auf der Insel Krk könnte der Güterverkehr auf 1,7 Millionen TEU steigen.
    Finanzierung von Offshore-Windenergie: Pichetto gibt Taranto Zusicherungen, aber Taranto fordert Gewissheit.
    Taranto
    Die Finanzierung des apulischen Hafens sinkt 2026 auf 13,9 Millionen Euro. Gugliotti hofft auf eine formelle Bestätigung der verbleibenden Mittel im Jahr 2027.
    Hafenreform: Die Mehrheit treibt die Reform von Porti d'Italia SpA voran.
    Rom
    Der Verkehrsausschuss der Kammer weist die unterdrückenden Änderungsanträge der Opposition zurück.
    Das Porto Rifugio von Gela hat eine positive Stellungnahme bezüglich der Ausbaggerung der Hafengewässer erhalten.
    Palermo
    HÄFEN
    Italienische Häfen:
    Ancona Genua Ravenna
    Augusta Gioia Tauro Salerno
    Bari La Spezia Savona
    Brindisi Livorno Taranto
    Cagliari Neapel Trapani
    Carrara Palermo Triest
    Civitavecchia Piombino Venedig
    Italienische Logistik-zentren: Liste Häfen der Welt: Landkarte
    DATEN-BANK
    ReedereienWerften
    SpediteureSchiffs-ausrüster
    agenturenGüterkraft-verkehrs-unternehmer
    MEETINGS
    Die vierte Ausgabe der Green Logistics Expo startet morgen früh in Padua.
    Padua
    Es werden über 300 Aussteller teilnehmen und 30 Konferenzveranstaltungen stattfinden.
    Assologistica-Veranstaltung zur Diskussion der Mittelmeerstrategie für die italienische Wettbewerbsfähigkeit
    Rom
    Es findet am 30. Oktober nächsten Jahres in Neapel statt.
    ››› Archiv
    NACHRICHTENÜBERBLICK INHALTSVERZEICHNIS
    Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
    (South China Morning Post)
    Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
    (Interfax)
    ››› Nachrichtenüberblick Archiv
    FORUM über Shipping
    und Logistik
    Intervento del presidente Tomaso Cognolato
    Roma, 19 giugno 2025
    ››› Archiv
    Greenbrier Europe wird das NIK-Umschlagsystem für TX Logistik produzieren.
    Troisdorf/Berlin
    Ermöglicht das schnelle Verladen von nicht kranfähigen Sattelaufliegern auf Züge
    Maersk eröffnet eigenes Logistikzentrum im Herzen Deutschlands
    Herleshausen
    Es befindet sich in Herleshausen und hat eine Fläche von 71.800 Quadratmetern.
    Südkoreas HJ Shipbuilding & Construction Co. erhält Aufträge für vier neue Containerschiffe mit einer Kapazität von 10.100 TEU
    Busan
    Der Vertrag hat einen Gesamtwert von rund 500 Millionen Dollar.
    Demokratische Partei: Die Hafenreform der Regierung ebnet den Weg für die Privatisierung italienischer Häfen.
    Rom
    Ghio und Misiani: Es entzieht den Gebieten auch Ressourcen und Fähigkeiten.
    Eigenproduktion im Hafen: Der Staatsrat verneint die Aufteilung der Genehmigung gemäß Artikel 16 Absatz 3.
    Rom
    Die "teilweise" Genehmigung von Cartour im Hafen von Salerno wurde ausgesetzt.
    Der Hafen von Miami schließt das Geschäftsjahr 2026 mit einem Rekord-Kreuzfahrtverkehr ab
    Miami
    Die Schwelle von zehn Millionen Passagieren wurde überschritten, im Vergleich zu 8,56 Millionen im vorangegangenen Geschäftsjahr.
    Die Grimaldi-Gruppe hat den neuen reinen Auto- und Lkw-Transporter Grande Egitto in Empfang genommen.
    Neapel
    Seine Ladekapazität erreicht 9.800 CEU.
    Die Hafenreform wird am 2. Oktober in Genua diskutiert.
    Genua
    Workshop organisiert von AdSP und dem Verein Altero Matteoli
    Fratelli Cosulich stärkt sein Logistiknetzwerk mit der Eröffnung von Express Global Dubai
    Dubai
    Teresa Cosulich wird für das neue Logistikbüro verantwortlich sein.
    "Ein Meer aus der Schweiz" findet am 9. Oktober in Lugano statt.
    Lugano
    Neunte Ausgabe des Internationalen Forums für Verkehr und Infrastruktur
    Neuer Angriff auf ein Schiff in der Straße von Hormuz
    Southampton
    Zwei Besatzungsmitglieder wurden durch eine Kugel leicht verletzt.
    Die Brullo-Gruppe bestellt drei Öl-/Chemikalientanker mit je 40.800 Tonnen Tragfähigkeit.
    Rom
    Auftrag an die chinesische Werft Anhui Shipyard
    In Triest wird ein neues Zentrum für die Produktion, Wartung und Lagerung von Megayachten eröffnet.
    Triest
    Trieste Shipyards wurde von Seadock (Samer-Gruppe) und Yachting Expertise gegründet und befindet sich im Besitz von Friulia.
    Confitarma begrüßt die Initiative der Regierung zum Schutz italienischer Schiffe im Roten Meer.
    Rom
    Zanetti: Maritime Sicherheit ist faktisch ein Bestandteil der nationalen wirtschaftlichen Sicherheit.
    Die Gewerkschaften stimmen der Plattform für den einheitlichen Tarifvertrag für die Schifffahrtsbranche zu.
    Rom
    Filt, Fit and Uilt ist um drei zentrale Elemente herum strukturiert: Gehalt, Schutz, Beteiligung und dreizehn konkrete Forderungen.
    FHP Intermodal erhöht die Frequenz seines Güterzugverkehrs zwischen Fiorenzuola und Incoronata/Bari.
    Mailand
    Es geht bis zu fünf Tage die Woche.
    In diesem Jahr waren über 2000 große Yachten entlang der italienischen Küsten unterwegs.
    Rom
    Plus 10 % für eigene Boote und ein im Wesentlichen stabiler Trend für gecharterte Boote
    Die Veranstaltung "Cyberresilienz im maritimen Sektor: Verteidigung, Regulierung und europäische Zusammenarbeit" findet am Dienstag in Rom statt.
    Rom
    Es wird von der Var Group und Confitarma organisiert.
    Mit der Übernahme von HTG erweitert Smeup sein Portfolio im Logistik- und Transportsektor.
    Erbusco
    Das in Turin ansässige Unternehmen ist auf die Entwicklung proprietärer Software spezialisiert.
    Saudi-arabische Häfen: Flüssiggutumschlag wird 2025 stark zurückgehen
    Riad
    Der Gesamtverkehr sank auf 298,3 Millionen Tonnen (-10,9 %).
    - Via Raffaele Paolucci 17r/19r - 16129 Genua - ITALIEN
    tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
    Umsatzsteuernummer: 03532950106
    Registrazione Stampa 33/96 Tribunale di Genova
    Verantwortlicher Direktor: Bruno Bellio
    Jede Reproduktion, ohne die ausdrückliche Erlaubnis des Herausgebers, ist verboten
    Suche in inforMARE Einführung
    Feed RSS Werbeflächen

    inforMARE in Pdf
    Handy