- Valuation of the
Liner Shipping
Industry-
- Economic Contribution and Liner
Industry Operations
-
- December 2009
-
- Table of Contents
-
|
Figures |
|
Figure 1: |
Average Weekly Port Calls Made by
Container and Vehicle Vessels, First 35 Weeks of 2009 |
|
Figure 2: |
Average Weekly Nautical-Miles
Travelled by Container and Vehicle Vessels, First 35 Weeks of 2009
|
|
|
|
|
Tables |
|
Table 1: |
Direct Economic Contribution of
Shipbuilding and Liner Industry Operations, 2007 |
|
Table 2: |
Direct Economic Contribution of Liner
Industry Operations, 2007 |
|
Table 3: |
Direct Economic Contribution of
Shipbuilding, 2007 |
|
Table 4: |
Global Liner Fleet, July 2009 |
|
Table 5: |
Global Liner Fleet on Order
|
|
Table 6: |
Current and On-Order Liner Fleet by
Region, July 2009 |
|
Table 7: |
European Union Liner Fleet, July 2009 |
|
Table 8: |
Top Twenty Countries by Existing Fleet
and Vessels On-Order, July 2009 |
|
Table 9: |
Deliveries of Container and Ro-Ro
Vessels by Builder Country, 2006-2008 |
|
Table 10: |
Cumulative Spending on Liner Vessels
by Operating Region through 2009
|
|
Table 11: |
Cumulative Receipts from Sales of
Liner Vessels by Region of Build as of July, 2009 |
|
Table 12: |
Number of Service and Annual Capacity
Deployed by Route, as of July 1, 2007 |
|
Table 13: |
Average Weekly Number of Port Calls
Made by Operator Region in 2009 |
|
Table 14: |
Average Weekly Number of
Nautical-Miles Travelled by Operator Region in 2009 |
|
Table 15: |
Top 20 World Ports by 2008 Throughput |
|
Table 16: |
Throughput at Select Container Ports
in the European Union, 2007- 2008
|
|
Table 17: |
Throughput at Select Container Ports
in North America, 2007
|
|
Table 18: |
Investment by Terminal Operators,
2007-2008
|
|
Table 19: |
Container Fleet by Region, Mid-2008
|
|
Table 20: |
Container Handling and Trans-shipment,
Million TEUs, 2007 |
|
Table 21: |
Chassis Fleet and Operating Costs in
the United States, 2008
|
- Executive Summary
-
- Liner shipping is the service of transporting goods by means of
high capacity, oceangoing ships that transit regular routes on fixed
schedules. The liner shipping industry is the primary conduit of
world trade and an increasingly important part of the maritime
industry. Liner shipping carries the majority of the world's
ocean-borne trade in value terms and facilitates a significant
portion of the merchandise trade of the world. The industry has
contributed to advances in the standard of living of most of the
world's population in the last 35 years, as the gains from trade
through advancing global commerce were enabled by the reliable,
efficient and relatively low-cost transportation provided by the
industry.
-
- Quantifying the significance of the liner shipping industry can
be done using many metrics. Valuable perspectives on the liner
industry include how much of world trade is handled by the liner
industry; the employment, investment, and value added the industry
contributes to the world economy, and the operational
characteristics of the industry in providing services globally.
-
- WHAT IS THE LINER SHIPPING INDUSTRY?
-
- The liner shipping industry is the portion of the maritime
industry that includes all operations and related infrastructure
involved in scheduled ocean-borne shipping. It consists of liner
vessels and the people working on-board these vessels, ports,
shipbuilding operations, longshore dock workers, shipbuilders, and
all other on-shore support staff. Liner shippers transport most of
the high unit-value consumer and intermediate goods, including ocean
containerized cargo, vehicles, and other mobile machinery. The
industry operates on all oceans and many of the navigable inland
waterways world-wide, benefitting consumers and exporters globally.
-
- KEY FINDINGS
-
- This report provides measures that describe the important role
of the liner shipping industry in the world and for key world
regions. Among the findings are:
-
The value of the liner industry operations and shipbuilding in 2007
is estimated to be $436.3 billion, generating 13.5 million direct
and related jobs.
-
The liner industry transported about 60% of the total value of
global seaborne trade of US$7.7 trillion in 2007.
-
The industry has invested in more than 7,000 vessels to provide
these services, with approximately another 1,400 on order.
-
Over $235 billion have been spent on new vessels by the industry.
-
Throughput at the top 20 global ports reached almost 250 million TEU
in 2008.
-
In 2008, the global container fleet consisted of 17.8 million
containers, which cost the industry over $80 billion.
-
In 2009, on average, liner ships made 10,000 port calls around the
world each week.
-
In mid-2007, the liner industry operated more than 400 scheduled
services serving intercontinentalroute.
- Introduction
-
- The liner industry is a crucial segment of the global economy
and contributes significantly to world economic output. The industry
is broadly defined as the operations and underlying infrastructure
involved in scheduled ocean-borne shipping. As such, it consists of
a variety of components with significant economic impact, including:
-
Liner operating companies
-
Liner vessels
-
Ports of Call
-
Shipbuilding operations
-
Liner industry operations
|
1 |
IHS Lloyd's Register-Fairplay fleet
database and IHS Global Insight World Trade Service. |
|
|
- Liner operating companies generally transport high-value
consumer and intermediate goods, including all seaborne
containerized cargo, automobiles, and other machinery. As a result,
the industry has a profound effect on consumers and exporters. In
2007, the industry carried almost 60% of the total value of the
world's seaborne commodities on more than 7,000 registered vessels.1
-
- The industry is especially significant to the economies of the
European Union and South Korea in terms of shipbuilding and to the
European Union, China, United States, and the Americas in its
economic contribution from transport operations. Globally, the
industry was directly or indirectly responsible for over $436.3
billion in output and 13.5 millions jobs in 2007.
-
- PURPOSE OF REPORT
-
- This report was commissioned by the World Shipping Council in
order to better understand the value and size of the liner shipping
industry and its contribution to global trade and national
economies. The estimates presented in this report are an initial
effort using readily available data from various IHS companies for
valuing and sizing the industry. The majority of the data presented
here is from 2007, the most recent year for which economic and trade
data is complete. This year also presents the size and impact of the
industry prior to the current global recession and is thus
indicative of future operations.
-
- METHODOLOGY AND DATA SOURCES
-
- The primary information presented in this report is derived from
three IHS data sources, described in greater detail in the body of
this report:
-
- IHS Global Insight World Trade Service (WTS): used
to estimate the trade impact of the liner industry.
- IHS Global Insight World Industry Service (WIS):
used to estimate the economic and employment impact of the liner
industry. A detailed explanation of the WIS methodology is available
in Appendix B.
- IHS Lloyd's Register - Fairplay Research (LRF):
used for determining the size of the global liner fleet, its
capacity and operating statistics. LRF maintains a comprehensive
ongoing registry of all seagoing vessels of 100 gross tons or larger
and tracks their operations on an ongoing basis.
- Where enough geographic detail was available, economic, trade
and operating metrics were aggregated by region. The WTS regional
trade aggregations are presented in Appendix A.
-
- These three databases were supplemented with data obtained from
research of websites and annual reports of liner industry
participants including liner vessel operators and service providers,
ports and port authorities, terminal operators, and equipment
manufacturers. Consulting and other research reports were also
reviewed. For a full list of reviewed sources please see Appendix C.
-
- Economic Valuation of the Liner
Industry
-
- The most common measures of the value of an industry in the
economy are the value of output produced by the sector and the
associated employment provided by this activity. These are commonly
measured through the value of the output of the companies in the
industry and the number of workers they employ. This section reviews
available economic metrics for the liner industry and provides
estimates of the economic value of the liner industry and its
contribution to the global economy and regional economies.
-
- An ideal measure of this value would include the value of liner
vessels, their operations, and the value of on-shore assets that
support the industry. In practice, however, because some on-shore
assets and personnel are shared in their use with non-liner
transportation services, such measures are very difficult to produce
and would require a significant effort in summing up values using a
"bottom-up" approach. This process faces limitations in
the inconsistencies between national financial accounting standards
and gaps in the data collected and published by different government
agencies and facilities such as liner ports around the world.
-
- The analysis of the industry included here have been produced
using "top-down" economic measures of the liner industry
derived from IHS Global Insight's World Industry Service databases.
The detailed methodology and data sources used to derive the liner
share portion of these measures are presented in Appendix A. The key
indicators presented here are Capital Expenditures, Gross Output,
Labor Compensation, and Number of Employees for both the liner
industry and the portion of the shipbuilding industry devoted to
building and maintaining liner vessels.
-
- The liner industry produced over $183 billion of direct output
globally in 2007 from both operations and shipbuilding. Of this,
more than a third was produced by companies in the European Union.
The liner industry also accounts for more than 4 million direct jobs
world-wide and investment in fixed assets of more than $29 billion.
This estimate of the value of the industry does not include related
activities such as cargo handling and storage activities at ports,
nor does it include the inland transportation of liner cargoes,
unless moved inland by water.
-
- In addition to the direct impacts of the liner industry measured
in value and jobs, the spending by the industry creates additional
indirect economic impact on other sectors of the economy.
Furthermore, this spending induces additional economic activity and
employment in the economy. Using estimates of the multipliers for
indirect and induced effects that apply to the maritime sector for
value and related employment, the full impact of the value of the
liner sector operations and shipbuilding in 2007 is estimated to be
$436.3 billion in gross output, generating 13.5 million jobs.
- Table 1: Direct Economic Contribution of Shipbuilding and
Liner Industry Operations, 2007
-
(Million US Dollars)
-
|
Region |
- Gross
-
Output
|
Labor
Compensation |
Employees
(Thousand) |
Capital
Expenditure |
|
Total |
183,305.0 |
27,177.9 |
4,146.8 |
29,406.0 |
Sources: IHS Global Insight World
Industry Service and World Trade Service.
- The direct global economic contribution generated from the
operations of the liner industry produced over $141 billion, or
about 77 percent, of liner industry related direct output in 2007.
With almost 4 million people directly employed world-wide and with
investment in fixed assets of almost $28 billion, liner industry
operations also account for most of the jobs and capital investment
related to the industry.
-
- Table 2: Direct Economic Contribution of Liner Industry
Operations, 2007
-
(Million US Dollars)
-
|
Region |
Gross
Output |
Labor
Compensation |
Employees
(Thousand) |
Capital
Expenditure |
|
Total |
141,528.3 |
20,792.2 |
3,869.9 |
27,527.8 |
Sources: IHS Global Insight World Industry
Service and World Trade Service.
- In addition to the extensive global operations of the liner
industry, the value and employment of the manufacturing required to
supply the equipment for liner industry operations is also
significant, especially for countries with advanced and sizable
shipbuilding operations. The direct economic contribution of liner
vessel manufacturing for countries that delivered at least one liner
vessel in 2007 is shown in Table 3.
-
The construction of liner vessels provided almost 277,000 jobs in
shipbuilding countries and generated almost $42 billion of gross
output, more than $6 billion of which was labor compensation. The
liner shipbuilding industry also invested almost $1.9 billion in
fixed assets during the year 2007. The leader in liner vessel
construction is South Korea, with almost $16 billion worth of
output, followed by Germany.
-
Likewise, Japan has a large shipbuilding industry, although much of
its output is of non-liner shipping vessels such as bulk carriers.
-
- Table 3: Direct Economic Contribution of Shipbuilding for the
Liner Industry, 2007
-
(Million US Dollars)
-
|
Country |
Gross
Output |
Labor
Compensation |
Employees
(Thousand) |
Capital
Expenditures |
|
China |
4,726.2 |
97.5 |
88.4 |
279.3 |
|
Germany |
8,694.8 |
1,531.4 |
24.5 |
166.8 |
|
Japan |
4,089.4 |
573.1 |
13.7 |
95.6 |
|
South Korea |
15,857.3 |
2,400.7 |
77.9 |
958.1 |
|
United States |
52.4 |
17.9 |
0.3 |
2.2 |
|
Rest of World |
8,356.7 |
1,765.1 |
72.0 |
376.2 |
|
European Union Total |
13,804.7 |
2,665.5 |
48.4 |
419.2 |
|
World Total |
41,776.7 |
6,385.8 |
276.9 |
1,878.2 |
Sources: IHS Global Insight World
Industry Service and Lloyd's Register-Fairplay Research.
- Liner Industry Operations and
Expenditures
-
- This section of the report examines the seaborne operations of
the liner industry as well as its on-shore component, including port
expenditures, where possible. The size and impact of the liner
industry can be quantified by examining its expenditure on capital
such as vessels, containers and equipment as well as the cost of its
operations. In addition, non-monetary measures of the industry’s
operations also provide useful information on the industries
magnitude and scope. Where data was available, this report
quantifies the dollars spent on capital and operations by the
industry as well as the following operational statistics: port
calls, port throughput, number of services provided, available liner
capacity, and nautical-miles traveled. The size and geographic scope
of the liner fleet is examined in greater detail. Lastly, the number
of containers and other equipment utilized by the liner industry is
quantified where possible.
-
- In mid-2007, the global liner fleet consisted of 7,210 vessels
with approximately 185 million deadweight tons (dwt) of capacity,
including 12.5 million TEU of container capacity and 3.2 million CEU
of automotive capacity. As of July 2009, approximately $236 billion
has been spent cumulatively on purchasing new liner vessels since
the inception of the liner trade. This amount does not include the
additional and potentially substantial amounts spent subsequently in
the second-hand market, or for upgrades and maintenance. The liner
fleet made more than 10,000 average weekly port calls in the first
half of 2009 and the average liner ship travelled more than 1,100
nautical-miles in an average week.
-
|
2 |
U.S. DOT Maritime Administration, U.S.
Public Port Development Expenditure Report (FYs 2006 &
2007-2011), February 2009. Major ports such as Los
Angeles/Long Beach and New York/New Jersey were not respondents to
this survey. The true investment by U.S. ports in liner facilities
is thus very likely to be significantly larger than $360 million. |
|
|
- Throughput at the top twenty busiest global ports reached almost
250 million TEU in 2008. The global container fleet reached 17.8
million units and cost $80.1 billion. Investment in liner ports by
port authorities and terminal operators are also substantial. Ports
in the United States alone invested at least $360 million2
in their liner facilities in just 2006.
-
- METHODOLOGY AND DATA SOURCES
-
- Fleet statistics are derived from databases compiled and
maintained by Lloyd's Register - Fairplay Research (LRF). LRF
maintains registry information for all ships with International
Maritime Organization (IMO) numbers, which includes all seagoing
trading ships of 100 gross tonnes and above as well as vessels that
are on order. The nationalities of the operator as well as the owner
are recorded for most - though not all - vessels in this database.
The fleet and order book databases are primary data sources and do
not pose any major limitations.
-
- The expenditures and operations of the liner industry are not
possible to fully quantify on a global scale for a variety of
reasons. Many liner companies, equipment manufacturers, and terminal
operators are privately held companies which disclose only minimal
details pertaining to their finances and operations. Accounting
requirements differ across countries for publicly held companies.
There are thus no global or regional organizations that have
aggregated any comprehensive financial or operating data on the
liner industry. Instead, only piecemeal information can be gleamed
from company reports and government agencies.
-
- Subject to such limitations, this report presents the best
available data and examples as could be gathered from a review of
company information as available from their websites, annual
reports, government organizations and research and consulting
companies. The sources and methodologies for the operating and
financial measures and data that were quantified here are described
in greater detail in each of the following sections.
-
- THE LINER FLEET
-
- For the purposes of this report, the liner fleet is defined as
consisting of container, vehicle, and Ro-Ro vessels. Some of the
Ro-Ro vessels identified in the database are used in short-sea, as
opposed to liner, shipping. While it is difficult to identify and
exclude Ro-Ro vessels utilized in short-sea shipping, their share of
the overall Ro-Ro vessel count is small. In addition, certain
vessels such as combination vessels that operate on a scheduled
service but are not container, vehicle or Ro-Ro vessels are excluded
from the vessel counts and capacity data.
-
- It is important to note that the exact number of ships in the
liner fleet changes frequently as ships are decommissioned or new
ships enter service. Likewise, the order book is frequently updated
with new orders and changes to current orders.
-
- Fleet Size and Capacity
-
- As of July 2009, the global liner fleet consisted of 7,210
vessels with almost 185 million dead-weight tons of capacity. The
container fleet of 4,684 vessels has capacity of just over 12.5
million TEU, and the vehicle fleet of 773 vessels has the capacity
of approximately 3.2 million car equivalent units (CEU). The Ro-Ro
fleet provides an additional 1.2 million CEU of capacity.
-
- Table 4: Global Liner Fleet, July 2009
-
|
Vessel Type |
Number
of Vessels |
Dwt |
|
Container |
4,684 |
165,774,103 |
|
Vehicle |
773 |
11,375,69 |
|
Ro-Ro |
1,753 |
7,423,240 |
|
Total |
7,210 |
184,573,034 |
Source: Lloyd's Register - Fairplay
Research
- The total order book for liner vessels in July 2009 contained
another 1,381 vessel to be added to the fleet. These vessels will
account for another 68.1 million dwt in liner tonnage. Container
ships on-order will add 5.5 million TEU of capacity or roughly 40%
additional capacity. The order book thus reflects the growing size
of container vessels. The average container ship in the current
fleet has the capacity of about 2,670 TEU where as the average
container ship on-order will have the capacity of more than 5,000
TEU. A similar trend can be observed in vehicle vessels. The vehicle
carrier vessels on-order will provide another 1.14 million CEU of
capacity, or an average capacity of 5,300 CEU per vessel compared to
an average capacity of 4,100 CEU per vessel in the current fleet.
-
- Table 5: Global Liner Fleet on Order
-
|
Vessel Type |
Number
of Vessels |
Dwt |
|
Container |
1,082 |
63,755,615 |
|
Vehicle |
214 |
3,539,701 |
|
Ro-Ro |
85 |
814,676 |
|
Total |
1,381 |
68,109,992 |
Source: Lloyd's Register - Fairplay
Research
- Over the last five years, container shipping has been one of the
fastest growing segments of seaborne shipping. The fleet has grown
by an average annual of 13% over the last five years. This growth is
driven primarily by vessels with a capacity of over 5,000 TEU, which
added 3.1 million TEU of capacity between 2004 and 2008. In the next
five years, the container fleet is expected to expand an average of
9.3% per year, with growth in vessels of more than 8,000 TEU topping
25% through 2013.
-
- The growth in the vehicle carrier fleet has also been
significant, averaging 9.3% per year between 2004 and 2008. This
growth will slow to about five percent per year over the next five
years.
-
- Table 6 below presents the regional break-down of the current
liner fleet as well as the liner fleet that is currently on-order.
Regional fleet data are aggregated based on the nationality of the
operator of each vessel and not the registry of the vessel as the
operator is more in control of the operational deployment of vessels
and therefore has a more important impact on the countries the
vessels are used to serve than the owner of the vessel in cases
where the owner and operator are different.
-
|
3 |
Greater China is a regional definition
used in this report to represent all of China, including Taiwan,
China and Hong Kong S.A.R. |
|
|
- The regional break-down of the liner fleet demonstrates that
with a total fleet of 2,112 vessels, or 29 percent of the global
fleet, and an additional 654 vessels on order, the European Union
dominates liner trade by this measure, especially for container
vessels. Asia, particularly Greater China3 and Japan,
also has a significant and expanding presence in container shipping.
Japan, however, is the leading country in seaborne vehicle shipping,
with almost 48 percent of the total global vehicle carrier fleet.
-
- Table 6: Current and On-Order Liner Fleet by Region, July
2009
-
|
Vessel Type |
Operator Region |
Existing Fleet |
On-Order |
|
|
|
Vessels |
Dwt |
TEU/CEU |
Vessels |
Dwt |
TEU/CEU |
|
Container |
European Union |
1,641 |
58,749,877 |
4,414,581 |
546 |
27,074,606 |
2,277,276 |
|
Other Europe |
508 |
21,191,551 |
1,568,753 |
68 |
7,335,173 |
648,447 |
|
Greater China |
857 |
32,271,290 |
2,498,311 |
131 |
9,843,666 |
866,764 |
|
Japan |
326 |
14,451,324 |
1,110,661 |
84 |
4,981,250 |
451,196 |
|
South Korea |
245 |
9,881,359 |
762,819 |
39 |
3,483,674 |
316,568 |
|
Other Asia |
529 |
13,084,849 |
961,141 |
45 |
2,060,360 |
184,538 |
|
United States |
89 |
1,977,114 |
145,363 |
1 |
63,300 |
4,860 |
|
Canada |
2 |
16,657 |
1,342 |
0 |
0 |
0 |
|
Latin America & Caribbean |
146 |
5,151,926 |
388,334 |
20 |
1,462,096 |
132,724 |
|
Middle East & Africa |
229 |
7,851,031 |
576,010 |
63 |
5,216,203 |
449,032 |
|
Unknown |
112 |
1,147,125 |
83,505 |
85 |
2,235,287 |
174,715 |
|
Total Container |
4,684 |
165,774,103 |
12,510,820 |
1,082 |
63,755,615 |
5,506,120 |
|
Vehicle |
European Union |
119 |
2,461,381 |
571,640 |
78 |
1,404,885 |
420,201 |
|
Other Europe |
164 |
2,653,173 |
764,238 |
29 |
399,520 |
153,827 |
|
Greater China |
49 |
484,134 |
143,341 |
33 |
537,726 |
162,924 |
|
Japan |
368 |
5,063,649 |
1,497,799 |
34 |
481,450 |
165,678 |
|
South Korea |
16 |
168,908 |
31,567 |
5 |
61,420 |
31,670 |
|
Other Asia |
10 |
52,466 |
10,531 |
1 |
17,250 |
5,309 |
|
United States |
10 |
183,887 |
49,788 |
2 |
42,400 |
12,000 |
|
Canada |
0 |
0 |
0 |
0 |
0 |
0 |
|
Latin America & Caribbean |
3 |
43,475 |
14,006 |
0 |
0 |
0 |
|
Middle East & Africa |
12 |
100,242 |
29,298 |
0 |
0 |
0 |
|
Unknown |
22 |
164,376 |
56,348 |
32 |
595,050 |
183,738 |
|
Total Vehicle |
773 |
11,375,691 |
3,168,556 |
214 |
3,539,701 |
1,135,347 |
|
Ro-Ro |
European Union |
352 |
3,429,781 |
595,003 |
30 |
450,528 |
98,274 |
|
Other Europe |
107 |
640,984 |
126,979 |
12 |
89,444 |
22,090 |
|
Greater China |
25 |
165,381 |
25,214 |
6 |
68,144 |
22,626 |
|
Japan |
94 |
610,843 |
90,298 |
0 |
0 |
0 |
|
South Korea |
11 |
74,909 |
10,227 |
0 |
0 |
0 |
|
Other Asia |
230 |
288,091 |
36,300 |
10 |
29,797 |
8,066 |
|
United States |
80 |
846,057 |
152,911 |
0 |
0 |
0 |
|
Canada |
8 |
62,693 |
9,226 |
0 |
0 |
0 |
|
Latin America & Caribbean |
33 |
104,264 |
20,106 |
5 |
26,325 |
10,780 |
|
Middle East & Africa |
169 |
499,640 |
75,966 |
3 |
13,270 |
2,159 |
|
Unknown |
644 |
700,597 |
93,452 |
19 |
137,168 |
13,004 |
|
Total Ro-Ro |
1,753 |
7,423,240 |
1,235,682 |
85 |
814,676 |
176,999 |
|
Total Liner |
European Union |
2,112 |
64,641,039 |
|
654 |
28,930,019 |
|
|
Other Europe |
779 |
24,485,708 |
|
109 |
7,824,137 |
|
|
Greater China |
931 |
32,920,805 |
|
170 |
10,449,536 |
|
|
Japan |
788 |
20,125,816 |
|
118 |
5,462,700 |
|
|
South Korea |
272 |
10,125,176 |
|
44 |
3,545,094 |
|
|
Other Asia |
769 |
13,425,406 |
|
56 |
2,107,407 |
|
|
United States |
179 |
3,007,058 |
|
3 |
105,700 |
|
|
Canada |
10 |
79,350 |
|
0 |
0 |
|
|
Latin America & Caribbean |
182 |
5,299,665 |
|
25 |
1,488,421 |
|
|
Middle East & Africa |
410 |
8,450,913 |
|
66 |
5,229,473 |
|
|
Unknown |
778 |
2,012,098 |
|
136 |
2,967,505 |
|
|
Total Liner |
7,210 |
184,573,034 |
|
1,381 |
68,109,992 |
|
Note: Unknown refers to liner vessels
the nationality of whose operator is not recorded in the
registry.
Source: Lloyd's Register - Fairplay Research
- Table 7 provides an overview of the current fleet size for
countries in the European Union - the largest regional participant
in the liner industry. With almost 600 liner vessels each, Denmark
and Germany are the leading participants in the European Union liner
industry and account for 55 percent of the Union's liner fleet.
France operates more than 300 liner vessels; where as all other
member states operate less than 100 vessels. Sweden is the major
operator of vehicle vessels, accounting for more than 55 percent of
the total European Union vehicle fleet. However, the European Union
operates much fewer vehicle vessels than Japan does alone. Ro-Ro
operations are spread fairly evenly through out the European Union.
-
- Table 7: European Union Liner Fleet, July 2009
-
|
Operator Country |
Container |
Vehicle |
Ro-Ro |
Total |
|
|
Vessels |
Dwt |
TEU |
Vessels |
Dwt |
CEU |
Vessels |
Dwt |
CEU |
Vessels |
Dwt |
|
Austria |
1 |
12,167 |
754 |
|
|
|
|
|
|
1 |
12,167 |
|
Belgium |
44 |
431,422 |
34,921 |
|
|
|
28 |
245,588 |
56,775 |
72 |
677,010 |
|
Bulgaria |
3 |
42,713 |
2,280 |
|
|
|
2 |
20,871 |
2,178 |
5 |
63,584 |
|
Cyprus |
37 |
738,066 |
53,088 |
|
|
|
2 |
17,684 |
2,975 |
39 |
755,750 |
|
Denmark |
529 |
25,873,255 |
1,902,981 |
1 |
15,880 |
6,545 |
39 |
375,452 |
86,856 |
569 |
26,264,587 |
|
Estonia |
3 |
14,954 |
1,262 |
|
|
|
3 |
6,565 |
925 |
6 |
21,519 |
|
Finland |
11 |
112,803 |
8,748 |
|
|
|
30 |
231,100 |
47,487 |
41 |
343,903 |
|
France |
296 |
12,011,547 |
938,591 |
|
|
|
17 |
213,155 |
33,732 |
313 |
12,224,702 |
|
Germany |
553 |
17,177,137 |
1,302,190 |
|
|
|
30 |
251,013 |
23,383 |
583 |
17,428,150 |
|
Greece |
30 |
605,565 |
42,526 |
15 |
123,524 |
38,818 |
38 |
203,600 |
38,212 |
83 |
932,689 |
|
Irish Republic |
9 |
52,801 |
4,491 |
1 |
1,275 |
568 |
2 |
13,511 |
2,925 |
12 |
67,587 |
|
Italy |
18 |
359,898 |
23,385 |
28 |
587,341 |
109,594 |
41 |
749,663 |
90,630 |
87 |
1,696,902 |
|
Latvia |
|
|
|
|
|
|
2 |
6,332 |
1,449 |
2 |
6,332 |
|
Lithuania |
1 |
13,729 |
1,080 |
|
|
|
|
|
|
1 |
13,729 |
|
Netherlands |
43 |
628,658 |
48,784 |
2 |
36,074 |
10,378 |
37 |
418,600 |
77,118 |
82 |
1,083,332 |
|
Poland |
1 |
9,238 |
750 |
|
|
|
6 |
44,766 |
8,127 |
7 |
54,004 |
|
Portugal |
3 |
31,246 |
2,123 |
|
|
|
1 |
3,570 |
870 |
4 |
34,816 |
|
Romania |
4 |
21,740 |
1,133 |
|
|
|
2 |
8,065 |
1,776 |
6 |
29,805 |
|
Spain |
17 |
236,242 |
15,076 |
6 |
21,773 |
7,005 |
14 |
80,121 |
19,750 |
37 |
338,136 |
|
Sweden |
2 |
19,071 |
1,618 |
66 |
1,675,514 |
398,732 |
28 |
345,762 |
59,052 |
96 |
2,040,347 |
|
United Kingdom |
36 |
357,625 |
28,800 |
|
|
|
30 |
194,363 |
40,783 |
66 |
551,988 |
|
Total |
1,641 |
58,749,877 |
4,414,581 |
119 |
2,461,381 |
571,640 |
352 |
3,429,781 |
595,003 |
2,112 |
64,641,039 |
Source: Lloyd's Register - Fairplay
Research
- Table 8 ranks the top twenty countries by the size of their
current liner fleet and by the number of vessels they have on order.
China is currently the leading operator of liner vessels with 11
percent of the global liner fleet and 15 percent of its capacity. It
is followed closely by Japan, with 788 liner vessels. Denmark, which
ranks fifth by the fleet count, operates the second largest fleet by
capacity. Germany is the largest European Union operator of liner
vessels and the country with the most vessels on-order world-wide.
By the current order-book, Germany will operate only two fewer
vessels than China by the time the orders are completed.
-
- Table 8: Top Twenty Countries by Existing Fleet and Vessels
On-Order, July 2009
-
|
|
Existing Fleet |
On-Order |
|
Rank |
Operator Country |
Vessels |
Dwt |
Operator Country |
Vessels |
Dwt |
|
1 |
China |
804 |
27,906,667 |
Germany |
355 |
14,103,350 |
|
2 |
Japan |
788 |
20,125,816 |
Unknown* |
136 |
2,967,505 |
|
3 |
Unknown* |
778 |
2,012,098 |
China |
126 |
8,626,542 |
|
4 |
Germany |
583 |
17,428,150 |
Japan |
118 |
5,462,700 |
|
5 |
Denmark |
569 |
26,264,587 |
Denmark |
63 |
4,609,064 |
|
6 |
Switzerland |
387 |
19,617,726 |
France |
59 |
5,338,548 |
|
7 |
France |
313 |
12,224,702 |
Greece |
56 |
2,252,062 |
|
8 |
Singapore |
291 |
9,409,744 |
Switzerland |
46 |
6,780,960 |
|
9 |
South Korea |
272 |
10,125,176 |
Hong Kong S.A.R., China |
44 |
1,822,994 |
|
10 |
Indonesia |
196 |
999,769 |
South Korea |
44 |
3,545,094 |
|
11 |
Norway |
186 |
2,783,435 |
Netherlands |
37 |
564,490 |
|
12 |
United States |
179 |
3,007,058 |
Norway |
37 |
442,420 |
|
13 |
Hong Kong S.A.R., China |
127 |
5,014,138 |
Singapore |
37 |
1,887,087 |
|
14 |
Chile |
119 |
4,515,680 |
Israel |
30 |
2,873,349 |
|
15 |
United Arab Emirates |
106 |
1,001,431 |
Cyprus |
27 |
720,900 |
|
16 |
Israel |
104 |
3,739,350 |
Turkey |
22 |
452,144 |
|
17 |
Sweden |
96 |
2,040,347 |
Belgium |
18 |
550,771 |
|
18 |
Turkey |
94 |
1,088,073 |
Italy |
18 |
334,497 |
|
19 |
Malaysia |
89 |
1,088,152 |
Kuwait |
17 |
1,781,100 |
|
20 |
Italy |
87 |
1,696,902 |
Sweden |
12 |
289,120 |
|
|
Other |
1,042 |
12,484,033 |
Other |
79 |
2,705,295 |
|
|
Total |
7,210 |
184,573,034 |
|
1,381 |
68,109,992 |
Source: Lloyd's Register - Fairplay
Research
- * Note: The identity of an operator is
unknown because the vessel is on the order book without an assigned
operator or the vessel is not currently in service. In addition,
operator data is incomplete on operators with small fleets of one or
two ships and on some operators from select developing countries.
-
- Shipbuilding
-
- Many maritime nations participate in liner vessel operations,
with larger nations tending to operate larger fleets. Shipbuilding,
however, is more concentrated among a few countries - particularly
South Korea and Japan - with highly developed shipyards.
Shipbuilding is an important component of the liner industry, and it
generates many skilled jobs and revenues.
-
- A total of 532 container and Ro-Ro vessels were delivered in
2007. In Table 9 below are the details. South Korea delivered
approximately 48 percent of new liner capacity in 2007 and Japan
delivered another 18 percent. The table also demonstrates that South
Korea's dominance in shipbuilding has slowly eroded over the last
three years, as its market share declined from 54 percent to 43
percent between 2006 and 2008. The main beneficiary has been China,
whose market share increased from less than 10 to more than 20
percent in the same time period. Indonesia and Malaysia deliver
dozens of smaller vessels, with less than one thousand gross-tons of
capacity.
-
- Table 9: Deliveries of Container and Ro-Ro Vessels by Builder
Country, 2006-2008
-
|
|
2006 |
2007 |
2008 |
|
Builder Country |
No. |
1,000gt |
% |
No. |
1,000gt |
% |
No. |
1,000gt |
% |
|
South Korea |
149 |
9,378 |
54.3% |
151 |
8,314 |
47.5% |
148 |
8,794 |
43.4% |
|
Japan |
63 |
2,776 |
16.1% |
72 |
3,179 |
18.2% |
86 |
4,137 |
20.4% |
|
China |
95 |
1,690 |
9.8% |
124 |
2,262 |
12.9% |
164 |
3,676 |
18.1% |
|
Germany |
47 |
991 |
5.7% |
53 |
1,085 |
6.2% |
52 |
1,015 |
5.0% |
|
Denmark |
4 |
537 |
3.1% |
5 |
854 |
4.9% |
6 |
572 |
2.8% |
|
Taiwan, China |
13 |
467 |
2.7% |
14 |
462 |
2.6% |
14 |
614 |
3.0% |
|
Poland |
24 |
784 |
4.5% |
13 |
460 |
2.6% |
13 |
516 |
2.5% |
|
Croatia |
5 |
138 |
0.8% |
6 |
273 |
1.6% |
5 |
211 |
1.0% |
|
Romania |
7 |
181 |
1.0% |
7 |
203 |
1.2% |
7 |
307 |
1.5% |
|
Philippines |
1 |
1 |
0.0% |
3 |
155 |
0.9% |
6 |
146 |
0.7% |
|
Turkey |
4 |
41 |
0.2% |
7 |
70 |
0.4% |
9 |
120 |
0.6% |
|
Singapore |
4 |
112 |
0.6% |
3 |
48 |
0.3% |
5 |
92 |
0.5% |
|
Spain |
|
|
|
3 |
36 |
0.2% |
4 |
54 |
0.3% |
|
Netherlands |
6 |
47 |
0.3% |
3 |
32 |
0.2% |
|
|
0.0% |
|
Indonesia |
36 |
18 |
0.1% |
33 |
18 |
0.1% |
21 |
11 |
0.1% |
|
Malaysia |
10 |
7 |
0.0% |
11 |
10 |
0.1% |
7 |
7 |
0.0% |
|
Iran |
7 |
4 |
0.0% |
13 |
7 |
0.0% |
3 |
1 |
0.0% |
|
Egypt |
|
|
|
1 |
7 |
0.0% |
|
|
|
|
Ukraine |
3 |
27 |
0.2% |
1 |
6 |
0.0% |
|
|
|
|
Thailand |
|
|
|
|
1 |
3 |
0.0% |
|
|
|
United Arab Emirates |
|
|
|
|
3 |
2 |
0.0% |
|
|
|
North Korea |
2 |
1 |
0.0% |
2 |
1 |
0.0% |
|
|
|
|
India |
|
|
|
1 |
1 |
0.0% |
1 |
1 |
0.0% |
|
United States |
4 |
31 |
0.2% |
2 |
1 |
0.0% |
1 |
0 |
|
|
Finland |
1 |
23 |
0.1% |
|
|
|
|
|
|
|
Italy |
1 |
28 |
0.2% |
|
|
|
|
|
|
|
Norway |
|
|
|
|
|
|
1 |
3 |
0.0% |
|
United Kingdom |
1 |
2 |
0.0% |
|
|
|
|
|
|
|
Total |
487 |
17,284 |
100% |
532 |
17,489 |
100% |
553 |
20,277 |
100% |
Source: Lloyd's Register - Fairplay
Research
- Vessel Purchase Prices
-
- While it is not possible to determine the current book value of
the liner fleet from available sources, one can measure the amount
of capital originally invested in liner vessels. Cumulatively, more
than $236 billion has been spent on the purchase of new liner
vessels though July of 2009. This number does not include the amount
spent on second-hand sales and or on vessel upgrades or necessary
maintenance and repair.
-
- Cumulatively, European operators have spent the most on liner
vessels, more than $105 billion or 45 percent of total purchases of
liner vessels, as shown in Table 10. This reflects the historical
dominance and a continued strong presence of Europe in liner
shipping. Greater China however is the second largest cumulative
spender on liner vessels, with 15 percent of total spending,
although most of its purchases have been more recent than Europe's.
-
- Table 10: Cumulative Spending on Liner Vessels by Operating
Region through 2009
-
(Million US Dollars)
-
|
Operating Region |
Container |
Vehicle |
Other
Ro-Ro |
Total |
|
South Korea |
11,309 |
299 |
224 |
11,832 |
|
Japan |
15,300 |
16,760 |
2,206 |
34,266 |
|
Greater China |
33,981 |
2,351 |
334 |
36,665 |
|
Other Asia |
648 |
0 |
164 |
812 |
|
Middle East |
8,913 |
179 |
1,009 |
10,101 |
|
South East Asia |
14,969 |
164 |
918 |
16,050 |
|
Europe |
82,365 |
13,882 |
9,433 |
105,681 |
|
Russia |
980 |
15 |
365 |
1,360 |
|
Turkey |
1,165 |
14 |
1,295 |
2,474 |
|
North America |
3,298 |
497 |
1,938 |
5,733 |
|
South America |
5,591 |
203 |
59 |
5,854 |
|
Rest of World |
68 |
8 |
309 |
386 |
|
Unknown |
2,083 |
498 |
2,268 |
4,849 |
|
Total |
180,671 |
34,869 |
20,523 |
236,062 |
Source: Lloyd's Register - Fairplay
Research
- Table 11 combines the cumulative recipients of spending on liner
vessels. As expected, South Korea, the leading shipbuilding country,
has received more than $76 billion or 32 percent of the total.
Europe is ranked next at 27 percent, reflecting its historic
presence in shipbuilding, although many of its yards have been
losing competitiveness and market share. Japan does not lag far
behind Europe, with a cumulative market share of 25 percent. The
United States no longer has a major international commercial liner
vessel building industry.
-
- Table 11: Cumulative Receipts from Sales of Liner Vessels by
Region of Build as of July, 2009
-
(Million US Dollars)
-
|
Building Region |
Container |
Vehicle |
Other
Ro-Ro |
Total |
|
South Korea |
69,781 |
6,087 |
377 |
76,244 |
|
Japan |
34,033 |
21,061 |
4,326 |
59,421 |
|
Greater China |
26,513 |
996 |
974 |
28,483 |
|
Other Asia |
10 |
0 |
80 |
90 |
|
Middle East |
0 |
0 |
278 |
278 |
|
South East Asia |
1,567 |
426 |
1,857 |
3,850 |
|
Europe |
45,771 |
6,221 |
11,151 |
63,144 |
|
Russia |
26 |
0 |
298 |
323 |
|
Turkey |
1,124 |
0 |
79 |
1,203 |
|
North America |
1,597 |
78 |
773 |
2,447 |
|
South America |
202 |
0 |
223 |
425 |
|
Rest of World |
46 |
0 |
107 |
153 |
|
Total |
180,671 |
34,869 |
20,523 |
236,062 |
Source: Lloyd's Register - Fairplay
Research
- LINER FLEET OPERATIONS
-
- This section of the report provides information on the
operations of the liner industry. These statistics are useful for
understanding the scope of liner operations. For example, container
and vehicle vessels made an average of more than 10,100 port calls
in a typical week in 2009, or about 2.1 port calls per vessel per
week. The average vessel also travelled more than 1,100
nautical-miles in a typical week. Seventy four services with almost
15 million TEU of capacity were provided by the industry on the West
Coast of North America and Asia route alone in the middle of 2007.
-
- The liner industry offers transport between all major container
ports world-wide. Inland countries in turn utilize the container
ports of their maritime neighbors in order to participate in
international trade.
-
- Table 12 demonstrates the number of services, or unique ship
schedules and routes, provided by the liner industry as of July 1,
2007. There were 409 services provided by the industry in mid-2007.
It is important to note that the industry frequently modifies its
services in order to respond to changing market forces and the needs
of its customers. The route with the most services is between Asia
and the west coast of North America, particularly reflecting the
large volume of trade between the United States, China and other
Asian countries. Together, the North Europe and the Mediterranean
routes with Asia have 88 unique services.
-
- Table 12: Number of Services and Annual Capacity Deployed by
Route, as of July 1, 2007
-
|
Route |
Services |
|
West Coast of North America - Asia |
74 |
|
East Coast of North America - Asia |
24 |
|
North America - Northern Europe |
36 |
|
North America - Mediterranean |
23 |
|
Asia - North Europe |
35 |
|
Asia - Mediterranean |
43 |
|
North America - East Coast of South
America |
11 |
|
North America - West Coast of South
America |
16 |
|
North America - North Coast of South
America |
22 |
|
Europe - East Coast of South America |
14 |
|
Europe - West Coast of South America |
6 |
|
Europe - North Coast of South America |
13 |
|
Asia - East Coast of South America |
6 |
|
Asia - West Coast of South America |
7 |
|
South Africa - Europe |
6 |
|
South Africa - North America |
3 |
|
South Africa - Asia |
21 |
|
West Africa - Europe |
33 |
|
West Africa - North America |
3 |
|
West Africa - Asia |
13 |
|
Total |
409 |
- Notes: Services may be counted on more
than one route.
-
"Asia" includes Australia and New
Zealand.
-
Sources: ComPair Data, World Line Supply
Report Summary, July 2007;
-
Drewry, Annual Container Market Review and
Forecast - 2007/08.
- Port Calls and Nautical-Miles Travelled
-
- As an indication of the extensiveness of the physical activity
of the liner industry, this section presents measures of port calls
and distances travelled by container and vehicle ships during the
first 35 weeks of 2009. These measures are derived from Lloyds
Register-Fairplay (LRF) Automatic Identification System (AIS), which
tracks the real-time movement of vessels. During this period, LRF's
AIS system tracked a weekly average of 4,800 container and vehicle
vessels, corresponding to about 88 percent of the total container
and vehicle fleet. The AIS satellite system was not in operation
prior to 2009, thus it is not possible to derive these measures for
an earlier time period. However, one would expect a larger number of
port calls and nautical-miles prior to the global recession.
-
- Overall, these vessels made more than 10,100 port calls and
travelled more than 5.4 million nauticalmiles in an average week. An
average container or vehicle vessel made 2.1 port calls per week and
travelled more than 1,100 nautical-miles.
-
- While measures of capacity and vessel counts demonstrate the
overall size of the industry, such operating measures indicate the
swings in its actual utilization and scope of operations as well as
the seasonality inherent in the liner business.
-
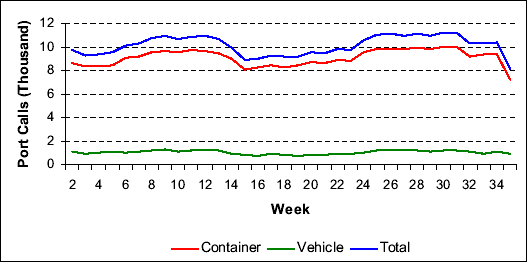
- Figure 1 shows the number of port calls made by container and
vehicle vessels in the first 35 weeks of 2009. On average, container
ships made more than 9,100 port calls and vehicle vessels just over
1,000 port calls per week. In other words, workers at ports
world-wide loaded and unloaded more than 10,000 vessel-stops per
week. The average vessel thus made 2.1 port calls per week.
-
- Figure 1: Average Weekly Port Calls Made by Container and
Vehicle Vessels, First 35 Weeks of 2009
-
Note: The first week of 2009 was a
short week and is excluded.
Source: Lloyd's Register- Fairplay
Research, AISLive.
- Operators from the European Union made more than a third of
these port calls and operators from Greater China and Other Asia
made about 17 percent each.
-
- Table 13: Average Weekly Number of Port Calls Made by
Operator Region in 2009
-
|
Region |
Container
Vessels |
Vehicle
Vessels |
Total |
|
Americas |
388 |
15 |
403 |
|
Greater China |
1,733 |
37 |
1,770 |
|
European Union |
3,505 |
212 |
3,716 |
|
Japan |
573 |
504 |
1,078 |
|
Other Asia |
1,723 |
36 |
1,760 |
|
Other Europe |
1,029 |
224 |
1,253 |
|
Rest of World |
10 |
0 |
10 |
|
Unknown |
156 |
15 |
171 |
|
Global Average |
9,116 |
1,044 |
10,160 |
Note: Average is for the first 35 weeks
of 2009, excluding the first short week.
Source: Lloyd's Register- Fairplay
Research, AISLive.
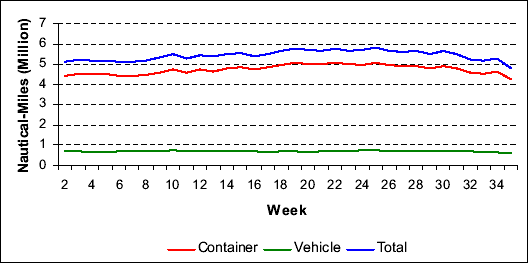
- On average, container ships travelled more than 4.7 million
nautical miles and vehicle vessels travelled 0.7 million nautical
miles per week in the first 35 weeks of 2009. Figure 2 demonstrates
the weekly number of nautical-miles travelled by container and
vehicle vessels during this period. The average vessel thus
travelled 1,132 nautical-miles per week.
-
- Figure 2: Average Weekly Nautical-Miles Travelled by
Container and Vehicle Vessels, First 35 Weeks of 2009
-
Note: The first week of 2009 was a
short week and is excluded.
Source: Lloyd's Register- Fairplay
Research, AISLive.
- Operators from the European Union travelled the most
nautical-miles, or about 36 percent of the total, reflecting the
higher number of port calls made by these vessels.
-
- Table 14: Average Weekly Number of Nautical-Miles Travelled
by Operator Region in 2009
-
(Thousands)
-
|
Region |
Container
Vessels |
Vehicle
Vessels |
Total |
|
Americas |
280 |
14 |
294 |
|
Greater China |
821 |
23 |
845 |
|
European Union |
1,829 |
129 |
1,958 |
|
Japan |
379 |
335 |
714 |
|
Other Asia |
863 |
21 |
884 |
|
Other Europe |
518 |
160 |
678 |
|
Rest of World |
2 |
0 |
2 |
|
Unknown |
49 |
10 |
59 |
|
Global Average |
4,741 |
692 |
5,433 |
Note: Average is for the first 35 weeks
of 2009, excluding the first short week.
Source: Lloyd's Register- Fairplay
Research, AISLive.
- PORT EXPENDITURES AND OPERATIONS
-
- The on-shore portion of the liner industry includes container
and Ro-Ro terminals, container handling equipment such as cranes and
chassis, as well as all the workers needed to load and unload
containers and vehicles and to deliver goods to their final
destinations. All this equipment, as well as containers themselves,
require constant expenditure to manufacture, maintain and operate.
The liner industry thus generates economic activity and employment
not just from vessel construction and operations but also from the
thousands of companies that participate in equipping and operating
ports and the inland portion of the distribution of liner goods.
-
- This section of the report thus quantifies the available data on
expenditures at ports and on liner industry equipment. Only limited
data was available on an aggregated global or regional basis.
Company and port annual reports were also reviewed in order to
highlight activity for select ports, equipment types and companies.
-
- Throughput at the top twenty global liner ports reached nearly
236 million TEU in 2007. Globally, there were more than 17.8 million
containers in the world fleet in mid-2008, costing about $80.1
billion.
-
- Throughput at Liner Ports
-
- Throughput at liner ports is another important indicator of
liner industry activity. Though it was not practical for this study
to estimate the throughput at every liner port, throughput at the
top 20 global ports is presented in Table 15 below. By definition
however, global port volumes must exceed the sum of import and
export TEU, since both the exporting and importing port will count
the containers.
-
- Table 15 has the top 20 world container ports ranked by 2008
TEU. Throughput at the top 20 ports reached almost 250 million TEU
in 2008. These rankings demonstrate the dominance of Asian ports in
container trade. In particular, the throughput at the ports of
Ningbo and Guangzhou in China has been growing rapidly. These ports
now rank seventh and eighth and have overtaken Rotterdam. Kaohsiung
and the ports of Los Angeles and Long Beach in the United States
were particularly affected by the global downturn that started in
2008.
-
- Table 15: Top 20 World Ports by 2008 Throughput
-
|
Rank |
Port Name |
Country |
2007 TEU |
2008 TEU |
|
1 |
Singapore |
Singapore |
27,932,000 |
29,918,200 |
|
2 |
Shanghai |
China |
26,168,000 |
27,980,000 |
|
3 |
Hong Kong |
China |
23,881,000 |
24,248,000 |
|
4 |
Shenzhen |
China |
21,099,000 |
21,413,888 |
|
5 |
Busan |
South Korea |
13,270,000 |
13,425,000 |
|
6 |
Dubai |
United Arab Emirates |
10,653,026 |
11,827,299 |
|
7 |
Ningbo |
China |
9,349,000 |
11,226,000 |
|
8 |
Guangzhou |
China |
9,200,000 |
11,001,300 |
|
9 |
Rotterdam |
Netherlands |
10,790,604 |
10,783,825 |
|
10 |
Qingdao |
China |
9,462,000 |
10,320,000 |
|
11 |
Hamburg |
Germany |
9,889,792 |
9,737,110 |
|
12 |
Kaohsiung |
Taiwan, China |
10,256,829 |
9,676,554 |
|
13 |
Antwerp |
Belgium |
8,175,951 |
8,662,890 |
|
14 |
Tianjin |
China |
7,103,000 |
8,500,000 |
|
15 |
Port Kelang |
Malaysia |
7,120,000 |
7,970,000 |
|
16 |
Los Angeles |
United States |
8,355,039 |
7,849,985 |
|
17 |
Long Beach |
United States |
7,312,465 |
6,487,816 |
|
18 |
Tanjung Pelepas |
Malaysia |
5,500,000 |
5,600,000 |
|
19 |
Bremerhaven |
Germany |
4,912,177 |
5,529,159 |
|
20 |
New York & New Jersey |
United States |
5,299,105 |
5,265,053 |
Source: Lloyd Register-Fairplay
Research
- Table 16 presents data for container ports in the European Union
that publicly report data. The port of Rotterdam is the largest
container port in Europe, with more than 10 million TEU handled in
2008. It is closely followed by the ports of Hamburg and Antwerp.
-
- Table 16: Throughput at Select Container Ports in the
European Union, 2007- 2008
-
|
Country |
Port Name |
2007 TEU |
2008 TEU |
|
Belgium |
Antwerp |
8,175,951 |
8,662,890 |
|
Belgium |
Zeebrugge |
2,020,723 |
2,209,665 |
|
Denmark |
Aarhus |
504,000 |
458,000 |
|
Denmark |
Copenhagen |
192,000 |
n/a |
|
Estonia |
Tallinn |
180,911 |
180,927 |
|
Finland |
Helsinki |
435,000 |
428,000 |
|
Finland |
Kotka |
570,881 |
627,765 |
|
Finland |
Hamina |
195,292 |
178,804 |
|
Finland |
Rauma |
174,531 |
172,155 |
|
Finland |
Pori |
34,415 |
n/a |
|
Finland |
Turku |
21,983 |
22,736 |
|
France |
Le Havre |
2,638,000 |
2,500,000 |
|
France |
Marseilles |
1,001,957 |
847,651 |
|
France |
Dunkirk |
197,000 |
215,000 |
|
Germany |
Hamburg |
9,889,792 |
9,737,110 |
|
Germany |
Bremerhaven |
4,912,177 |
5,529,159 |
|
Germany |
Lubeck |
205,338 |
n/a |
|
Germany |
Cuxhaven |
63,808 |
63,271 |
|
Germany |
Kiel |
20,064 |
12,860 |
|
Germany |
Emden |
51 |
n/a |
|
Greece |
Piraeus |
1,373,138 |
431,000 |
|
Italy |
Gioia Tauro |
3,445,337 |
3,467,772 |
|
Italy |
Genoa |
1,855,026 |
1,766,605 |
|
Italy |
La Spezia |
1,187,040 |
1,246,139 |
|
Italy |
Livorno |
745,557 |
n/a |
|
Italy |
Naples |
460,812 |
481,521 |
|
Italy |
Taranto |
756,000 |
786,655 |
|
Italy |
Venice |
328,000 |
379,072 |
|
Italy |
Trieste |
267,854 |
335,943 |
|
Latvia |
Riga |
211,840 |
207,122 |
|
Latvia |
Ventspils |
16,846 |
14,148 |
|
Latvia |
Liepaja |
7,665 |
4,227 |
|
Lithuania |
Klaipeda |
321,432 |
373,263 |
|
Malta |
Marsaxlokk |
1,887,405 |
2,300,000 |
|
Netherlands |
Rotterdam |
10,790,604 |
10,783,825 |
|
Netherlands |
Amsterdam |
370,000 |
435,129 |
|
Poland |
Gdynia |
614,373 |
610,767 |
|
Poland |
Szczecin |
47,976 |
62,913 |
|
Poland |
Gdansk |
96,873 |
163,704 |
|
Portugal |
Lisbon |
554,774 |
556,062 |
|
Romania |
Constantza |
1,411,370 |
1,380,935 |
|
Slovenia |
Koper |
305,648 |
350,000 |
|
Spain |
Algeciras |
3,414,345 |
3,324,310 |
|
Spain |
Valencia |
2,771,851 |
3,593,000 |
|
Spain |
Barcelona |
2,610,099 |
2,569,547 |
|
Sweden |
Helsingborg |
300,000 |
240,000 |
|
Sweden |
Stockholm |
44,563 |
41,000 |
|
United Kingdom |
Felixstowe |
3,300,000 |
3,200,000 |
|
United Kingdom |
Southampton |
1,900,000 |
1,710,000 |
|
United Kingdom |
Tilbury |
843,808 |
n/a |
|
United Kingdom |
Liverpool (United Kingdom) |
727,363 |
n/a |
|
United Kingdom |
Thamesport |
800,000 |
n/a |
Source: Lloyd's Register- Fairplay
Research
- Table 17 presents throughput levels for container ports in the
United States that publicly report data. The ports of Los Angeles
and Long Beach are the largest ports in the United States as
measured by throughput, followed by the port of New York and New
Jersey.
-
- Table 17: Throughput at Select Container Ports in North
America, 2007
-
|
Port Name |
2007 TEU |
|
Los Angeles |
8,355,039 |
|
Long Beach |
7,312,465 |
|
New York & New Jersey |
5,299,105 |
|
Savannah |
2,604,401 |
|
Oakland |
2,388,182 |
|
Vancouver, B.C. |
2,307,289 |
|
Hampton Roads |
2,128,366 |
|
Seattle |
1,973,504 |
|
Tacoma |
1,924,934 |
|
Houston |
1,768,627 |
|
Charleston |
1,754,377 |
|
Baltimore |
624,462 |
|
New Orleans |
315,375 |
Source: Lloyd's Register- Fairplay
Research
- Expenditures by Terminal Operators
-
- Although it is not possible to determine the precise amount of
the total investment in liner ports worldwide, we know that the
investment levels are on the order of several billion dollars per
year.
-
Example investment levels of the top private terminal operating
companies have been over $2.6 billion to almost $4 billon per year
for the last two years. In 2007, these terminal operators held a
market share of about 37 percent so their investment of
approximately $2.6 billion in property, plant, equipment and other
capital, if extended to the rest of the liner market would have been
over $7 billion in 2007 and over $10.5 in 2008 alone. Although a
portion of these investments are in non-liner terminal facilities,
it is a conservative assumption that most of the billions of dollars
are invested annually in liner port facilities worldwide.
-
- Table 18: Investment by Terminal Operators, 2007-2008
-
(Million US Dollars)
-
|
Operator |
Cash Flow Use |
2007 Market Share |
2007 |
2008 |
|
APM Terminals |
Capital Expenditures |
12.1% |
853 |
723 |
|
PSA |
Property, Plant, Equipment |
11.0% |
1,086 |
1,313 |
|
DP World |
Expansions, Maintenance, New Projects |
8.7% |
N.A. |
1,397 |
|
COSCO Pacific |
Property, Plant, Equipment |
5.5% |
683 |
522 |
|
Total |
|
37.3% |
2,622 |
3,955 |
Sources: Company Annual Reports; Drewry
Shipping Consultant Limited, 2008.
- Container Fleet
-
- Globally, in mid-2008 there were 17.8 million containers in the
world fleet providing 27.3 million TEU of capacity, and which cost
the industry almost $81 billion. This was an increase from about
24.8 million TEU of capacity the previous year. Europe accounts for
the largest container fleet at 6.9 million units or nearly 39
percent of the total fleet. North East Asian and North American
owners account for nearly the rest of the global fleet, reflecting
the location of company headquarters that own the containers, not
the deployment of the containers which move throughout the world.
-
- Table 19: Container Fleet by Region, Mid-2008
-
|
Region |
TEU |
TEU Share |
Units |
Unit Share |
Cost (US$ million) |
Cost Share |
|
Europe |
10,427,987 |
38.1% |
6,917,319 |
38.7% |
36,365 |
44.9% |
|
North East Asia |
7,674,963 |
28.1% |
4,990,588 |
28.0% |
19,588 |
24.2% |
|
North America |
7,648,952 |
28.0% |
4,823,997 |
27.0% |
20,698 |
25.6% |
|
Middle-East & Indian Sub-Continent |
926,730 |
3.4% |
609,693 |
3.4% |
2,285 |
2.8% |
|
South East Asia |
477,371 |
1.7% |
362,561 |
2.0% |
1,267 |
1.6% |
|
Australia & New Zealand |
86,210 |
0.3% |
73,751 |
0.4% |
383 |
0.5% |
|
Central & South America &
Caribbean |
64,670 |
0.2% |
41,987 |
0.2% |
232 |
0.3% |
|
Africa |
36,834 |
0.1% |
32,656 |
0.2% |
98 |
0.1% |
|
Total |
27,343,717 |
100.0% |
17,852,552 |
100.0% |
80,916 |
100.0% |
Note: Includes containers specific to
regional standards.
Source: Containerisation International
Market Analysis: World Container Census 2009, Table 8.
|
4 |
The three metrics each have their purpose
for measurement of container handling activity. Most fundamentally
is the port-to-port movement of loaded containers carrying goods
that shippers are paying to have moved. This is from the
perspective of a shipper or customs authorities who are concerned
with the ultimate origin and destination for the delivery of the
goods. Operational efficiency of the liner system is improved
through the use of transhipment where containers are transferred
during their journey between vessels at an intermediate port. The
transshipment activity is valuable to the operators and ports that
provide this service and counting this activity is another measure
of container handling provided by the liner industry. At container
port terminals there are often operational needs to move
containers on and off ships and within terminals not just one time
at the original port of loading or discharge for each leg of a
container's journey. This can include when containers need to be
unloaded temporarily from a ship in order for other containers to
be accessible or for reloading of containers onboard vessels for
stability or access at a subsequent port call. This can be thought
of as additional port handling of containers. |
|
|
- The volume of container handling world-wide is measured from
several perspectives. When all measures of container handling are
combined, the total world container handling activity in 2007 was
almost half a billion twenty-foot equivalent units (497 million
TEU). This included movements of over 224 million loaded and empty
TEU between the ports of the world, and 137 million TEU of
transhipment activity.4
-
This type of container handling at ports can be considered essential
to the efficient operations of the industry and it takes resources
at the terminals to provide, so ports appropriately count this
activity as well.
-
- Table 20: Container Handling and Transhipment, Million TEU,
2007
-
|
|
PORT TO PORT |
TRANSHIPMENT |
PORT HANDLING |
TOTAL |
|
Loaded |
120.3 |
108.4 |
86.0 |
314.7 |
|
Empty |
104.2 |
28.6 |
49.9 |
182.7 |
|
Total |
224.5 |
137.0 |
135.9 |
497.4 |
Source: IHS Global Insight Analysis and
the IHS Global Insight World Trade Service.
- Other Liner Industry Equipment
-
- Aside from containers, the industry relies on numerous types of
on-board and port terminal equipment to handle liner cargo. One of
the most complex and expensive types of equipment are the
ship-to-shore gantry cranes. Comprehensive public data on the world
inventory of port cranes and their associated costs is unavailable,
but ports do invest millions of dollars in cranes in most years. The
largest container port alone, the Port of Singapore, has 190 cranes.
The port of Shanghai and the port of Rotterdam each have just over
100 cranes. The ports of Los Angeles and Long Beach each have about
70 cranes. A typical new state-of-the-art crane cost about $10
million in 2007 to provide some perspective on the value of these
equipment investments. As the containerization of cargo continues to
spread world-wide, investment in such equipment is sure to
accelerate.
-
- Once a container is unloaded at the port, it is often loaded
onto a specially designed truck-trailer or chassis for transport by
motor carrier to its final destination.
-
- Table 21 below demonstrates the chassis count in the United
States along with the estimated annual cost of operating that fleet.
The chassis fleet in the United States alone costs about $869
million a year to operate.
-
- Table 21: Chassis Fleet and Operating Costs in the United
States, 2008
-
|
Owner Type |
Count
(Thousand) |
Average Annual
Operating Cost
(Million) |
|
Ocean Carriers |
392.1 |
401 |
|
Railroads |
96.2 |
98 |
|
Common Pool Operators |
320.0 |
327 |
|
Motor Carriers |
41.8 |
43 |
|
Total |
850.0 |
869 |
Source: Requirements for Intermodal
Equipment Providers and for Motor Carriers and Drivers
Operating Intermodal Equipment; Final Rule
49 CFR Parts 385, 386, 390, et al.
December 17, 2008.
- Summary
-
- The liner industry has been essential to the facilitation and
expansion of world trade, contributing to global economic growth and
improvements in the standard of living in both developed and
developing countries. This report provides an overview of various
economic, trade, and operating metrics that demonstrate the value of
the liner industry to specific regional and individual country
economies as well as the world as a whole.
-
- This report confirms the industry's profound global economic
impact, particularly in Europe, the United States, Asia, and the
rest of the Americas. Globally, the full value of the liner industry
operations and shipbuilding in 2007 is estimated to be $436.3
billion, and generated 13.5 million direct and related jobs.
-
- The liner industry is the largest sector of the maritime
industry when measuring the value of world trade transported, moving
about 60% of global seaborne trade. This was over US$4.3 trillion of
goods in 2007 alone. The liner industry draws significant investment
in capacity, using over 7,000 vessels that cost the industry
initially over US$235 billion to acquire plus another US$80 billion
to equip the vessels with containers in which to move cargo.
Landside terminals represent additional billions of capital
investment from the industry. The liner industry incurs operating
costs that produce output valued at $142 billion annually which make
the extensive capital investments available and useful to shippers
worldwide for the transportation services they need.
-
- Using the existing metrics available to economists, the
estimates of the value of the industry to the world economy
understate the importance of the liner industry to the daily lives
of most of the world's population. Without the efficient
facilitation of trade provided by the liner industry, the standard
of living of most families and the financial health of most retail,
wholesale, manufacturing and services businesses would be reduced.
-
- Appendix A: World Industry Service
Methodology
-
- IHS Global Insight's World Industry Service (WIS) includes both
historic and forecast economic data covering 95 industries in 75
countries.
-
- DATA SOURCES
-
- The basic data in World Industry Service is taken from public
sources; but is then processed extensively and filled out using
established techniques.
-
- The initial set of industry-based data is drawn from
complementary primary public sources:
-
- Industrial Structure Statistics, from the OECD-STAN
database;
- International Yearbook of Industrial Statistics, from the
United Nations Industrial Development Organization (UNIDO) ;
- National Accounts Statistics: Main Aggregates and Detailed
Tables, from the United Nations System of National Accounts
(UNSNA) ;
- Yearbook of Labour Statistics, from the International
Labour Organization (ILO) ;
- Structural Business Statistics, from Eurostat database.
- The number of countries whose industry data is included in the
OECD database is restricted to members of the OECD organization.
Fortunately, these countries are also the largest countries
economically in the world and include the United States, Japan,
Germany, France, and others. For those countries whose data is not
included in the OECD database, and also for those industries whose
coverage in STAN is not detailed enough, WIS uses a combination of
UNSNA and UNIDO databases. The data from these organizations have
the desirable attributes of fine detail, consistency, and
comparability. ILO and Eurostat are also used as specific
complementary sources of data. Finally, both the UN- and
OECD-supplied data are supplemented by individual country sources.
-
- Thus, the historical dataset in World Industry Service is built
like a pyramid with three layers:
-
- The bottom layer is the UNSNA and UNIDO data, which provides the
baseline for data for all countries and all sectors;
- The next layer up is the OECD data, which replaces UN data in
those countries/industries where there is overlap ;
- Finally, the top layer represents data that comes from
individual country sources, or from global trade associations and
other specific data sources. These “specific-sourced”
data are used to bring the OECD and UN data forward in time to
provide a timely “now-cast” snapshot of the latest
available measures of industry-level business activity.
- Note that employment and labor compensation data is taken
directly from UNIDO statistics, and is not processed or modified in
any way.
-
- WATER TRANSPORT AND SHIPBUILDING SECTORS
-
- In order to determine appropriate economic values for the liner
industry, this report concentrated on two industries within WIS:
water transport and shipbuilding.
-
- Water Transport: defined as International Standard of
Industrial Classification (ISIC) code 61 (Water Transport). This
category includes sea, coastal and inland water transport. Included
is transport of passengers or freight over water, whether in
scheduled service or not. Also included are the operation of towing
or pushing boats, excursion, cruise or sightseeing boats, ferries,
and water taxis. The category requires transport service be provided
to be included by definition. Therefore excluded are restaurant and
bar activities on board ships, except when delivered as an integral
part of transportation. Also excluded are landside cargo handling,
storage of freight, plus harbor operation and other auxiliary
maritime activities such docking, lightage and vessel salvage that
are not directly transportation services.
- Shipbuilding: defined as ISIC code 351 (Building and
Repairing of Ships and Boats). This category includes the
manufacturing, repairing, overhaul and the manufacturing of sections
for the following type of commercial vessels and floating
structures: vessels used in commerce, in pursuits related to
commerce or in the carriage of passengers including multi-purpose
vessels; vessels designed for ocean, coastal or inland waters;
passenger vessels, fishing boats and fish processing factory
vessels; tugs and pusher craft; non-motorized vessels such as
barges, stationary vessels such as light-ships; non-navigational
vessels such as dredgers, floating docks, and floating or
submersible drilling platforms; hovercraft; boats with hulls
resembling pleasure boats but specially equipped for commercial
service or services related to commerce; warships and auxiliary
naval vessels; vessels for scientific investigation; floating
structures such as pontoons, non-recreational inflatable rafts;
coffer-dams, landing stages, buoys, floating tanks and others.
Also
included are the manufacturing, maintenance and repair of the
following types of noncommercial vessels: yachts, rowing boats,
canoes, dories, skiffs, oared life-boats, cutters, kayaks, racing
shells, pedalos, rafts, inflatable boats and other pleasure and
sporting vessels; pleasure boats designed to accept inboard or
outboard motors or to be propelled by wind, paddles or oars; larger
boats such as cabin cruisers and sport fisherman.
Excluded
are: manufacture of parts of vessels such iron or steel anchors and
sails and other parts that are not major hull assemblies;
navigational and other instruments used aboard ships; and amphibian
motor vehicles.
- LINER INDUSTRY SHARE
-
- The following methodologies were used to extract the liner
portion of these industries:
-
- Water Transport: A trade ratio was applied to each
country with data in the WIS. The ratio for a given country is the
value of liner trade relative to its total seaborne trade. This
ratio does not account for passenger and inland water transport that
is included in the WIS data, and thus somewhat overstating the liner
portion of the water transport industry. At the same time, the water
transport industry within WIS excludes important liner industry
elements such as cargo handling, storage of freight, docking and
other harbor and terminal operations. This means the estimate
understates the liner industry because of the other operations it
excludes. At this level of detail it is not possible to tell which
effect is larger, the inclusion of inland and passenger transport,
or the exclusion of port and related land-side operations, though
they clearly largely offset each other.
- Shipbuilding: Countries that have a shipyard that
delivered a liner vessel (container, Ro-Ro or vehicle) in 2007 were
identified first. Next, for each country we determined the ratio of
the grosston capacity of the liner vessels relative to the gross-ton
capacity of all shipping vessels delivered by the country in the
same year. This ratio was then applied to estimate the liner portion
of shipbuilding from the WIS data.
- DEFINITION OF WIS METRICS
-
- WIS was used to derive the amount of Capital Expenditures, Gross
Output, Labor Compensation and the number of Employees attributable
to the liner industry's shipping services as well as the liner
portion of shipbuilding. The following are the definitions of these
four metrics:
-
- Capital Expenditures: refers to investments made by
establishments operating in the industry during the reference year
(2007), net of fixed assets sales. The investments covered are those
(whether new or used) with a productive life of one year or more.
These assets are intended for the use of the establishments’
own labor forces. Major additions, alterations, and improvements to
existing assets that extend their normal economic life or raise
their productivity are also included.
Capital Expenditures in the
liner industry would thus include investment in any type of
equipment and vessels used by liner operators. The category would
also include machinery and equipment purchased by shipbuilders in
order to construct liner vessels. Sales of any equipment are
subtracted from the totals.
- Gross Output: also called total sales or total
production. This measures the total revenue that is earned by a
sector’s operating activities. It includes the domestic
production that is exported abroad, but excludes imports that are
produced abroad. Gross output thus includes all operating
expenditures, wages and benefits and company profits.
- Labor Compensation: includes both wages and fringe
benefits.
- Number of Employees: the number of people directly
employed by the sector. For this report, this includes employees in
liner services and in the construction of liner vessels.
- Appendix B: Data Sources
-
- AXS-Alphaliner, Cellular Fleet
Forecast, September 2009.
-
- AXS-Alphaliner, Top 100 - Existing
Fleet on September 2009.
-
- American Association of Port Authorities,
www.aapa.org.
-
- Clarksons Research Services, Shipping
Intelligence Network data, 2009.
-
- Containerization International,
Containerization International Yearbook 2004.
-
- Containerization International Informa
Cargo Information, Fleet as of September 3, 2009.
-
- Containerization International Informa
Cargo Information, Market Analysis: World Container Census 2009.
-
- Drewry Shipping Consultant Ltd, Annual
Container Market Review and Forecast - 200708 September 2007.
-
- Drewry Shipping Consultant Ltd, Annual
Container Market Review and Forecast - 2008/09. September 2008.
-
- Drewry Shipping Consultant Ltd, Container
Forecast Annual Supplement, 4Q08.
-
- Eurostat, Maritime Transport of Goods
and Passengers 1997-2007.
-
- IHS Global Insight, World Industry
Service, 2009.
-
- IHS Global Insight, World Trade
Service, 2009.
-
- Institute of International Container
Lessors, 2009 IICL Annual Leased Container Fleet Survey, June 8,
2009.
-
- International Association of Ports and
Harbors, http://www.iaphworldports.org/.
-
- Lloyd's Registry-Fairplay Research, Vessel
Registry, Vessel Characteristics and Movements data, 2009.
-
- Martin Associates, JWD, and WEFA, U.S.
Economic Growth and the Marine Transportation System, December,
2000.
-
- Oosterhaven, J, and Stelder, T.M., On
the Use of Gross versus Net Multipliers, August, 2000.
-
- Requirements for Intermodal Equipment
Providers and for Motor Carriers and Drivers Operating Intermodal
Equipment; Final Rule 49 CFR Parts 385, 386, 390, et al.
December 17, 2008.
-
- Stopford, Martin, Maritime Economics,
3rd edition, Routledge, 2009.
-
- U.S. Maritime Administration, MARAD
Port Economic Impact Kit (MARAD Port Kit) Ver 1.1, December
2000.
-
- U.S. Maritime Administration, Public
Port Finance Survey for FY 2006, December 2008.
-
- U.S. Maritime Administration, U.S.
Public Port Development Expenditure Report (FYs 2006 &
2007-2011), February 2009.
-
- World Shipping Council, The Liner
Shipping Industry and Carbon Emissions Policy, September 2009.
-
- World Shipping Council, The Liner
Shipping Industry's Impact on the US Economy. 2000
-
|
Port Crane Manufacturers and 2007 Annual Reports of
Public Companies |
|
|
|
|
|
Hyundai |
|
|
IMPSA |
|
|
Kalmar Industries |
|
|
Konecranes |
|
|
Liebherr Container Cranes |
|
|
Mitsubishi Heavy Industries, |
|
|
Mitsui |
|
|
Paceco |
|
|
Samsung |
|
|
TCM Corporation |
|
|
Zhenhua Port Machinery Company (ZPMC) |
|
|
|
|
Liner Operator Websites |
|
|
|
|
|
APL (NOL) |
|
|
A.P. MÖller-Maersk |
|
|
Atlantic Container Line |
|
|
COSCO (Cosco Container Lines) |
|
|
China Shipping Group |
|
|
CMA-CGM Group |
|
|
Compania Chilena Navegacion Interoceanica |
|
|
Compania Sud-Americana de Vapores |
|
|
Crowley Maritime Corporation |
|
|
Dole Ocean Cargo Express |
|
|
Evergreen Maritime Corporation |
|
|
Hamburg Süd |
|
|
Hanjin Shipping Company |
|
|
Hapag-Lloyd Container Line |
|
|
Hoegh Autoliners, Inc. |
|
|
Hyundai Merchant Marine Company |
|
|
Independent Container Line |
|
|
Kawasaki Kisen Kaisha Ltd. (K Line) |
|
|
Malaysia International Shipping
Corporation (MISC) |
|
|
Mediterranean Shipping Company (MSC) |
|
|
Mitsui O.S.K. Lines |
|
|
NYK Line |
|
|
Orient Overseas Container Line, Ltd.
(OOCL) |
|
|
Pacific International Lines, Ltd. |
|
|
United Arab Shipping Company |
|
|
Wan Hai Lines, Ltd. |
|
|
Wallenius Wilhemsen Logistics, |
|
|
Yang Ming Marine Transport Corporation |
|
|
Zim Integrated Shipping Services, Ltd. |
|
|
|
|
Terminal Operator Websites and 2007 Annual Reports (if
Public) |
|
|
|
|
|
APM Terminals |
|
|
COSCO Pacific, Limited |
|
|
DP World |
|
|
Eurogate |
|
|
Hutchinson Whampoa, Limited |
|
|
International Container Terminal
Services, Inc. |
|
|
Port America |
|
|
PSA International |
|
|
SSA Marine |
|
|
|
|
Top 20 Port Websites |
|
|
|
|
|
Port of Singapore, Singapore |
|
|
Port of Shanghai, China |
|
|
Port of Hong Kong, China |
|
|
Port of Shenzhen, China |
|
|
Port of Yingkou, China |
|
|
Port of Busan, South Korea |
|
|
Port of Rotterdam, Netherlands |
|
|
Port of Dubai, United Arab Emirates |
|
|
Port of Kaohsiung, Taiwan, China |
|
|
Port of Hamburg, Germany |
|
|
Port of Qingdao, China |
|
|
Port of Ningbo, China |
|
|
Port of Guangzhou, China |
|
|
Port of Los Angeles, United States |
|
|
Port of Antwerp, Belgium |
|
|
Port of Long Beach, United States |
|
|
Port of Kelang, Malaysia |
|
|
Port of Tianjin, China |
|
|
Port of Tanjung Pelepas, Malaysia |
|
|
Port of New York/New Jersey, United
States |
|


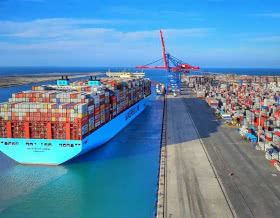
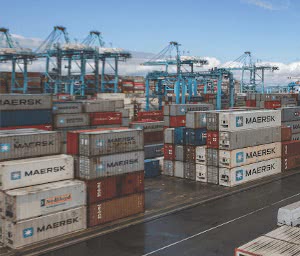




 - Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA


