testata inforMARE
Cerca
01 de noviembre de 2026 - Año XXX
Periódico independiente sobre economía y política de transporte
01:18 GMT+1
LinkedInXFacebook
FORUM de lo shipping y
de la logística


Shipping and Shipbuilding Markets in 2002

I N D E X


The containership market in 2002


The freight market
 
Fleet growth versus demand
The operators
The fleet
The second-hand market


The year 2002 can be summed up as a year of convalescence, after the 2001 traumas, while 2003 is hopefully to see full health recovered ' at least in the absence of any unpredictable event.

Indeed, 2002 has been also a transitional year on another front, as new, stringent rules on container content monitoring and cargo manifests have been elaborated by the U.S. administration to prevent unwanted weapons entering the U.S. The year 2003 will see these rules coming into force.

During the implementation phase, hiccups will surely occur, resulting in ship delays. Carriers said that they will have to pass the costs of these measures onto shippers, although it is not yet clear if it will be through rate increases or through a 'U.S. cargo manifest' surcharge.
 
The freight market

2002 has been a mixed year, with varying fortunes witnessed by operators. Some of them expected to close the year with comfortable profits while others are deep in the red.

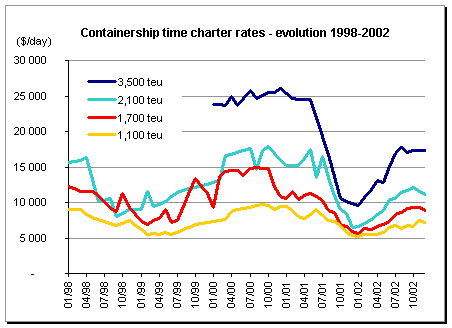
Charter rates for containerships have increased by around 75 % on average since the January 2002 lows. At least the rise lasted until November, when the winter season and its lower volumes of cargoes started to take effect.

Rates eased slightly during the last weeks of 2002, but were expected to rise again in the first quarter of 2003. Relatively strong rates can be anticipated for the next summer season, boosted by traditional high seasonal volumes and a well-balanced supply / demand ratio.

The larger the ship, the more volatile the rates. This is well illustrated by the fluctuation in rates for modern 3,500 teu ships, which plunged from $ 25 / 26,000 in the Summer 2000 to $ 10,000 in January 2002. They have recovered month after month in the first part of 2002 to stagnate around $ 17,500 in the second part of the year. Meanwhile, rates for 1,100 teu ships went down from $ 9,500 (summer 2000) to $ 5,250 (January 2002), and $ 7,000 / 7,500 during the last quarter 2002.

Having plunged under the $ 6,000 mark in January 2002, the rates for 1,700 teu ships -such as the B-170s- have risen to reach $ 9,500 in October 2002 before easing just under $ 9,000 at the year end. There is some way to go before flirting again with the $15,000 figure of the summer 2000.

The fleet of cellular ships over 1,000 teu identified as idle (not including those which underwent routine general repairs) has decreased from 160,000 / 180,000 teu during the first four months of 2002 to around 60,000 teu during the summer. Is was expected to increase slightly after the summer season, but it did not, thanks to the lock-out in the USWC ports, which has prolonged artificially the demand for 1,000 to 2,500 teu ships in order to scoop up the boxes left in Asia by delayed main-line ships. At the beginning of 2003, the idle fleet stood at 65,000 teu. Interestingly, there were no large ships identified as mothballed. The situation is indeed very different from one year ago.

Industrial production is rising again in most south east Asian countries while the export boom in China seems endless. As this region of the world generates high containerised cargo volumes, it governs the supply/demand balance in container transportation more than other regions.

In 2001, the world seaborne trade contracted by 1 %. It is now growing again. After a period of stalling during the winter 2001-2002, the demand in container transportation has, surprisingly, recovered above all expectations. The volume of containers carried at sea is expected to grow by 7 or 8 % in 2003, in line with growth rates observed in the 1990s.

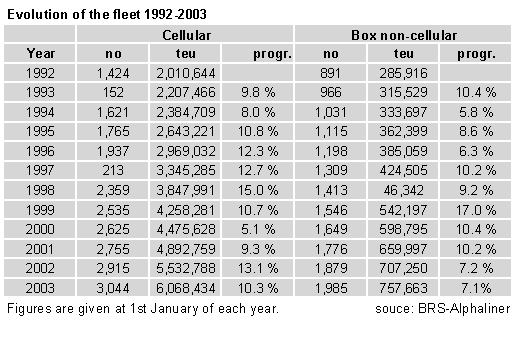
The demand in container transportation may even surpass these figures. The cellular fleet has risen by 10.8 % per annum over the past 7 years. The way the market has absorbed this extra capacity is remarkable. So, with an expected cellular fleet growth of 'only' 7.5 % per annum for the years 2003 and 2004, the market will be on the owners side.

Another factor which may have a strong impact on rates is the trend of East Asian-U.S. cargoes shifting from the U.S. West Coast ports to the U.S. East Coast, to the detriment of rail 'landbridges'. The Panamax ships of 4,000+ teu are much sought after for the Far East-USEC services that have to transit the Panama Canal.

The longer transportation distance means that eight or nine ships are needed on such services instead of five or six for the Far East-USWC option. Assuming that, say, four new Far East-USEC routes are launched, it means that a dozen supplementary Panamax ships are needed. This can be sufficient to create a shortage of such ships, and could send the charter rates soaring for 4,000 teu ships.
 

Fleet growth versus demand

The fleet growth is expected to match the rise in demand, at least during the years 2003 and 2004. A tight market may well even develop if the 10 to 11 % growth in containership demand observed since the mid-1990s is to continue.

This spectacular growth rate of the cellular fleet will not be repeated in the two years to come. It will hover around 7.5 % (see accompanying table). This will lead to a fleet of 7 million teu in January 2005, up from 6 million teu in January 2003 and 3 million teu in January 1996.

In fact, to keep up with the average yearly increases of 7 % in the seaborne container trade observed during the past decade, the cellular fleet should have grown from 3 million teu in 1996 to 4.8 million teu in early 2003 (notwithstanding the increase in average ship speed and box handling productivity).

So, the extra 1.2 million teu of on board capacity added to reach the 6 million teu figure has been filled with goods which were either already containerised, but were moved on general cargo vessels or simply not containerised half a decade ago. Breakbulk liner services continue to fade away as the cargoes they carry shift to the box (see inset).

This leads to think that, in the first instance, owners and operators were right to invest so massively in container tonnage. However, the balance is fragile. Most operators are struggling in trying to make profits, and economic accidents are catastrophic for the bottom line.
  

The dwindling breakbulk services

As the container continues to make inroads into the breakbulk sector, the surviving regular conventional services see their volumes dwindle year after year, vanishing like fading stars. Each year brings it examples. In 2002, the U.S. Gulf-Brasil service operated by Brasilian operator Global Transporte Oceanico (GBTO) was closed. This service used to be run with up to five 17,000 dwt / 500 teu ships in the mid 1990s (mostly Astrakhan tonnage), then lost progressively its grip on the market as competitive container services were incessantly upgraded, up to the unavoidable weekly frequency and with unbeatable transit times. High volumes of specific cargoes (such as CKDs - Cars Knocked Down) and the boxes still carried on these multipurpose ships were more and more siphoned off by full container ships, while cheaper box rates helped to attract low value 'breakbulk' cargoes. And as the cargoes flee the conventional ships, less and less sailings were offered. Eventually, these services lost their remaining appeal with regular shippers.
 

As for the non-cellular fleet deployed on liner trades, it includes multipurpose cargo vessels, ro-ro ships and a few conbulkers. Some of these non- cellular ships are currently deployed on liner trades, and as far as they can be identified they total some 1,550 units of 100 teu and over, representing around 800,000 teu.

By comparison, in early 1996, the figure for these ships stood at around 2,600 units for almost 1.1 million teu. Thus, the non cellular component of the liner fleet has lost 1,050 ships for some 0.3 million teu in 6 or 7 years, which can be assumed to have shifted to cellular ships (and this is a maximum figure as many general cargo ships and ro-ros do not make full use of their teu capacity).

This still leaves us with a differential of almost 1 million teu, which can be assumed as having absorbed cargoes not yet containerised in the mid-1990s as well as empty boxes carried in larger quantities than ever before.

In addition, it can be said that these massive investments spurred competition so that box rates reached such low figures that the container sector now attracts low value cargoes or goods of a certain value, which were until recently cheaper to carry in conventional or bulk carrying tonnage, such as steel products, forest products or bagged sugar.
 

No reversal expected in the box rates downtrend

Should this trend continue, as there are still a lot of goods that could be containerised, container tonnage could be ordered massively and yet be filled. The question is of course the cost for carriers' It is a nonsense to carry waste paper on ships plying at 25 knots but such low value cargoes make a few bucks when repositioning otherwise empty boxes, which is better that nothing at all. Conversely, a lot of not so cheap consumer goods are carried at a cost representing a tiny fraction of their prices as displayed on the retail shelf.

The industry is still fragmented, with the 'Top 10 carriers' controlling roughly 50 % of the market. So there is room for bitter rivalry. Intense competition between carriers and the race for market share have driven rates down over the years, and there are no signs of a reversal of this trend. Instead, the container shipping industry is under constant pressure not only from shippers -which is natural- but also, more artificially, from regulators, which suspect every form of alliance or sharing agreements to generate cartel-like behaviour.

And with 4,000+ teu ships starting to find their way on North-South trades, the box rates are expected to plunge further in the long term on these trades, in corollary to the economies of scale that these large ships allow.
Fragmentation, competition pressure and the race to market share are powerful incentives for mergers and acquisitions. On the other hand, the destruction of value, which has followed large mergers in the recent past (in sectors ranging from the automotive industry to the telecom and steel industries) appears as a strong deterrent. There has been a lull in the consolidations since the late 1990s. A new round of mergers is inevitable. But who can dare say when it will happen, and in what context ?
 

The deadweight comes back in vogue

The cargoes which have shifted to the container over the recent years are generally significantly heavier than the cargoes traditionally stuffed in boxes. The deadweight capacity of containerships now takes on a greater significance than ever before. With most liner statistics focusing on teu, the deadweight capacity has been forgotten. It is now time to reinstate it. After all, the cellular fleet nom reaches 85 million dwt, which represents roughly 10 % of the deadweight tonnage of the world merchant fleet.

The traditional items carried by containers are light ones, both in their own nature (think of the volume to weight ratio of a TV set) and because of the packing used (think of the super light polyester pads which protect this same TV set in its bulky cardboard box) ' not to mention boxes full of Christmas balls which flow periodically out of China. Light boxes have now to share ship slots with boxes fully laden in weight.

Modern cellular ships are designed in such a way that the average load of teu carried stands at around 12 to 13 tons per teu, which leaves roughly 10 tons of cargo per teu after subtraction of the box tares, and allowance for bunker supplies.
Most of the time, ships are today fully laden in weight well before deck cargoes are complete. Fortunately, empty boxes have often to be repositioned on the legs where the average loaded box weight is high. Thus, deck cargoes are topped up with these empty boxes, provided that allowance has been planned to take their light weight into account.

The operators

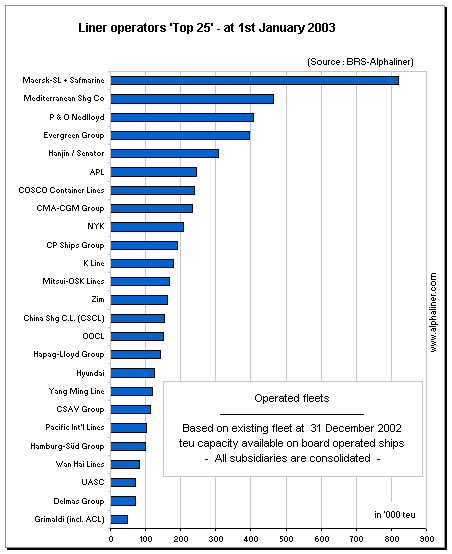
The liner shipping industry is not as concentrated as other industrial sectors. It is scattered among some 300 operating groups operating 4,650 ships deployed on liner trades worldwide, representing 6.3 million teu at the closure of the year 2002, of which only 1 % were inactive, according to BRS-Alphaliner data.

The largest of them, Maersk-SeaLand, operates a capacity of 825,000 teu, representing 12 % of the global active capacity in teu terms. The next in size is MSC, with 6.8 % of the global capacity.

There have been only minor transactions in 2002. The most significant ones have been the sale by Andrew Weir & Co of most of its services to Hamburg-S'd (which bought the Ellerman Line) and CMA CGM (which bought MacAndrews and UBC), the sale by D'Amico di Navigazione of Italia Line to C.P. Ships and the sale by CSX of its container shipping activities to US investors. Interestingly, the ships owned by the sellers were not involved in the Andrew Weir and D'Amico deals, and were merely chartered in. Other transactions are summed up in the accompanying table.

There are larger deals in the offing. P&O Nedlloyd could become a target when it will be introduced on stock exchanges (which was postponed). APL, which suffers from heavy losses, is also prone to accept an M&A deal (although APL parent company NOL is to raise cash from the planned sale of its tanker subsidiary AET). The privatisations of Zim and S.C. India are still in the news, although they have stalled for political reasons.

East-West niche carriers are also downsizing their operations as they cannot compete with global organisations employing large, economic ships. In 2002, Trans Pacific Line (TPL) left the Asia-U.S. trade while Sinotrans left its Asia-Europe trade. Senator Linie has also left all its U.S.-related trades, which have been in fact shifted to its parent company Hanjin.


Operators : transactions and significant moves in 2002

Straight sales

  • Hamburg-S'd bought the Ellerman Line from Andrew Weir & Co.

  • CMA CGM bought MacAndrews and UBC from Andrew Weir & Co.

  • C.P. Ships bought Italia Line from D'Amico di Navigazione.

  • CSX Corp. (U.S.) reached an agreement to convey its domestic container shipping unit CSX Lines LLC to a venture formed with the Carlyle Group (effective 2003).

  • A.P. M'ller bought the liner division of Copenhagen-based Torm A/S D/S.

  • Navalmar Transportes Maritimo (Boggazzi Group) bought 50 % of the stock of Nordana Line A/S from Dannebrog.

  • CSAV bought the Norsul container shipping activities (Brasil), which were limited to its participation in the 'Good Hope Express'.

  • Sea Star Line (U.S.) bought Navieras de Puerto Rico (U.S.) from Holt (U.S.).

  • Tropical Shipping (U.S.) bought certain assets of Tecmarine Lines and TMX Logistics (U.S.).

  • Seaboard Marine (U.S.) bought the remaining services of Tecmarine (U.S.).

  • Wan Hai took over the customer base of Trans Pacific Line.

Transfers within operating groups

  • The Preussag Group bought the remaining 0.4 % of Hapag-Lloyd shares, giving it the whole control of the company.

  • Tschudi & Eitzen (Norway) gained 100% ownership of the Estonian Shg Co.

  • NYK completed its stake in TSK (its intra Asian arm), gaining 100% ownership.

  • Evergreen International Storage and Transport Corp. bought Uniglory (intra Asian arm of Evergreen) through a share swap.

Cessations of activity

  • International Shipping Line (ISL) was terminated after Belgium - based MCL Shipping (Maritime Chartering & Liner Shipping Company NV, which managed the ISL service) filed for bankruptcy (ISL operated a North Europe - West Africa breakbulk service).

  • Valuship ceased its activities after the failure of its  WCNA-Europe service.

Significant other moves

  • Senator Linie (Germany, 75 % Hanjin ownership) left all the services involving the U.S.

  • Sinotrans left the China-Europe trade.

  • Fu Hai Line halted its Far East-South Africa service.

  • Coral Container Line (Cuba) closed its own Med-Cuba service and opted for slot buying.

  • Global Transporte Oceanico (Brasil) closed it U.S. Gulf-Brazil multipurpose service.

  • Libyan carrier GNMTC ran into difficulties.

The fleet

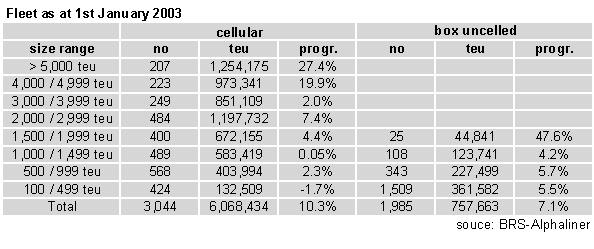
The cellular fleet stood at 6,068,000 teu on 1st January 2003, shared between 3,044 ships. It has doubled during the past seven years, in teu terms, meaning that the average annual growth has been at roughly 10.5 %. In 2002, the growth reached 10.3 %.

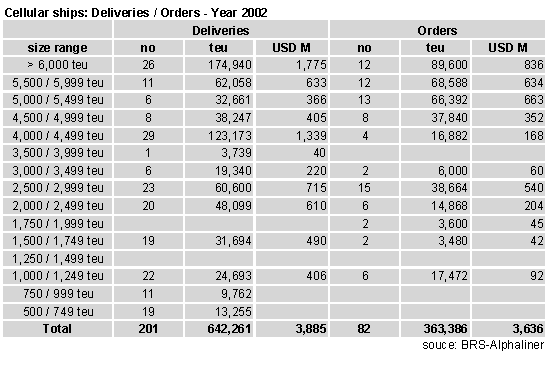
Two hundred and one cellular ships were delivered during the year 2002, for a total capacity of 642,261 teu. At the same time, 59 cellular ships were withdrawn for 74,001 teu, leaving a net fleet increase of 568,260 teu.

Eighty two cellular ships were ordered for 363,000 teu, Their cumulated value is estimated at $3.6 billion. It is a far cry from the year 2000, when 1,038,000 teu were ordered for a total value of $11.5 billion (some of them were however cancelled in 2002, especially in Polish yards).

In 2003 and 2004, the annual growth should reach a relatively modest 7.5 %, based on the current orderbook in January 2003 and taking into account a deletion rate of 50,000 teu per annum.

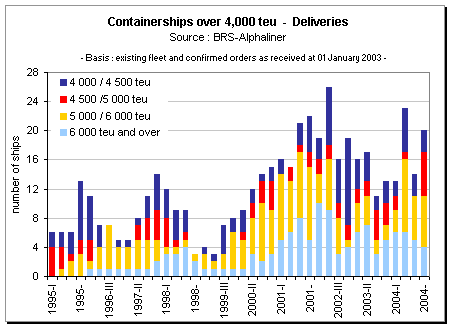
The largest ships in service remain the 19 'Sovereign' class series vessels of Maersk-SeaLand, the capacity of which stands at around 8,000 teu (although advertised at 6,600 teu by A.P. M'ller). Four of them were delivered in 2002. A.P. M'ller has six 'large' ships on order, for delivery in 2003-2004. Their size is undisclosed and it is only when the first ship will be delivered that their real capacity can be appreciated. Meanwhile, Seaspan has ordered five ships of 8,100 teu at Samsung on behalf of a long term charter by China Shipping Container Lines (CSCL).

There are currently 28 ships of more than 7,000 teu in service, including 25 units owned by A.P. M'ller and three by Hapag-Lloyd. There are 29 more on order : six for A.P. M'ller/Maersk-SeaLand, eight for OOCL, five for Seaspan/CSCL, five for Rickmers Schiffahrts/Cosco, four for P&O Nedlloyd and the remaining ship for Hapag-Lloyd. German owners have engaged discussions with Hyundai for a series of ships of 8,450 teu.

With the exception of the six Maersk-SeaLand newbuildings, for which nothing is known, all the 7,000+ teu ships offer a breadth of 42,80 m, allowing the stowage on deck of 17 rows of boxes. This is no coincidence : most of the large terminals are fitted with gantry cranes with a 17-row or 18-row reach.

As for the six Maersk-SeaLand newbuildings for delivery this year and next, a breadth of 55 or 56 meters cannot be ruled out. It corresponds to 22 rows on deck, in line with the gantry cranes in which Maersk-SeaLand invested so much over the past three years for its own terminals. One can reasonably speculate that such an investment will be matched with the construction of adequate ships. That means the 10,000 teu barrier could be broken.


The containership second-hand market in 2002


2002 as a vintage was relatively modest but nonetheless respectable concerning the second-hand market activity, with some 135 containerships sold for a combined value of $ 1.56 billion. The relative weakness of the market can be explained for the most part by the quasi-non-existence of the German market (except the numerous orders of new ships), preoccupied by placing the 150 ships already in her portfolio with local independent investors. On the other hand, this year can be viewed as one of consolidation after several seasons rich in mergers and acquisitions.

The breakdown of the sales in 2002 quite accurately reflects the proportions of the existing fleet with 13 ships over 3,000 teu (of which 5 over 4,000 teu) sold, 30 ships between 2,000 and 3,000 teu, 50 ships 1,000 and 2,000 teu and 42 ships under 1,000 teu.

There were relatively few massive 'en bloc' sales this year, with the exception of the 11 ships built in 1995-1996 of 650 teu for Elite Shipping sold to the Danish operator Clipper for a global price of $ 110 million, and the 4 ships of 3,500 teu built in 1993-1994 of L+B sold to MSC following a bareboat charter for about $ 20.7 million each.

The Greek owner Technomar was extremely active this year with 5 ships bought in 2002 to bring his total to 13 (of which 4 GX-class, 4 G-class and 4 L-class) bought from Evergreen on a time charter back for 5 to 7 years.

The small number of ships scrapped this year is worth noting, 59 ships with a total containership capacity of 74,001 teu roughly 1 % of the world capacity. This phenomenon can largely be explained by a freight market, which on average was rising steadily throughout the year.

A large majority of business contracted in 2002 was combined with charter employments (longer or shorter depending on investment sizes) to the liner operators, which has now become a recurring feature in this sector's activity.

As to price variations over the year, it can be summarised by a rising curve, which saw all sectors appreciate by some 10 to 20 % compared to 2001. Naturally this trend is more or less pronounced according to the various type and size of ships. As to be expected the sale prices follow the tendency of the market, with immediate effect in the case of a jump in daily rates (which happened this year), whereas prices are bolstered up for a longer period in the case of falling freight rates. Consequently although we have seen rates drop as from November 2002 after the prolonged strike in ports which blocked a large number of ships on the U.S. West Coast, ship prices have nonetheless remained fairly stable over the last two months.
 

Ships under 1,000 teu

As usual with this size, buyers are fairly heterogeneous. Given their poor profit-earning capacity in terms of pure investment, it is rarely speculators but rather pure liner operators who buy these ships. The market price has remained very steady. The improvement in rates has helped reassure buyers as to the high prices being sought by sellers. It is in these conditions that we have seen the following:

  • 'Flemming Sif', 'Kathrin Sif' 9,750 dwt, 972 teu, 1990 Orskov, change hands at around $ 8.7 million each.
  • 'Green Breeze', 'Green Better' and 'Green Bridge', 512 teu, 1984 Hakodate, sold to Bangladesh buyers at around $ 2.5 million each.
  • 'Xin Hai Yi', 9,734 dwt, 612 teu, 1985 Japan, sold for $ 3 million in September 2002 to Chinese buyers.

Ships of 1,000 to 2,000 teu

The market took advantage of a favourable upsurge after having slumped in the doldrums during the course of 2001. A large number of ships on order which can take the place of sold units have been delivered or are on the point of being so. Sales have for the most part benefited from time charters back, covering the interim period up until the delivery of new ships awaited by the sellers. We can note for example :

  • 'Sagittarius' 23,051 dwt, 2001 Szczecinska, 1,730 teu, 20 knots on 50.5 t, sold by Costa Container Lines for $ 22 million in September to Lipsi Navigation.
  • 'Mapocho' 21,184 dwt, 1999 Hanjin, 1,620 teu, sold to CSAV for $ 17.4 million in September.
  • 'Iyo', 24,370 dwt, 1995 Shin Kurushima, 1,613 teu, 20 knots on 53 t, sold by Fair Wind Navigation to Tsakos for $ 13.3 million in December 2002.
  • 'Box Wave', 'Gallant Wave', 24,083 dwt, 1995 and 1996, Shin Kurushima, 1,510 teu, 19 knots on 45 t, sold in August to clients of Teo Shipping for $ 14 million each with a charter-party attached for 18 months at $ 8,000 per day.
  • 'Kuo Lih', 18,050 dwt, 1995 Imabari, 1,471 teu, 17 knots on 31 t, sold in May to clients of Vroon for about $ 9.7 million, with a charter-party attached for 12 months at a level of $ 7,500 per day.
  • 'Lisboa', 'Tavira' and 'Miden Agan', 21,370 dwt, 1982 Warnowwerft, 1,438 teu, 19 knots on 62 t, sold in October by Sarlis Container Line for about $ 3 million each.

Ships of 2,000 to 3,000 teu

One can detect a certain hesitancy on the part of buyers in this market as the future does not have the backing of a fair number of operators. Some fear that the units of 2,500 teu will be replaced sooner or later by ships carrying more than 3,000 containers. This point of view is supported by an orderbook which carries relatively few ships of this size. It is true that 1999, 2000, and 2001 produced a large number of units between 2,000 and 2,800 teu. Operators have consequently been prudent, in concluding several operations mainly secured against firm employment:

  • 'P&O Nedlloyd Xiamen', 'Oriental Bay' and 'Grand Vision', 44,006 dwt, 59,285 dwt and 44,005 dwt, built in 1991, 1989, and 1991 at Daewoo, with a capacity of 2,797, 4,206, and 2,986 teu were sold en bloc on subjects to clients of Zodiac for $ 61 million.
  • 'MOL Victory' and 'MOL Independence', 40,638 dwt and 38,014 dwt, 1988 and 1986 Imabari, 2,890 and 2,571 teu, 22 knots, sold en bloc in October by Karakoram Maritima to clients of Danaos for $ 24 million.
  • 'MSC Europe', 45,647 dwt, 1986 Tsuneishi, 2,875 teu, 22.5 knots on 89.5 t, sold in June by Acasia Shipping to clients of Danaos for $ 12 million.
  • 'LT Glory', 'LT Grand', 'LT Globe', 43,310 dwt, 1984 Onomichi, 2,728 teu, 20.5 knots on 74 t, sold en bloc in December by Everglory Line to clients of Technomar for $ 13 million each with a charter-party attached for 5 years at a rate of $ 12,500 per day.
  • 'CMA CGM Claudel', 34,622 dwt, 2002 STX, 2,602 teu, sold by Efshipping to Schulte Group for $ 33.85 million, including a transfer of the charter-party to CMA CGM until February 2007 at $ 16,600 per day.
  • 'Christine Schulte', 33,871 dwt, 2001 Hyundai, 2,550 teu, sold in December by B. Schulte to German investors for $ 33.5 million, including a transfer a 4-year charter-party to CSAV at $ 16,750 per day.
  • 'Ambassador Bridge', 45,643 dwt, 1986 Tsuneishi, 2,518 teu, 22.5 knots on 89.5 t, sold in May to clients of Danaos for $ 11 million with a 18 to 24 month charter-party at $ 12,000 per day.

Ships over 3 000 teu

Only 13 sales were achieved out of more than 600 ships existing in this category. None or very few sellers showed themselves. The market was extremely nervous on the selling side, with owners reluctant to sell for fear of not finding a replacement unit and this, even if the sale prices were attractive. Consequently outside of the 'straight' purchase by MSC of 4 ships from L+B, already under charter to them, the others sales were all undertaken by operators / investors against charters back. These operations are more and more sought after not only by the traditional German investors, but also by owners such as Zodiac, Technomar, Danaos, Costamare'

  • 'CMA CGM Normandie', 59,600 dwt, 1991 Samsung, 4,734 teu, 24 knots on 158 t sold in September by CMA CGM to clients of Zodiac for $ 31 million with a 3-year charter back at $ 21,775 per day.
  • 'MSC Sarah', 'MSC Ingrid', and 'MSC Matilde', 67,795 dwt, 2000 Samsung, 4,400 teu, 25 knots, sold in March to Swiss buyers for $ 40 million each and fixed for a long period with MSC.
  • 'Peloponesian Pride', 53,240 dwt, 1986 Onomichi, 3,428 teu, 21 knots on 74.5 t, sold in August by Evergreen Marine to clients of Technomar for $ 21 million with a 7-year charter back at $ 15,500 per day.
  • 'MSC Martina', 'MSC Sophie', 'MSC Monica' and 'MSC Rossela', 43,600 dwt, 1993, 1994, 1993 and 1994 at Samsung, 3,424 teu, 22.5 knots on 99 t, sold in February by Hansa Asia to MSC for $ 20.7 each, subjects lifted following a bareboat charter with purchase option on the 4 ships.

* * *

Nearly all analysts at the end of 2001 were predicting a vintage 2002 somewhat depressed and a declining market. Once again as in 2000, the containership market surprised everybody. In a stagnant world economy, shipping lines were able to re-distribute the cards to be able to offer a service tailor-made to the situation. The specificity of containers allows such flexibility. It is also this adaptability that reassures investors, who have found a means of investment which insures regularity, safety (very few accidents), flexibility to market changes and - the icing on the cake - tax relief.

At the time of writing, good news has been announced in France regarding the introduction of 'tonnage tax' system. We can only hope that this tax incentive is as open and accessible as it has been in Germany, which thanks to this opening, has experienced the shipping activity that we all know.
 

›››Archivo
DESDE LA PRIMERA PÁGINA
En el tercer trimestre, el tráfico marítimo en el Canal de Panamá se mantuvo estable.
Panamá/Balboa
Sin embargo, el tonelaje de los buques y el volumen de mercancías en tránsito están aumentando.
El sistema marítimo de comercio de derechos de emisión (ETS) y FEPORT apoyan las medidas contra la evasión fiscal relacionadas con la carga.
Bruselas
Es la solución más eficaz —afirma la federación de operadores de terminales europeos— para proteger la competitividad de los puertos de la UE.
COSCO Shipping, ingresos +29% y beneficios +82%: el mérito se debe a las tarifas de flete, más que a los volúmenes.
Hong Kong
El mercado transpacífico es el motor que impulsa las cuentas del grupo chino.
Norwegian Cruise Line Holdings registra un aumento en sus ingresos netos, pero una disminución en sus márgenes durante el tercer trimestre.
Miami
APM Terminals firma una nueva fase de expansión para el puerto marroquí de Tánger Med.
Rabat
Se prevé una inversión de más de 800 millones de dólares para construir 1,2 kilómetros de muelles.
El puerto de Barcelona lanza un proyecto para reducir las terminales de cruceros de siete a cinco.
Barcelona
Revisión de la concesión de Creuers del Port de Barcelona
Boluda y Samskip, una nueva fusión en el transporte marítimo de corta distancia europeo.
Valencia/Róterdam
El grupo español ha firmado un acuerdo para adquirir todas las actividades del grupo holandés y ampliar su plataforma multimodal.
Astilleros indios en la lista de reciclaje de buques de la UE, ECSA pide a los eurodiputados que la aprueben.
Bruselas
Llamamiento para rechazar una moción que se opone a la propuesta de la Comisión.
CVC DIF ha adquirido una participación mayoritaria en el astillero español Cernaval.
Schiphol
La empresa ibérica emplea aproximadamente a 275 personas.
Contship Italia adquiere el grupo Tarros.
Melzo/La Spezia
Todas las actividades y activos que conforman el sistema de servicios integrados del grupo La Spezia cambian de manos.
El crucero residencial de Villa Vie Residences fue suspendido.
Fort Lauderdale/Sihanoukville
La compañía atribuye el encallamiento del buque al aumento del precio del combustible y está trabajando en un plan de reestructuración y recapitalización.
Wallenius Wilhelmsen encarga cuatro PCTC de 9.900 CEU más ocho opciones.
Lysaker
Acuerdo con el astillero chino Jinling Shipyard (Jiangsu)
Royal Caribbean registra ingresos trimestrales récord de 5.590 millones de dólares. Se revisan al alza las previsiones para el año completo 2026.
Miami
EBITDA de 2.530 millones y 2,68 millones de pasajeros en el período julio-septiembre
La seguridad marítima, el sistema de transporte de emisiones (ETS), los pabellones y el empleo son los temas centrales del informe del presidente de Confitarma.
Roma
Zanetti aboga por una alianza europea para la libertad de navegación, un pacto nacional para la transición y menos burocracia para la bandera italiana.
Global Ports Holding firma un acuerdo de concesión para el puerto de cruceros de San Vicente.
Estanbul
El acuerdo tiene una duración de 30 años.
La familia Sunde vende Color Line a Stena.
Gotemburgo
Un grupo sueco de ferris adquiere la mayor compañía de ferris de cruceros de Noruega.
Puertos chinos, la carrera se está ralentizando.
Pekín
Tras 25 años de crecimiento, el tráfico de mercancías está prácticamente paralizado, pero los contenedores siguen batiendo récords.
Lorenzo Sanna es el nuevo presidente de ANPAN
Sestri Levante
Parmigiani: En lo que respecta al Protocolo de Alta Mar, deberíamos retomar la declaración escrita del comandante.
2027 volverá a ser un año récord para la industria italiana de cruceros.
Livorno
Se prevé la llegada de aproximadamente 16 millones de pasajeros, con un crecimiento del +4%.
Reforma portuaria: la Comisión debate la posibilidad de reservar y rechazar únicamente buques.
Roma
La Cámara de Diputados no ha aprobado ninguna enmienda en tres semanas. La única excepción es el personal de la Autoridad Portuaria.
Transporte por carretera, tregua inminente. El gobierno libera fondos para combustible diésel y reformas estructurales.
Roma
Se aprueba un decreto de emergencia con créditos fiscales, prohibición de arrendamiento y protección contra el recargo por combustible.
La flota de portacontenedores y buques de transporte de automóviles de combustible dual supera las 500 unidades.
Washington
Un incremento del 41% en comparación con septiembre de 2025. Las inversiones del sector han superado los 200.000 millones de dólares.
Corredores marítimos verdes: China lidera la carrera.
Llevar a la fuerza
Casi una quinta parte de los proyectos de desarrollo a nivel mundial involucran un puerto chino. El informe del Foro Marítimo Global destaca el combustible y la colaboración como puntos fuertes, mientras que la demanda sigue siendo débil.
En el tercer trimestre, el tráfico de mercancías en los puertos españoles creció un +2,1%.
Madrid
La carga a granel está marcando la tendencia. La carga en contenedores se mantiene estable.
La UE invierte en la revolución verde de los mares.
Bruselas
Desde el amoníaco hasta el e-metanol, desde los transbordadores eléctricos hasta la captura de CO2: proyectos que están transformando el futuro del transporte marítimo europeo han recibido financiación.
Las asociaciones de transporte por carretera piden que se ponga fin a los bloqueos de carreteras en el sur del país.
Roma/Módena
Tras la reunión con Salvini, los sindicatos instaron a Piantedosi a intervenir. Ruote Libere respondió: escuche a los manifestantes, no los reprima.
APM Terminals y Hateco firman un acuerdo para desarrollar una red de terminales de carga ferroviaria en el norte de Vietnam.
Copenhague
La inversión inicial se estima en alrededor de 3.500 millones de dólares.
IFM Investors adquirirá las participaciones de CPPIB y OMERS en Associated British Ports.
Londres
Se ha alcanzado un acuerdo para la transferencia del 63,9% del capital del grupo portuario británico.
Los sectores de transporte marítimo y aéreo, y logística contractual impulsan el tercer trimestre, mientras que el transporte por carretera se ralentiza.
Copenhague
La división de carreteras sufre problemas tras la integración de Schenker.
Descarbonización del transporte marítimo: El Reino Unido debería aprender de los errores de FuelEU Maritime.
Londres
La Cámara Naviera del Reino Unido presenta al gobierno un documento con las lecciones aprendidas de los dos primeros años de aplicación del reglamento europeo.
El puerto de Amberes-Brujas vuelve al crecimiento en el tercer trimestre, con un aumento del 2,5% tras dos trimestres de descenso.
Amberes
Los contenedores, el transporte ro-ro y el transporte de graneles secos están impulsando la recuperación, mientras que el acero y los productos energéticos siguen atravesando dificultades.
Interferry reitera su preocupación por el aplazamiento de la inclusión del transporte por carretera en el RCDE UE.
Victoria
Roos: Las cargas y los desafíos de la descarbonización no pueden ser asumidos por sectores individuales.
El puerto de Trieste se recupera en el tráfico de contenedores en el tercer trimestre, pero el ferrocarril sigue en dificultades.
Trieste
El volumen de líquidos está en aumento.
Tráfico récord de cruceros trimestral en las terminales de Global Ports Holding
Estanbul
Únicamente las cifras en la región del Mediterráneo oriental y el Adriático están disminuyendo.
Rheinmetall confirma su asociación con MSC para la adquisición del astillero rumano en Mangalia.
Düsseldorf
El precio de compra, de aproximadamente 138 millones de euros, será pagado conjuntamente por los dos socios.
Estrecho de Ormuz: Otro fin de semana de ataques a buques
Teherán/Southampton
Primer uso de un cohete antitanque RPG disparado desde una embarcación pequeña.
Puerto de Rotterdam: El tráfico de carga general disminuye en el tercer trimestre, mientras que el tráfico de carga a granel aumenta.
Róterdam
En los primeros nueve meses de 2026 se manipularon 323,2 millones de toneladas (+0,9%).
Nace el Observatorio de Construcción Naval de Liguria: un sector valorado en dos mil millones de euros y que emplea a más de 10.000 personas.
Génova
AdSP, Confindustria Genova y Unione Industriali Savona lanzan un seguimiento permanente del sector
La BPA afirma que el crecimiento del sector de contenedores en el Reino Unido depende de la inversión, no de las fugas de carbono.
Londres
Un informe de la asociación británica refuta al Observatorio Español: el indicador en teu-millas no mide volúmenes reales y amplifica el efecto del orden de los puertos de escala.
El sistema de comercio de emisiones (ETS, por sus siglas en inglés) representa el 10% de las emisiones, pero paga casi el 20% de la factura.
Bruselas
Estudio de ECSA: Los armadores europeos solicitan cuotas triples del SMAP para combustibles y tecnologías sostenibles.
AP Moller Capital adquirirá Portek International Port Group.
Copenhague
Será comercializado por la empresa japonesa Mitsui & Co.
La disputa portuaria entre Washington y Madrid amenaza con convertirse en una guerra comercial.
Washington
La FMC propone un gravamen de 200 mil dólares por viaje a los buques con bandera española y restricciones a la importación de ciertos productos.
Reforma portuaria: la Comisión rechaza los cambios en la gobernanza de Puertos de Italia.
Roma
Ayer, la Comisión de la Cámara de Diputados votó el artículo 9 del proyecto de ley 2925: las enmiendas de la oposición fueron rechazadas; su posterior examen se ha aplazado a otra sesión.
El puerto de Singapur establece un nuevo récord histórico de movimiento trimestral de contenedores (TEU).
Singapur
Las ventas de combustible marino ponen de manifiesto la continua transformación del mercado de combustibles.
Dos buques portacontenedores fueron alcanzados por proyectiles mientras transitaban por el estrecho de Ormuz.
Southampton/Singapur
El "GFS Pride" sufrió daños y un incendio a bordo, y posteriormente se hundió.
Ataques a barcos y puertos: el ETF hace un llamamiento a los líderes de la UE.
Bruselas
"Necesitamos acción, no otra declaración de preocupación": el sindicato exige que la seguridad de los trabajadores sea el eje central de la respuesta europea en el Mar Negro.
Según el tribunal de Génova, RINA es responsable del hundimiento del Al Salam Boccaccio '98 .
Génova
La empresa manifiesta su profundo desacuerdo y recuerda las conclusiones de otras investigaciones.
Perú planea un segundo puerto nacional importante
Archivo
El puerto de Corío se construirá en la costa sur del país para servir también a las exportaciones brasileñas.
Los ataques contra barcos en el estrecho de Ormuz y el mar Negro se están multiplicando.
Sofía/Southampton/Nueva Delhi
Dos embarcaciones resultaron heridas en la zona económica especial de Bulgaria.
Sistema de comercio de emisiones marítimo: El SMAP bajo escrutinio por parte de quienes producen los combustibles del futuro.
Bruselas
Una carta conjunta de productores, empresas de servicios públicos, armadores y ONG solicita la reserva de cuotas para combustibles sintéticos y la introducción de la reserva anticipada.
El puerto de Los Ángeles establece nuevos récords históricos de movimiento de contenedores, tanto mensuales como trimestrales.
Los Ángeles
Nuevos picos en contenedores llenos al desembarcar y cajas vacías
Rheinmetall adquiere el astillero de Mangalia por 138 millones de euros.
Bucarest
El proyecto está vinculado al relanzamiento de la industria naval rumana y a la construcción de cuatro unidades para la Armada.
Nace United Transport Mutual: barcos, puertos y logística bajo un mismo paraguas asegurador.
Londres
Los miembros del UK P&I Club y del TT Club aprueban la fusión, conservando los nombres, las marcas y los equipos.
En España, el transporte marítimo de corta distancia está en declive.
Madrid
La SPC España advierte que los costes de las regulaciones ambientales están alejando el tráfico marítimo del mar.
Puerto de Ravenna, agosto -20,5% y septiembre estimado -9%.
Rávena
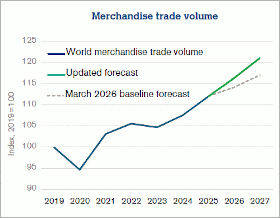
El comercio mundial es más resistente de lo esperado. La IA está impulsando el sector de bienes, mientras que el de servicios se está frenando.
Ginebra
La OMC revisa sus estimaciones: el crecimiento del comercio de bienes se sitúa en el 3,9% en 2026, y el de servicios en el 3,3%. Sin embargo, el impacto de la crisis de Oriente Medio no afecta por igual a todos.
Puertos europeos: la sostenibilidad entra en fase de implementación
Bruselas
De las políticas a los resultados: el informe de ESPO documenta en imágenes el progreso, los retrocesos y las prioridades del sector.
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
El gobierno federal alemán prohíbe la venta de Zippel al grupo chino COSCO.
Berlina
En febrero la autoridad antimonopolio lo había aprobado.
Informe de Fedespedi: Los puertos del norte del Adriático están creciendo, pero hablan esloveno y croata.
Milán
Assoporti representó la posición italiana sobre el RCDE UE en ESPO.
Roma
Petri: No a la aplicación indiscriminada de normas diseñadas para realidades territoriales profundamente diferentes.
DP World se asegura diez años más de gestión de la terminal multipropósito en el puerto de Luanda.
Dubái
Desde 2021, ha invertido más de 260 millones de dólares en ella.
El puerto de Nápoles, la Darsena di Levante - advierte Confindustria Napoli - ya no puede esperar
Nápoles
El nuevo tren lanzadera de Hupac entre Busto Arsizio/Gallarate y Barcelona
Ruido
El servicio, que tendrá una frecuencia de tres semanas, se inaugurará el 9 de noviembre.
Nuevo récord trimestral de tráfico de mercancías en los puertos albaneses.
Tirana
En el período julio-septiembre, el número de pasajeros disminuyó un -5,4%.
Los beneficios de FedEx están aumentando, pero el beneficio neto cae un 68%.
Memphis
La pérdida de capital no monetaria relacionada con la escisión de FedEx Freight pesa mucho
Kalmar registró un crecimiento del 22% en nuevos pedidos en el tercer trimestre.
Helsinki
Facturación estable. Beneficio neto un 14% inferior.
En el tercer trimestre, las ventas de contenedores producidos por CIMC aumentaron un 30%.
Hong Kong
La actividad comercial se vio impulsada por los contenedores secos (+36%). Las unidades refrigeradas disminuyeron un 28%.
Puertos, nuevas inversiones en Toscana y Cerdeña
Livorno/Cagliari
Se han aprobado los presupuestos para 2027 de las dos autoridades portuarias. Entre los proyectos más destacados se incluyen el muelle de Piombino, las obras en Livorno y los proyectos de dragado y electrificación en los puertos de Cerdeña.
Encontrar personal cualificado en los puertos italianos es cada vez más difícil.
Nápoles
Un análisis realizado por Randstad Research de 13 perfiles profesionales también pone de manifiesto un marcado desequilibrio de género.
COSCO Shipping Ports registra ingresos récord en el tercer trimestre.
Hong Kong
En el período de julio a septiembre, el beneficio neto fue de 102,5 millones de dólares (+3,4%).
Aprobación del presupuesto previsto para 2027 y del Plan Operativo de Transporte (POT) para el periodo 2027-2029 de la Autoridad Portuaria del Sur del Mar Tirreno y Jónico.
Gioia Tauro
El documento de previsiones muestra unos ingresos de aproximadamente 24 millones de euros y unos gastos de aproximadamente 88 millones.
Bongiovanni, natural de Ravenna, ha sido confirmado como presidente del Comité Juvenil de la Federación.
Roma
Renovación de la junta directiva de la federación
Se ha aprobado el Plan Operativo Trienal 2027-2029 para el Sistema Portuario del Adriático Central.
Ancona
Se prevén inversiones por valor de 308 millones de euros, de los cuales 218 millones se destinarán a la región de Las Marcas y 91 millones a Abruzzo.
Se ha aprobado el presupuesto previsto para 2027 de la Autoridad Portuaria de Liguria Occidental.
Génova
El nuevo recargo sobre los productos se pospone hasta 2028.
DP World inaugura un almacén con temperatura controlada cerca de Bolonia.
Bolonia
Superficie de 22 mil metros cuadrados
Saipem gana dos nuevos contratos de perforación en alta mar.
Milán
El valor total de los pedidos asciende a aproximadamente 121 millones de dólares.
Hanwha pone el astillero naval de Filadelfia bajo el control de la División de Defensa.
Arlington
El objetivo es integrar la construcción de buques comerciales y militares.
Los puertos de La Spezia y Carrara aprueban el Programa Trienal de Obras Públicas 2027-2029 y el Presupuesto 2027.
La Spezia
Pisano: PTLP concreto y coherente con los recursos actualmente disponibles.
Concesiones portuarias: El Tribunal Administrativo Regional (TAR) bloquea el aumento de tarifas de 2025.
Roma
Se ha aceptado el recurso presentado por Assiterminal y dieciséis empresas portuarias.
Wärtsilä registra aumentos trimestrales en los pedidos, pero no en el segmento marítimo.
Helsinki
En el periodo julio-septiembre la empresa registró un beneficio neto de 125 millones de euros (-31%).
Montaresi fue nombrado secretario general de la Autoridad Portuaria del Mar de Liguria Oriental por otros cuatro años.
La Spezia
Renovación del mandato a propuesta del Presidente Pisano
Doble ceremonia para dos barcos de Explora Journeys en el astillero Fincantieri en Génova.
Génova
Lanzamiento del "Explora V" y ceremonia de colocación de la primera moneda del "Explora VI".
La empresa italiana CMD pasa a estar bajo el control del grupo emiratí EDGE.
Abu Dabi/Roma
Los primos Mariano y Giorgio Negri conservan una participación significativa.
La Autoridad Portuaria del Tirreno Septentrional presenta el nuevo diseño del puerto de Piombino.
Livorno
Gariglio: Un paso concreto hacia la reconversión industrial y el futuro de Piombino.
FS Logistix ha adquirido seis nuevas locomotoras CZ LOKO para servicios de transporte de mercancías y maniobras.
Roma/Praga
Este es el cuarto pedido de este tipo que recibe la empresa checa en diez años.
Puerto de Bremerhaven: El crucero Mein Schiff 3 colisionó con dos buques portacontenedores.
Bremen
No hubo heridos. El crucero fue cancelado.
Paolo Moretti ha sido nombrado consejero delegado de RINA Spa.
Génova
Giosuè Vezzuto ha asumido el cargo de director ejecutivo de RINA Services.
HD Hyundai y Kiewit establecerán una empresa conjunta en un nuevo astillero en Estados Unidos.
Houston/Seúl
Está prevista la construcción de buques tanto militares como comerciales.
Los pedidos trimestrales de equipos portuarios de Konecranes disminuyen a medida que aumentan los ingresos.
Helsinki
El tercer trimestre de Kuehne+Nagel fue muy positivo.
Schindellegi
Crecimiento de los resultados económicos y operativos en todos los segmentos de negocio.
La apuesta de Wildcat por la defensa estadounidense: acuerdo exclusivo con el histórico astillero de Fraser.
Superior
El funcionamiento del fondo de Miami Beach forma parte del plan del gobierno para relanzar la industria naval estadounidense.
Puerto de Ancona: Se emite la primera autorización ZES individual.
Ancona
Se ha desbloqueado una inversión de tres millones de euros en la construcción de yates.
El acceso al puerto de Ravenna está autorizado para buques con un calado máximo de 11,00 metros.
Rávena
Benevolente: es un paso fundamental para el desarrollo económico y estratégico del aeropuerto.
El puerto de Génova extiende la autorización de inspección de alimentos a la terminal PSA SECH.
Génova
La disposición del Ministerio de Salud amplía las categorías de productos que pueden estar sujetos a control.
PROXIMAS SALIDAS
Visual Sailing List
Salida
Destinación:
- orden alfabético
- nación
- aréa geogràfica
El jueves, la Unione Interporti Riuniti presentará el proyecto ELODIE en la Cámara de Diputados.
Roma
El objetivo es crear una federación digital de interpuertos.
ABB registra pedidos récord por valor de 12.000 millones de dólares en el tercer trimestre.
Zúrich
Los ingresos y las ganancias también aumentaron, mientras que el grupo anunció una empresa conjunta con Mitsubishi Electric.
En el tercer trimestre de 2026, el volumen de contenedores en el puerto de Barcelona disminuyó un -9,2%.
Barcelona
El descenso se debió a una reducción del 19,9% en el tráfico de transbordo.
Las terminales de COSCO Shipping Ports establecen un nuevo récord trimestral de procesamiento de contenedores.
Hong Kong
En el período julio-septiembre también los volúmenes manejados por CMPort
En agosto, los puertos de Liguria Occidental gestionaron 5,2 millones de toneladas de mercancías (+1,6).
Génova
En Génova se registró un aumento del +6,1%, mientras que Savona-Vado Ligure sufrió un descenso del -10,0%.
Raben Italia abre un nuevo almacén en Pomezia.
Milán
El objetivo es consolidar el posicionamiento y la expansión territorial en el transporte por carretera.
El puerto de La Spezia firma un acuerdo para desarrollar proyectos de economía azul y seguridad.
La Spezia
Fue firmado por la AdSP y la Fundación del Centro Nacional de la Dimensión Subacuática.
El puerto de Long Beach celebra un nuevo récord mensual de movimiento de contenedores.
Playa larga
Nuevo máximo histórico también en el trimestre de julio a septiembre.
Se ha abierto la licitación para la demolición parcial del muelle norte del puerto de Ancona.
Ancona
La intervención incluye la regularización de los fondos marinos correspondientes.
HMM invierte más de 1.600 millones de dólares en 12 nuevos buques portacontenedores.
Busan
Para 2029, se entregarán ocho buques de 13.000 TEU, tres buques de 2.800 TEU y un buque de 1.700 TEU.
Paolo Pessina confirmado como presidente de Federagenti
Roma
Votación unánime de la asamblea de la Federación
Han comenzado las negociaciones para renovar el convenio colectivo único del sector naviero.
Roma
Las partes han acordado un intenso calendario de reuniones.
El tráfico de contenedores en el puerto de Hong Kong creció un 15,1% en el tercer trimestre.
Hong Kong
En septiembre el aumento fue del +25,0%.
Formación marítima: Apelación ante el Tribunal Administrativo Regional (TAR) contra el aumento de tarifas de la Autoridad Portuaria.
Roma
ANIFORMAR, CONFORMAR y 15 centros de formación desafían el decreto del MIT-MEF: los aumentos alcanzan hasta el 149,3%.
El Grupo Spinelli ha inaugurado un nuevo depósito de contenedores vacíos en Novi Ligure.
Génova
Inversión por valor de 14 millones de euros.
Rhenus integra sus servicios logísticos en un único centro logístico en el Interporto de Padua.
Padua
El complejo reunirá transporte por carretera, transporte aéreo y marítimo, almacenamiento y servicios especializados.
Un camionero fallece en el puerto del canal de Cagliari.
Cagliari
Habría quedado aplastado por una carga de tuberías grandes.
Confitarma, empresa dedicada al sector marítimo, está preocupada por la incertidumbre que surge de la interpretación que hace la Agencia Tributaria.
Mitsubishi Heavy Industries planea ampliar su capacidad de construcción naval.
Tokio
La empresa planea invertir 100 mil millones de yenes.
Trasportounito: El gobierno está loco si piensa que la crisis del transporte por carretera se puede resolver por sí solo.
Roma
Se insta a la aplicación de la cláusula de ajuste del costo del diésel.
Emanuele Grimaldi es el nuevo presidente de la Asociación Internacional de Armadores de Malta.
La Valeta
Sucede en el cargo a Marily Frangista, quien ha estado al frente de la asociación desde abril de 2022.
La cuarta edición de la Green Logics Expo arranca mañana por la mañana en Padua.
Padua
Contará con la participación de más de 300 expositores y la celebración de 30 eventos de conferencias.
En el tercer trimestre de este año, el tráfico de mercancías en los puertos turcos disminuyó un -1,1%.
Ankara
Los volúmenes de tráfico desde y hacia Italia crecieron un +6,2%.
En Assiterminal, la flexibilidad de los PRP debe tener en cuenta el mercado relevante en el que operan los puertos.
Génova
Cetus Maritime planea cotizar en la bolsa de valores Euronext Growth Oslo.
Hong Kong
Adquisición de 16 buques en preparación para su cotización en bolsa.
El sábado, un avión estadounidense impactó contra un buque granelero en el Golfo de Omán.
Tampa
Centcom: El barco había intentado imponer un bloqueo naval contra Irán.
PUERTOS
Puertos italianos:
Ancona Génova Rávena
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Liorna Taranto
Cagliari Nápoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venecia
Interpuertos Italianos: lista Puertos del mundo: Mapa
BANCO DE DATOS
Armadores Reparadores navales y astilleros
Expedicionarios Abastecedores de bordo
Agencias marítimas Transportistas
MEETINGS
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
El jueves, la Unione Interporti Riuniti presentará el proyecto ELODIE en la Cámara de Diputados.
Roma
El objetivo es crear una federación digital de interpuertos.
››› Archivo
RESEÑA DE LA PRENSA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Reseña de la Prensa Archivo
FORUM de lo shipping y
de la logística
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› Archivo
Buque impactado cerca del estrecho de Ormuz
Southampton
Una bala provocó un incendio que posteriormente fue extinguido.
OOCL informa un crecimiento del 9,0% en los volúmenes transportados por buques en el tercer trimestre.
Hong Kong
El aumento del valor de las tarifas de flete marítimo provoca un incremento del +45,1% en los ingresos.
HD Hyundai Marine Solutions adquirirá la empresa estadounidense Goltens Worldwide.
Dubái/Seongnam
La empresa se dedica a la reparación y el mantenimiento de grandes motores marinos y maquinaria industrial.
UNATRAS al gobierno: Desbloquee de inmediato las medidas para reducir los precios del diésel.
Roma
Las asociaciones de transporte por carretera denuncian retrasos e incertidumbres en la aplicación del acuerdo del 22 de mayo y solicitan una reunión urgente.
Puerto de Taranto: Gugliotti reitera su solicitud al gobierno de financiación para el parque eólico del puerto.
Taranto
El proyecto —subrayó— no puede ni reducirse ni posponerse.
Ataque a un barco en medio del Golfo Pérsico.
Southampton
La UKMTO informó que varios proyectiles causaron bajas entre los miembros de la tripulación.
Gioia Tauro: Se aprueba la adenda al Plan Portuario actualizado.
Gioia Tauro
Este análisis nos permitirá evaluar las necesidades de personal y de contratación de la Agencia Portuaria.
Barcos haciendo cola, combustible desperdiciado: cómo esperar fondeado puede ahorrarle dinero.
Copenhague
El Foro Marítimo Global publica los resultados de las pruebas realizadas por Cargill en 16 viajes reales. Reducir la velocidad y llegar cuando el muelle está libre disminuye el consumo de combustible y las emisiones.
ZIM eleva sus previsiones para todo el año 2026.
Haifa
Se espera que el EBITDA ajustado y el EBIT sean de 2.700 millones de dólares/3.000 millones de dólares y de 1.400 millones de dólares/1.700 millones de dólares.
Gabriele Sangiorgi ha sido nombrado secretario general interino de la Autoridad Portuaria de Rávena.
Rávena
El mandato de Fabio Maletti ha expirado.
Puerto de Génova: Los trabajadores de la terminal de Messina se declaran en huelga durante una hora por un mes.
Génova
La empresa informa que uno de los miembros del sindicato no se presentó a la última reunión, en cumplimiento del procedimiento de reflexión previsto en el Convenio Colectivo Nacional.
Puerto de Taranto, acuerdo para participar en el desarrollo del Valbasento Interporto en Ferrandina.
Matera/Taranto
Se elaborará un plan maestro logístico-funcional en un plazo de 180 días.
En Ática, el déficit se reduce principalmente gracias a las ganancias de capital y la cobertura.
Kallithea
Primer semestre del año con menos cruces y un ligero aumento de los ingresos.
Desde principios de año, el número de pasajeros y mercancías en los buques de GNV ha aumentado un +2% y un +5%, respectivamente.
Marrakech
Asociación estratégica de tres años con la Oficina Nacional Marroquí de Turismo.
Filt Cgil reconoce que el trabajo marítimo y portuario es arduo.
Roma
El sindicato exige que se incluya una disposición clara al respecto en la próxima ley de presupuestos.
Escola Europea - Transporte Intermodal celebra su 20 aniversario
Barcelona
Un viaje por el Mediterráneo entre Barcelona, Civitavecchia, Palermo y Génova.
Un petrolero fue atacado en el estrecho de Ormuz.
Southampton
La unidad continuó su navegación con normalidad.
FS Logistix e Interporto Bologna presentaron el primer tren experimental italiano con convertidor de amplitud directa (DAC).
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
Sanilog lanza una campaña especial de prevención del cáncer.
Roma
Tres nuevas áreas dedicadas a la prevención de cánceres de cabeza y cuello y de cavidad oral y a la evaluación del riesgo vascular.
Se ha adjudicado el contrato para el dragado y la finalización de la electrificación de los muelles del puerto de Gioia Tauro.
Gioia Tauro
Serán llevadas a cabo respectivamente por Dravo y RTI Saet-Suardi.
Premio de estudiante de arquitectura naval otorgado en Génova
Génova
El Grupo d'Amico y la Real Institución de Arquitectos Navales reconocen la excelencia en la ingeniería naval.
El transporte de mercancías resulta más caro para Malta: 35 millones de euros al año entre ETS, FuelEU y BAF.
Zebbug
La asociación de transportistas insta al gobierno a cuestionar una política europea diseñada para el continente.
CMA CGM ha finalizado la adquisición de FedEx Supply Chain.
Marsella/Atlanta
Con esta transacción, la presencia de CEVA Logistics en Norteamérica se ha triplicado.
- Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA
tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Director: Bruno Bellio
Prohibida la reproducción, total o parcial, sin el explicito consentimento del editor
Búsqueda en inforMARE Presentación
Feed RSS Espacios publicitarios

inforMARE en Pdf
Móvil