testata inforMARE
Cerca
17 de octubre de 2026 - Año XXX
Periódico independiente sobre economía y política de transporte
23:31 GMT+2
LinkedInXFacebook
FORUM de lo shipping y
de la logística

April 2000


DEVELOPING COUNTRIES' MERCHANDISE EXPORTS IN 1999 EXPANDED BY 8.5% -
ABOUT TWICE AS FAST AS THE GLOBAL AVERAGE

Developing countries' merchandise exports in 1999 expanded by 8.5 per cent or about two times faster than the global average. Throughout the 1990s, developing countries' exports rose faster than world trade, with the exception of 1998. In 1999, the share of developing countries was 27.5 per cent for merchandise exports and 23 per cent for commercial services exports, both being more than 4 percentage points higher than in 1990.

Among the least-developed countries, merchandise export growth differed sharply again in 1999. Exporters of manufactured goods like Bangladesh, Cambodia and Haiti expanded their exports faster than world trade. Oil exporters, such as Angola and Yemen, benefitted from the oil price hike and increased their exports by more than one third. While, non-fuel commodity exporters, faced with declining commodity prices, tended to record lower export values.

Global commercial services trade accelerated only slightly in 1999, as the recovery in Asia and higher growth in North America were partly offset by lower growth in Western Europe and an import contraction in Latin America and the transition economies.

These are among the findings of the WTO's preliminary report on trade developments in 1999 and the outlook for this year (full report is attached). Other highlights include the following:

  • Global output and trade strengthened considerably in the second half of 1999, thereby improving the prospects for higher growth in the current year. The recovery in Asia and continued high demand growth in North America contributed most to global trade expansion last year.

  • World commodity output in 1999 increased by 1.5 per cent, the same as in 1998. A fall in mining sector output (in particular oil) contrasted with stronger growth in the manufacturing sector (e.g. electronic goods and automobiles). The global output of services industries exceeded commodity output growth. World GDP growth increased from 2 in 1998 to 3 per cent in 1999.

  • Trade benefitted from the stronger economic activity. Although for the year as a whole merchandise trade expanded in volume terms at the same rate as in 1998 (4.5 per cent), the pace of the expansion in the fourth quarter exceeded the average rate of 6.5 per cent recorded in the nineties.

  • International capital markets remained buoyant. Global FDI flows surged to a new record level of 800 billion dollars, driven by an exceptionally large value of cross border mergers and acquisitions. The sharp rise in global capital flows was largely concentrated among developed countries. Private net capital flows to emerging markets are estimated to have stagnated in 1999 at about 150 billion dollars.

  • Nominal and real effective exchange rates recorded major variations, leaving their mark on trade flows. While the euro and most European currencies weakened vis-à-vis the US dollar, many East Asian currencies, in particular the Japanese yen, the Korean won and the Thai baht, appreciated markedly.

  • Average prices of internationally traded goods declined slightly. The weakness of the Euro contributed largely to the fall in Western Europe's dollar export prices and a decrease in the prices of manufactured goods. Non-fuel commodity prices continued to weaken further, thus affecting the earnings of many raw material exporters. Oil prices, which had fallen sharply in 1998, recovered strongly in 1999 due to a cutback in oil output and an increase in global demand.

  • World merchandise trade value increased by 3.5 per cent in 1999, faster than commercial services trade. Nevertheless for the 1990-99 period as a whole, commercial services trade still expanded slightly faster than merchandise trade.

  • Thanks to oil price developments, the highest export value growth of all regions in 1999 was recorded in the Middle East and Africa. However, this strong expansion last year did not fully offset the declines recorded in 1998.

  • Merchandise imports grew at double-digit rates in North America and Asia, stagnated in Western Europe and Africa and decreased by about 10 per cent in the transition economies and in Latin America (excluding Mexico).

  • Merchandise export growth among the LDCs differed sharply again in 1999. Oil exporters such as Angola and Yemen benefitted from the oil price hike and increased their exports by more than one-third. Exporters of manufactured goods like Bangladesh, Cambodia, Haiti and Myanmar expanded their exports faster than world trade. Non-fuel commodity exporters faced with declining commodity prices tended to record lower export values.

  • Developing countries' merchandise exports expanded by 8.5 per cent or about two times faster than the global average. Throughout the 1990s developing countries' exports rose faster than world trade, with the exception of 1998. In 1999, the share of developing countries was 27.5 per cent for merchandise exports and 23 per cent for commercial services exports, both being more than 4 percentage points higher than in 1990.

  • Commercial services trade accelerated only slightly in 1999, as the recovery in Asia and higher growth in North America were partly offset by lower growth in Western Europe, and an import contraction in Latin America and the transition economies.


WORLD TRADE DEVELOPMENTS

Main Features

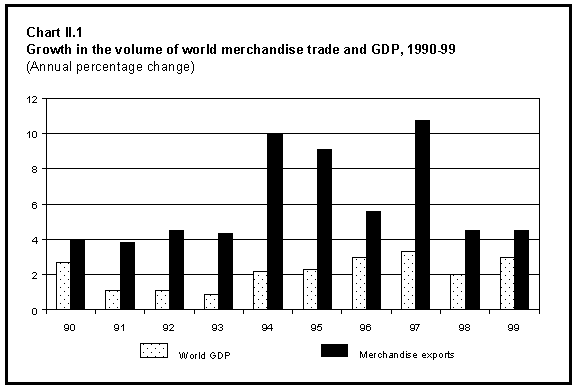
A strengthening of world economic output in 1999 reversed the slowdown of world trade in the first half of 1999 and led to a dynamic expansion of trade in the second half. For the year as a whole, the real growth of world trade remained unchanged from the preceding year and was below the average trade expansion recorded throughout the 1990s. Although trade growth continued to exceed both the growth in world commodity output and world GDP, the excess margin between the growth rates remained smaller in 1999 than those observed during the 1990-1997 period.


Demand in the United States and the Asian recovery were the motors of the global trade expansion in 1999. The outstanding strength of United States investment and private consumption benefitted not only the NAFTA region, but also sustained the recovery in Asia and to a lesser extent output in Western Europe. A major factor behind the excellent performance of the United States economy and the unprecedented length of the current expansion has been the high level of investment in information technology, the backbone of the "new economy". Excitement about the growth potential of the new economy has attracted large capital inflows and contributed to an extraordinary boom in the creation and valuation of high-tech companies. While the high rate of investment has increased production capacity and stimulated productivity growth of the United States economy, the question arises for how long high output and demand growth can be sustained without leading to inflationary pressures. A further risk to the strong economic expansion in the United States could arise from the widening of the current account deficit, which points to the increasing role of foreign savings in sustaining United States demand growth. An erosion of investor confidence in the outlook for the United States economy could lead to lower capital inflows and trigger a correction in the dollar rate and the stock markets.

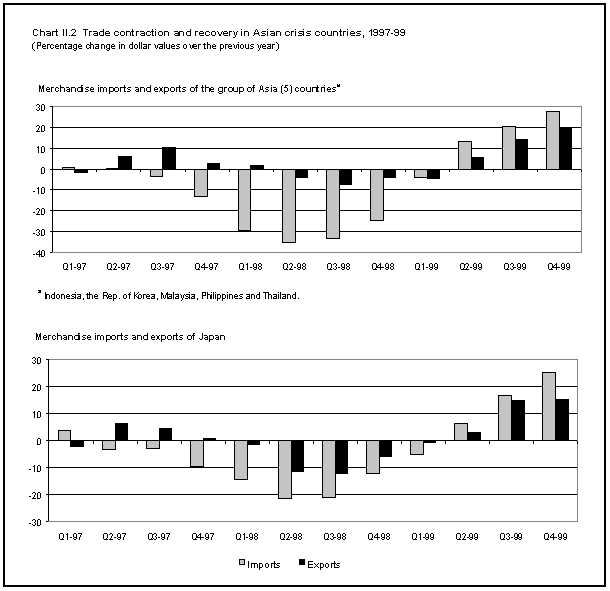
The recovery in Asia was stronger than expected and led to double-digit real import growth in 1999. GDP growth was uneven among the economies in the region, ranging from 11 per cent in the case of the Republic of Korea to stagnation in the case of Indonesia. In many countries economic growth was sustained by fiscal stimulus, replenishment of inventories and a rebound in the global demand for electronic goods.


The information technology sector and the automobile industry both recorded strong global output growth. Within the information technology sector, the unit sales of personal computers rose by 22 per cent to 114 million units, and the dollar value of global sales of semi-conductors expanded by 18 per cent, to a new record level of 160 billion dollars. One of the most dynamic branches of the global information technology industry in 1999 was mobile phones. It is estimated that world-wide sales of cellular mobile phones reached 283 million units, an increase of two-thirds over 1998 sales. New registrations of passenger cars are estimated to have expanded by 5.5 per cent, lifting the production of passenger cars to a new all time high of 48.6 million units in 1999. Although trade data by product group are still incomplete, there is no doubt that exports of automotive products and of office and telecom equipment have expanded significantly faster than the global average.

Developments in world financial markets continued to influence global trade developments through shifts in the direction of international capital flows and their impact on exchange rate changes. Global FDI flows have surged by about 25 per cent, to some 800 billion dollars. FDI inflows in Asia stagnated or rose only marginally, while the United States recorded net FDI inflows of 130 billion dollars. The main factor behind the increase in global FDI flows was the exceptional wave of cross-border mergers and acquisitions.

While the United States attracted an unprecedented level of capital inflows, which financed its widening current account deficit, net private capital flows to the major emerging markets are estimated to have stagnated at 150 billion dollars in 1999.

The increase in the United States current account deficit caused by increased imports can be seen as a positive cyclical element in the world economy as it allows output and employment to be sustained in foreign export industries facing excess capacity. At the same time, the deficit eases inflationary pressures in the United States where labour and productive capital are increasingly scarce. However, what is beneficial in a certain cyclical situation might be difficult to sustain in the medium term.

In particular, a large current account surplus of the developing countries vis-à-vis the United States (or any other high income country) is hardly a desirable feature over a longer period. Why is this so when most governments seem to favour a current account surplus over a deficit? A current account surplus implies that net capital (= savings) from the developing countries flows to other countries where it supports investment and/or consumption. A more desirable situation for the developing countries is a current account deficit (and a rising trade volume), and a concurrent inflow of capital that is used to enlarge (profitable) production capacity. If the capital inflow is used primarily for consumption, increased debt and debt servicing costs are unlikely to be sustainable.

The present large net capital inflows into the United States reflect, on the one hand, that foreign investors expect investment returns to be higher in the United States than elsewhere, and on the other, that United States consumers are spending an historically high share of current income (encouraged by its increased financial wealth), while United States companies maintain a high level of capital spending. A reversal in foreign investors' appreciation of future earnings in the United States or a cutback in United States consumption or investment growth could rapidly change the size of the United States current account deficit, which in 1999 was equivalent to 3.7 per cent of GDP - a historic record level.

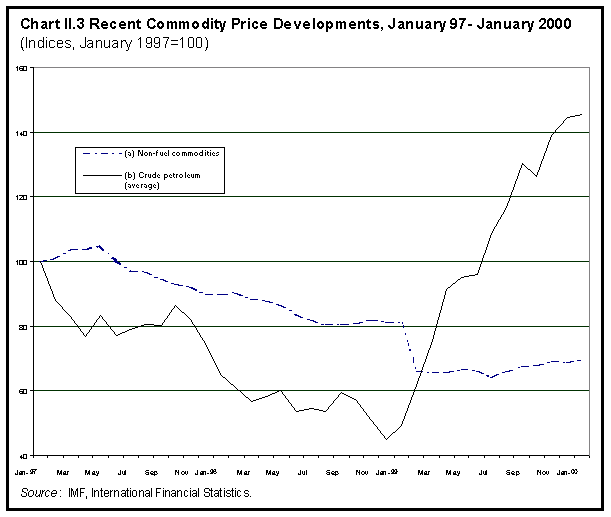
Prices of internationally traded goods decreased slightly as the increase in oil prices was offset by a further decrease in the prices of non-fuel commodities and manufactured goods. Among the non-fuel commodities, prices of food and beverages decreased by more than 15 per cent while those of agricultural materials and metals remained roughly unchanged, although they started to strengthen in the second half of 1999. Despite this partial price recovery, the annual average prices of non-fuel commodities fell to a ten year low. The decrease in the dollar price of manufactured goods can be attributed to the fall in prices of office and telecom equipment as well as the strength of the United States dollar vis-à-vis the euro and the near absence of inflation in the goods sector of all major economies.

Given that oil prices tripled from 10 dollars per barrel in February 1999 to 30 dollars in the first quarter of 2000, concerns about a resurgence of consumer prices are understandable. However, the marked reduction in the oil intensity of output in the industrial countries - by about 40 per cent since the first oil price hike more than 25 years ago - has reduced this risk considerably. The increased role of natural gas in world fuels trade has also contributed to moderate the increase in import prices of fuels. While the impact of the rebounding oil prices have been small on consumer prices in 1999, the impact was dramatic on the export revenues of the oil exporters. The Middle East recorded export growth in excess of 20 per cent in 1999, but this did not fully offset a corresponding decline in 1998.


WORLD TRADE IN 1999

1. Global trade and output developments

While the negative impact of the financial crisis in Asia and Latin America on output and trade flows were initially underestimated, the more sober projections for 1999 turned out to be too pessimistic. Output of developing countries in Asia rebounded by 6 per cent, Russian GDP recovered by 3 per cent and Brazil's economy achieved positive growth for the full year of 1999. The United States economy again provided a major stimulus to world trade last year as domestic demand grew by 5.5 per cent. By contrast, the Japanese economy stagnated and Western Europe's GDP growth decelerated to 2 per cent.

On a sectoral basis, preliminary data suggest that mining output decreased as crude oil production was cut back by 1.5 per cent and agricultural output rose for the second year in a row by only about 1 per cent. Manufacturing output recovered and expanded by about 2.5 per cent. The highly divergent growth rates of regional demand and sectoral output left their mark on global trade flows, which also differed strongly by region and sector.

The value of world merchandise trade rose by 3.5 per cent in 1999 and amounted to 5.45 trillion dollars. Average trade prices decreased for the third year in a row, although the decrease in 1999 was much smaller than in preceding years.

Trade in commercial services rose by 1.5 per cent in 1999 and thereby less rapidly than merchandise trade. Price data for United States commercial services point to a moderate increase in prices for internationally traded services. This implies that the expansion of exports of commercial services has probably also lagged behind merchandise export growth in volume terms.

World exports of merchandise and commercial services, 1997-99
 ValueAnnual change
 1999199719981999
 
Merchandise54603.5-1.53.5
 
Commercial services13404.00.01.5


2. Merchandise trade

A detailed review of world merchandise trade by product group in 1999 is not yet feasible at the time of writing this report. However, partial information indicates that rebounding oil prices have led to an increase of world fuels exports in excess of 20 per cent. Above average growth was also recorded for office and telecom equipment and automotive products. Primary products, other than fuels, on average experienced price declines in 1999. Taking into account moderate demand growth, the global value of non-fuel primary products has probably stagnated or changed only very little from the preceding year.

Preliminary data on merchandise trade by region are provided in Tables II.2 and II.3. The large variations in import volumes by region largely reflect the differences in regional demand and output growth. As can be seen from Table II.2, North America and Asia recorded import growth slightly above 10 per cent or two times faster than the global average. While for North America this was the third year in a row in which import growth exceeded 10 per cent, the developments in Asia illustrate the strength of the region's recovery, which offset the sharp import contraction in the preceding year. While imports of Asia recovered, those of Western Europe recorded a marked deceleration. The transition economies as a group recorded a 10 per cent contraction due to the sharp cut back of imports into Russia and the Ukraine. Imports of Africa and the Middle East changed little in real terms in 1999, also reflecting poor export earnings in recent years.

Table II.2
Growth in the volume of world merchandise trade by selected region, 1997-99
(Percentage change)
    
 Exports Imports
        
 199719981999 199719981999
        
World a10.54.54.5 ………
North America11.03.54.5 13.010.510.5
Latin America11.57.57.0 22.58.5-2.0
Mexico19.511.013.5 28.015.515.0
Other Latin America6.55.52.0 20.04.5-12.0
Western Europe9.55.53.5 9.08.53.5
European Union (15) 9.56.03.5 8.58.54.0
Transition economies10.55.0-3.0 13.55.0-10.0
Asia13.03.56.0 5.5-8.59.0
Japan12.0-1.52.0 1.5-5.59.5
Asia (5) b16.513.011.5 3.0-22.517.5
a Average of export and import growth.
b Indonesia, the Republic of Korea, Malaysia, Philippines and Thailand.
Note: Separate volume data are not available for Africa and the Middle East, although estimates for these regions have been made in order to calculate a world total.

The variation among regional export growth rates in 1999 was smaller than for imports. Despite sharply lower intra-regional trade, Latin America recorded the highest export expansion of all regions. Asian export growth exceeded the global average as Japan's exports recovered and the five Asian developing countries affected most by the 1997/98 financial crisis achieved double-digit export growth. North America's exports accelerated somewhat thanks to the dynamic performance of intra-trade. The deceleration of West European economic activity in 1999 led to markedly lower growth of intra-trade. While intra-European Union exports expanded two times faster than world trade in 1998, its growth in 1999 fell below that of world trade. The transition economies and the Middle East both recorded a contraction of their export volume.


Turning to developments in value terms, the Middle East reports the highest regional export growth rate despite its reduction in export volume. Africa's export growth was, at 8 per cent, the second highest among all regions. This was largely due to the sharp recovery of shipments from the region's oil-exporting countries. However, it should be recalled that for both Africa and the Middle East, the 1999 rise did not fully offset the decrease recorded in the preceding year. Latin America's exports rose by a strong 6 per cent, as the higher growth of Mexico's and some Caribbean countries' exports more than offset the sharp declines reported for all South American countries. A recovery of intra-Asian trade supported by stronger regional growth and appreciating currencies led Asian exports to regain their pre-crisis peak level. North American exports expanded by 4 per cent in 1999, following a small contraction in 1998. The marginal decline in Western Europe's export value was due to a deceleration in volume growth but above all, to a fall of nearly 4 per cent in the region's dollar export prices. The weaker export prices are principally due to the depreciation of the Euro vis-à-vis the US dollar. The sluggishness of Western Europe's import growth, together with the sharp contraction of Russia's imports, contributed to a further decrease in the export value of transition economies in 1999.

Table II.3
Growth in the value of world merchandise trade by region, 1997-99
(Billion dollars and percentage change)
    
 Exports (f.o.b.) Imports (c.i.f.)
        
 Value Annual percentage change Value Annual percentage change
            
 1999 199719981999 1999 199719981999
            
World5460 3.5-1.63.5 5725 3.5-0.84.0
North America934 9.2-0.74.0 1281 10.34.411.5
Latin America292 10.2-1.26.0 329 18.54.8-4.0
Mexico137 15.06.416.5 148 22.613.913.5
Other Latin America156 7.2-6.2-2.0 181 16.4-0.1-14.5
Western Europe2349 -0.63.4-0.5 2417 -0.35.90.5
European Union (15)2176 -0.53.8-0.5 2233 -0.56.31.0
Extra-EU (15) trade799 1.8-0.3-1.5 851 -0.36.22.5
Transition economies212 4.1-4.6-1.5 211 6.5-1.8-13.0
Central/Eastern Europe101 6.39.50.0 129 5.610.8-2.0
Russian Federation74 -0.4-15.90.0 41 6.7-19.8-30.5
Africa113 1.9-15.58.0 132 5.51.20.5
South Africa a27 6.2-9.01.5 27 9.5-9.3-8.5
Major fuel exporters b41 -0.1-31.424.0 30 9.6-0.85.5
Middle East169 4.7-22.422.0 152 8.1-3.24.0
Asia1390 5.4-6.17.5 1201 0.4-17.810.5
Japan419 2.4-7.88.0 311 -3.0-17.211.0
China195 21.00.66.0 166 2.5-1.518.0
Asia (5) c371 5.1-3.59.5 292 -3.1-30.915.5
a Beginning 1998, figures refer to South Africa and no longer to the South African Common Customs Area.
b Angola, Algeria, Congo, Gabon, Libyan Arab Yamahiriya and Nigeria.
c Indonesia, the Republic of Korea, Malaysia, Philippines and Thailand.


3. Commercial services trade

The global export value of commercial services recovered in 1999 after stagnating in 1998. Preliminary data by major services categories indicate that all categories recorded positive growth. Transportation services are estimated to have expanded less than the average growth rate of 1.5 per cent despite the increase in fuel costs. Travel services and the residual grouping of Other business services have both expanded by about 2 to 3 per cent.


The commercial services trade data by region shown in Table II.4 indicate that the most dynamic export and import growth in 1999 was in North America and Asia. While North America's services import growth exceeded its export growth, thereby reducing its traditional surplus in commercial services, Asia's imports and exports expanded at about the same rate (4-5 per cent). The rebound in Asian services trade is much weaker than for Asian merchandise trade, in particular for exports. In contrast to the developments in North America and Asia, Western Europe's services trade expanded less favourably in 1999 than in the preceding year. Available data for the transition economies point to a sharp contraction of both services exports and imports.

Table II.4
Growth in the value of world trade in commercial services by selected region, 1997-99
(Billion dollars and percentage change)
 
 Exports Imports
 
 Value Annual change Value Annual change
 
 1999 199719981999 1999 199719981999
            
World1340 402 1335 313
North America284 825 219 1069
United States252 925 182 11810
Latin America54 79-2 60 134-9
Mexico12 56-3 14 1979
Other Latin America42 810-2 47 124-13
Western Europe630 260 600 071
European Union (15)565 151 555 072
Transition economies47 02-10 44 01-8
Asia267 5-154 337 2-115
Japan60 3-9-3 114 -5-93
Hong Kong, China35 1-103 22 5-2-2
China27 19-2… 32 34-4…
Asia (5) a62 7-233 73 5-255
aIndonesia, the Republic of Korea, Malaysia, Philippines and Thailand
Note: Separate reliable data are not available for Africa and the Middle East, although estimates for these regions have been made to calculate a world total.


4. Trade by region and country

The outstanding high investment and consumption growth in the United States resulted in an expansion of imports of goods and services of more than 10 per cent in both nominal and real terms. Over the last two years United States import demand sustained world trade remarkably. Excluding shipments to the United States, the nominal value of world merchandise and services trade in 1999 would have still been below its 1997 level and the volume expansion of world merchandise trade would have been limited to 6 per cent instead of 9 per cent. The share of the United States in world merchandise imports rose to 18 per cent, the highest US share ever. Strong domestic growth was also one reason why United States merchandise exports in real terms lagged behind global trade growth. All countries having strong trade ties with the United States benefitted from this development, and in particular Canada, which expanded its merchandise exports to the United States over the last two years by about 18 per cent, or twice the rate of global trade growth.

Commercial services' imports of the United States rose by 10 per cent and two times faster than exports. Canada's import growth of commercial services recovered to 5.5 per cent, but remained for the fifth year in a row behind the expansion of its services exports. Although the expansion of United States commercial services' imports has exceeded that of exports since 1997, the United States surplus in services in 1999 still amounted to US$68 billion.

In 1999, Latin America recorded its worst annual economic performance for the last decade, as regional output stagnated and the volume of merchandise imports decreased by 2 per cent. At least eight economies recorded lower output in 1999 than in the preceding year. As in 1998, there is a striking difference in output and trade growth between Mexico and all the other Latin American countries combined. While Mexico's merchandise exports and imports rose over the last two years by more than 20 per cent, other Latin American countries combined reported a fall in exports of nearly 8 per cent and in imports of nearly 15 per cent.

A large part of the divergent performance can be attributed to differences in the export structure. Manufactured goods account for 85 per cent of Mexico's exports, but only 40 per cent for Latin America excluding Mexico. Manufactures enjoyed more stable prices than non-fuel commodities. In addition, Mexico's exports are destined largely to the booming North American market (nearly 90 per cent) while the other Latin American countries ship less than 30 per cent of their exports to North America. Mercosur experienced a contraction of its intra-trade by about one quarter, as output of its member countries declined or stagnated.

For commercial services imports, one can observe a similar divergency, as Mexico's imports rose by 15 per cent, while those of the other Latin American countries contracted by nearly 10 per cent over the last two years. Only for commercial services exports, Mexico reports a stronger decrease than the other Latin American countries in 1999. The somewhat surprising decline reported for Mexico's commercial services exports is attributed to a decrease in revenues from both travel and other business services.

The slowdown in Western Europe's output growth to 2 per cent in 1999 contributed to a markedly lower trade growth in volume terms. As more than two-thirds of Western Europe's trade is intra-regional, weak consumption growth affected both exports and imports. As regards merchandise trade, it is estimated that exports and imports grew in volume terms by about 3.5 per cent and thereby less than world trade. As the Euro and other European currencies weakened vis-à-vis the US dollar, the region's dollar export and import prices decreased on average by about 4 per cent, leading to a stagnation of their trade dollar values in 1999. Austria, France and Sweden were among the West European countries which recorded only moderate import growth, while Norway and Turkey even experienced a contraction of their import volumes in 1999. Spain, Portugal and Ireland, however, continued to be the most dynamic traders in Western Europe, with imports and exports expanding much faster than the European average.

Although output in the transition economies recovered by about 2 per cent, growth remained disappointingly low in the tenth year of transition. Poland is the only country in the region in which the output level in 1999 was above the level attained ten years ago. The sluggishness in Western Europe's economy together with a dramatic shrinkage of Russian imports depressed the region's trade in 1999. Merchandise and commercial services trade were both shrinking in dollar value and volume terms. Most of the decline was concentrated in the CIS member countries. Central and Eastern Europe's merchandise trade slowed down sharply but continued to show positive real growth in 1999. Hungary continued to record the highest trade growth among the Central/East European countries. In 1999, its merchandise exports and imports expanded by about 9 per cent in dollar terms. A major contribution to this strong trade performance was made by the expansion of intra-industry trade in office and telecom equipment and automotive products.

Africa and the Middle East recorded one of their weakest annual GDP growth performances in the 1990s. The rebound in their merchandise exports was largely due to the recovery in oil prices. Africa's merchandise exports rose by 8 per cent in 1999. The major fuel exporters recorded an increase of about one-quarter, which did not fully offset the decline recorded in 1998. South Africa and other non-fuel exporting African countries recorded an increase in their export earnings of less than 2 per cent. African imports stagnated in dollar terms for the second year in a row, as sharp declines in South Africa's imports were offset by increases by African developing countries.

Economic growth patterns differed widely in Asia in 1999. While GDP growth in the two most populous countries in the region, China and India, was about 7 per cent, the output in Japan, the largest economy in Asia, stagnated. Among the five Asian countries severely affected by financial crisis, the Republic of Korea recorded an outstanding recovery with double digit growth, while Indonesian output stagnated. Asian developing countries as a group recorded an output expansion of 6 per cent, at least two times faster than any other developing region.

One of the outstanding developments of Asian trade in 1999 was the double digit trade volume growth of the five Asian countries most affected by financial crises in 1997-98. Their export expansion remained very strong (11.5 per cent) and imports rebounded sharply without offsetting fully the contraction of the preceding year. The regional recovery and the cyclical recovery in the electronic goods industry contributed largely to this dynamic growth. For the Republic of Korea and Malaysia, exports of office and telecom equipment accounted for more than 80 per cent of the overall increase of their export value in 1999.

Japan's merchandise trade recovery was strong, taking into account its stagnating economy. However, export and import values did not regain their pre-crisis peak levels. Japan's commercial services exports continued to shrink, while imports picked-up after a marked decrease in 1997-98. China's merchandise imports expanded by 18 per cent while those of Hong Kong, China decreased for the second consecutive year. A notable feature in Asia's trade is the steady decline of the share of Hong Kong, China in Asia's merchandise trade. Hong Kong, China's domestic exports and retained imports had by 1999 fallen below their 1990 level. This decline has to be seen in the context of the relocation of Hong Kong, China's manufacturing industry to China, which in turn has greatly enhanced its share in world exports. In respect to commercial services, however, Hong Kong, China maintains its position as the leading developing country exporter. For the Asian region, exports of commercial services decreased more strongly in 1998 and recovered by far less in 1999 than did merchandise exports. For imports of commercial services, the recovery in 1999 was also far smaller than for merchandise trade.

Looking at trade performance by country, the following features emerge for 1999 trade developments (see Appendix Tables). First, the United States consolidated its leading position in world merchandise imports and world commercial services exports. Its share in world merchandise imports reached, at 18 per cent, its highest level ever. Second, oil-exporting countries recorded in general the highest export growth in 1999 (at least 16 of them recorded export increases ranging from 15 per cent to 50 per cent). For most of them the increase in 1999 did not fully offset the declines recorded in the preceding year. Third, exporters of office and telecom equipment benefitted from the recovery in the global electronic goods industry. The double digit export growth of the Republic of Korea, Malaysia, the Philippines, Costa Rica and Israel was largely due to office and telecom equipment exports. Fourth, a large number (at least 24) of South American and transition economies recorded double-digit decreases in their imports and often also a fall in their export values. The main causes of these bleak developments include the steep fall of intra-regional trade and the low prices of non-fuel commodities. Fifth, the four largest traders in Western Europe (France, Germany, Italy and the United Kingdom) all recorded a small decline in their merchandise export values and minimal changes in their imports.


5. Processing trade contributes to exceptional trade expansion in selected developing countries

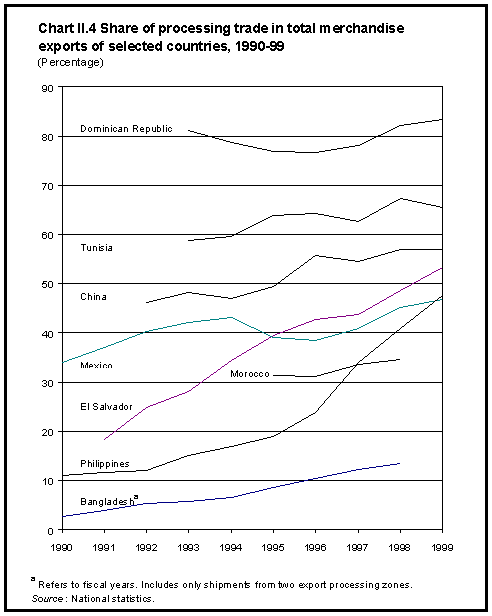
Over the last fifteen years, the outstanding high trade growth recorded by a selected number of developing countries can be partly attributed to the expansion of their "processing trade". Beside multilateral and regional trade liberalization, an increasing number of countries have modified their import regime by granting, under certain conditions, duty-free access to those imports which are bound for the processing and assembling of goods destined for exports. This preferential tariff treatment was initially limited to trade which went through specific areas (e.g. the Special Economic Zones in China or the maquiladoras zones in Mexico) but often extended thereafter to companies located outside these specifically designated areas. While the number of export processing zones has risen to about 850, their success in expanding employment and trade is mixed. In several countries employment in these zones rose sharply and trade was growing rapidly while in many other countries the creation of special zones granting tariff preferences to processing trade had a negligible impact on both trade and employment. In the 1990's the most dynamic processing traders among the developing countries are to be found in Asia and Latin America.

A comprehensive appreciation of the contribution of "processing trade" to the expansion of developing countries' merchandise exports and imports is not attempted here, as the data on processing trade are not as readily available as standard trade statistics. However, the examples given below show that the "processing trade" has gained in importance and often played a crucial part in these countries' overall trade performance. All the eight countries presented in Chart II.4 have recorded an expansion of exports well ahead of the global average in the last decade. Five of them recorded average annual export growth rates around 15 per cent, which is about three times faster than the global trade expansion of 5.5 per cent.

Leading exporters and importers in world merchandise trade (excluding intra-EU trade), 1999


Preferential tariff treatment to "processing trade" is not only a feature of trade regimes in the developing countries. Industrial countries too are often providing duty exemption or reduction on imported goods if these products have been manufactured abroad with materials/components from the importing country. While the value of these imports can be relatively important in bilateral trade flows, their share in total imports is at present rather moderate. For the United States and the European Union the share of imports benefitting from this specific duty exemption amounted to 8 per cent in the US and to 2 per cent in the EU (excluding intra-trade) in 1998. In the United States the share of processing trade in total imports declined markedly as trade with Mexico and Canada became increasingly tariff free with the implementation of NAFTA.

Table II-5
Processing trade and export performance of selected countries, 1990-99
(Billion dollars and percentage)
 Total exportShare ofValue of
 growthprocessing tradeprocessing exports
Country1990-199919981998
 (percent)(percent)(billion $)
 
Dominican Republic an.a. 82.2 4.1 
Tunisia5.9 67.4 4.0 
China13.5 56.9 104.6 
El Salvadorb16.8 48.6 1.2 
Philippines16.5 40.9 12.1 
Mexico14.4 45.2 53.1 
Morocco6.4 34.7 2.6 
Bangladesh c15.2 13.4 0.7 
Memorandum item:      
World total5.4 … … 
 
a Between 1993 and 1998 exports grew by 9.2% and world exports by 7.7% annually.
b Refers to years 1991-1999.
c Refers to fiscal years.
Source: National Statistics


6. Outlook

Global economic output is expected to accelerate from 3 per cent in 1999 to about 3.5 per cent in 2000. The volume of world merchandise trade growth should reach 6.5 per cent. Higher trade growth is possible, in particular, if the demand in Western Europe and Japan pick up more strongly than currently projected.

In 2000, GDP growth of industrial countries could expand by 3 per cent or one half per cent faster than in 1999 as moderately lower growth in the United States is more than offset by higher growth in Western Europe and Japan. Latin America and the Middle East should see a strong pick-up in their GDP growth after experiencing a stagnation of output in 1999. Higher growth is also projected for the transition and African economies. GDP growth of the Asian developing countries is projected to remain unchanged as the impact of the expansionary fiscal policies and the rebuilding of inventories will be less important in 2000 than in 1999, but offset by a strengthening of fixed investment and private consumption.

More robust growth of the world economy in 2000, together with the carry-over effect due to the trade acceleration in the second half of 1999 is projected to lead to export volume growth of at least 6.5 per cent. Most of this higher growth is expected to come from Western Europe and to a lesser extent from Latin America, the Middle East and the transition economies. North America and the developing countries in Asia, which recorded double digit import growth in 1999, are likely to expand their imports less rapidly in 2000, and the projected deceleration of North America's final demand should lead to less dynamic import growth in 2000.

The projections above assume that the oil price will recede from its US$30 per barrel level in the first quarter back to a range of US$20 to US$25 and that major financial market turbulence - in particular a sudden sharp correction of stock markets and the dollar rate - can be avoided in the remaining months of the year. A sharp correction of the stock markets, together with a marked slowing down of United States demand and imports, could alter the trade forecast significantly. Note, for example, that at nearly 350 billion dollars, the United States merchandise trade deficit in 1999 exceeded the total imports of Japan. A disruptive adjustment of the current external imbalances would imply a major risk to trade growth in the near future.


Appendix Table 1
Leading exporters and importers in world merchandise trade, 1999
(Billion dollars and percentage)
 
 Annual Annual
 percentage percentage
ExportersValueSharechange ImportersValueSharechange
 19981999 19981999
 
United States695.012.4-12 United States1059.918.0512
Germany540.59.660 Germany472.68.060
Japan419.47.5-88 United Kingdom320.75.522
France299.05.35-2 Japan310.75.3-1711
United Kingdom268.44.8-3-2 France286.14.97-1
Canada238.44.2011 Canada220.23.737
Italy230.84.11-5 Italy216.03.730
Netherlands204.13.642 Netherlands188.93.251
China194.93.516 Hong Kong, China181.73.1-12-3
Belgium-Luxembourg184.13.363 retained imports a29.20.5-30-20
      Belgium-Luxembourg169.42.972
 
Hong Kong, China174.83.1-70 China165.72.8-118
domestic exports22.20.4-10-10 Mexico148.22.51413
Korea, Rep. of144.22.6-39 Spain145.02.589
Mexico136.72.4616 Korea, Rep. of119.72.0-3528
Taipei, Chinese121.62.2-910 Taipei, Chinese111.01.9-86
Singapore114.62.0-124 Singapore111.01.9-239
domestic exports68.61.2-138 retained imports a65.01.1-3118
Spain109.42.050 Switzerland80.11.450
Malaysia84.51.5-715 Australia69.01.2-27
Sweden84.51.520 Sweden68.21.240
Switzerland80.61.442 Austria67.81.250
Russian Fed. b74.31.3-160      
 
Ireland69.61.2208 Malaysia65.51.1-2612
Austria62.01.17-1 Brazil51.80.9-7-15
Thailand58.41.0-57 Thailand50.60.9-3218
Australia56.11.0-110 Ireland45.60.8142
Saudi Arabia50.50.9-3527 Poland44.80.811-5
Indonesia48.50.9-9-1 India44.60.834
Brazil48.00.9-4-6 Denmark43.30.74-6
Denmark47.80.9-1-1 Russian Fed. b41.10.7-20-30
Norway44.90.8-1813 Turkey39.20.7-5-15
Finland41.50.76-4 Portugal37.60.652
 
Total of above c4927.087.8-- Total of above c4976.084.7--
World c5610.0100.0-23 World c5875.0100.0-14
 
a Retained imports are defined as imports less re-exports.
b Includes trade with the Baltic States and the CIS.
c Includes significant re-exports or imports for re-export.

Appendix Table 2

(Billion dollars and percentage)
 
 Annual Annual
 percentage percentage
ExportersValueSharechange ImportersValueSharechange
 19981999 19981999
 
European Union(15)798.618.90-1 United States1059.923.6512
United States695.016.4-12 European Union (15)851.218.963
Japan419.49.9-88 Japan310.76.9-1711
Canada238.45.6011 Canada220.24.937
China194.94.616 Hong Kong, China181.74.0-12-3
Hong Kong, China174.84.1-70 retained imports a29.20.6-30-20
domestic exports22.20.5-10-10 China165.73.7-118
Korea, Rep. of144.23.4-39 Mexico148.23.31413
Mexico136.73.2616 Korea, Rep. of119.72.7-3528
Taipei, Chinese121.62.9-910 Taipei, Chinese111.02.5-86
Singapore114.62.7-124 Singapore111.02.5-239
domestic exports68.61.6-138 retained imports a65.01.4-3118
 
Malaysia84.52.0-715 Switzerland80.11.850
Switzerland80.61.942 Australia69.01.5-27
Russian Fed. b74.31.8-160 Malaysia65.51.5-3512
Thailand58.41.4-57 Brazil51.81.2-7-15
Australia56.11.3-110 Thailand50.61.1-3218
Saudi Arabia50.51.2-3527 Poland44.81.011-5
Indonesia48.51.1-9-1 India44.61.034
Brazil48.01.1-4-6 Russian Fed. b41.10.9-20-30
Norway44.91.1-1813 Turkey39.20.9-5-15
India36.50.9-49 Norway33.80.81-7
 
Philippines35.00.81819 Israel33.20.7-513
United Arab Emirates29.50.7-1315 Philippines32.60.7-184
Czech Rep.26.80.6162 Saudi Arabia30.00.740
Poland26.80.610-5 United Arab Emirates28.90.6-96
South Africa c26.70.6-91 Czech Rep. d28.90.660
Turkey26.20.63-3 Hungary27.70.6218
Israel25.30.6210 South Africa c26.80.6-9-8
Hungary24.60.6207 Argentina25.50.63-19
Argentina23.30.60-12 Indonesia23.90.5-34-13
Venezuela18.90.4-2110 Egypt16.20.4220
 
Total of above e3884.091.8- - Total of above e4073.090.7--
World (excl. intra-EU trade) e4232.0100.0-44 World (excl. intra-EU trade) e4494.0100.0-35
 
a Retained imports are defined as imports less re-exports.
b Includes trade with the Baltic States and the CIS.
c Beginning 1998, figures refer to South Africa and no longer to the South African Common Customs Area.
d Imports are valued f.o.b.
e Includes significant re-exports or imports for re-export.

Appendix Table 3
Leading exporters and importers in world trade in commercial services, 1999
(Billion dollars and percentage)
         
   Annual    Annual
   percentage    percentage
ExportersValueSharechange ImportersValueSharechange
   19981999    19981999
           
United States251.718.825 United States182.313.7810
United Kingdom101.47.672 Germany127.29.532
France79.35.95-6 Japan113.98.5-93
Germany76.85.73-3 United Kingdom81.46.1114
Italy64.54.80-3 Italy62.74.770
Japan59.84.5-9-3 France59.24.45-9
Spain54.14.01211 Netherlands46.53.540
Netherlands53.14.033 Canada37.12.8-45
Belgium-Luxembourg37.62.864 Belgium-Luxembourg35.52.684
Hong Kong, China35.42.6-103 China32.12.4-4…
           
Austria32.62.493 Spain30.92.31312
Canada32.42.427 Austria29.52.26-2
Switzerland27.22.055 Korea, Rep. of26.72.0-1914
China26.62.0-2… Ireland23.51.83218
Korea, Rep. of25.01.9-65 Taipei, Chinese23.21.7-40
Singapore22.91.7-4025 Sweden22.81.7115
Sweden18.01.312 Hong Kong, China22.41.7-2-2
Australia17.21.3-139 Singapore19.31.4-78
Denmark16.01.268 Australia18.01.3-86
Turkey16.01.221-31 India17.31.31622
           
Taipei, Chinese14.81.1-2-11 Denmark16.21.2135
Thailand14.11.1-168 Switzerland15.71.283
Norway13.71.0-3-2 Norway15.41.242
India13.21.02419 Thailand13.91.0-3117
Mexico11.60.96-3 Mexico13.71.079
Malaysia10.80.8-24… Malaysia13.01.0-24…
Greece10.50.86… Indonesia12.70.9-288
Israel10.30.8814 Russian Fed.11.70.9-14-27
Poland9.80.721-10 Brazil11.60.99-26
Russian Fed.9.70.7-9-25 Israel10.70.8512
           
Total of above1165.087.1-- Total of above1145.085.9--
World1340.0100.00.01.5 World1335.0100.00.52.5

›››Archivo
DESDE LA PRIMERA PÁGINA
Puerto de Rotterdam: El tráfico de carga general disminuye en el tercer trimestre, mientras que el tráfico de carga a granel aumenta.
Róterdam
En los primeros nueve meses de 2026 se manipularon 323,2 millones de toneladas (+0,9%).
Nace el Observatorio de Construcción Naval de Liguria: un sector valorado en dos mil millones de euros y que emplea a más de 10.000 personas.
Génova
AdSP, Confindustria Genova y Unione Industriali Savona lanzan un seguimiento permanente del sector
La BPA afirma que el crecimiento del sector de contenedores en el Reino Unido depende de la inversión, no de las fugas de carbono.
Londres
Un informe de la asociación británica refuta al Observatorio Español: el indicador en teu-millas no mide volúmenes reales y amplifica el efecto del orden de los puertos de escala.
El sistema de comercio de emisiones (ETS, por sus siglas en inglés) representa el 10% de las emisiones, pero paga casi el 20% de la factura.
Bruselas
Estudio de ECSA: Los armadores europeos solicitan cuotas triples del SMAP para combustibles y tecnologías sostenibles.
AP Moller Capital adquirirá Portek International Port Group.
Copenhague
Será comercializado por la empresa japonesa Mitsui & Co.
La disputa portuaria entre Washington y Madrid amenaza con convertirse en una guerra comercial.
Washington
La FMC propone un gravamen de 200 mil dólares por viaje a los buques con bandera española y restricciones a la importación de ciertos productos.
Reforma portuaria: la Comisión rechaza los cambios en la gobernanza de Puertos de Italia.
Roma
Ayer, la Comisión de la Cámara de Diputados votó el artículo 9 del proyecto de ley 2925: las enmiendas de la oposición fueron rechazadas; su posterior examen se ha aplazado a otra sesión.
El puerto de Singapur establece un nuevo récord histórico de movimiento trimestral de contenedores (TEU).
Singapur
Las ventas de combustible marino ponen de manifiesto la continua transformación del mercado de combustibles.
Dos buques portacontenedores fueron alcanzados por proyectiles mientras transitaban por el estrecho de Ormuz.
Southampton/Singapur
El "GFS Pride" sufrió daños y un incendio a bordo, y posteriormente se hundió.
Ataques a barcos y puertos: el ETF hace un llamamiento a los líderes de la UE.
Bruselas
"Necesitamos acción, no otra declaración de preocupación": el sindicato exige que la seguridad de los trabajadores sea el eje central de la respuesta europea en el Mar Negro.
Según el tribunal de Génova, RINA es responsable del hundimiento del Al Salam Boccaccio '98 .
Génova
La empresa manifiesta su profundo desacuerdo y recuerda las conclusiones de otras investigaciones.
Perú planea un segundo puerto nacional importante
Archivo
El puerto de Corío se construirá en la costa sur del país para servir también a las exportaciones brasileñas.
Los ataques contra barcos en el estrecho de Ormuz y el mar Negro se están multiplicando.
Sofía/Southampton/Nueva Delhi
Dos embarcaciones resultaron heridas en la zona económica especial de Bulgaria.
Sistema de comercio de emisiones marítimo: El SMAP bajo escrutinio por parte de quienes producen los combustibles del futuro.
Bruselas
Una carta conjunta de productores, empresas de servicios públicos, armadores y ONG solicita la reserva de cuotas para combustibles sintéticos y la introducción de la reserva anticipada.
El puerto de Los Ángeles establece nuevos récords históricos de movimiento de contenedores, tanto mensuales como trimestrales.
Los Ángeles
Nuevos picos en contenedores llenos al desembarcar y cajas vacías
Rheinmetall adquiere el astillero de Mangalia por 138 millones de euros.
Bucarest
El proyecto está vinculado al relanzamiento de la industria naval rumana y a la construcción de cuatro unidades para la Armada.
Nace United Transport Mutual: barcos, puertos y logística bajo un mismo paraguas asegurador.
Londres
Los miembros del UK P&I Club y del TT Club aprueban la fusión, conservando los nombres, las marcas y los equipos.
En España, el transporte marítimo de corta distancia está en declive.
Madrid
La SPC España advierte que los costes de las regulaciones ambientales están alejando el tráfico marítimo del mar.
Puerto de Ravenna, agosto -20,5% y septiembre estimado -9%.
Rávena
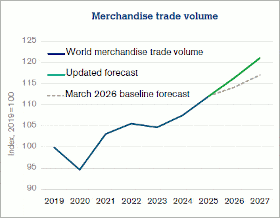
El comercio mundial es más resistente de lo esperado. La IA está impulsando el sector de bienes, mientras que el de servicios se está frenando.
Ginebra
La OMC revisa sus estimaciones: el crecimiento del comercio de bienes se sitúa en el 3,9% en 2026, y el de servicios en el 3,3%. Sin embargo, el impacto de la crisis de Oriente Medio no afecta por igual a todos.
Puertos europeos: la sostenibilidad entra en fase de implementación
Bruselas
De las políticas a los resultados: el informe de ESPO documenta en imágenes el progreso, los retrocesos y las prioridades del sector.
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
El gobierno federal alemán prohíbe la venta de Zippel al grupo chino COSCO.
Berlina
En febrero la autoridad antimonopolio lo había aprobado.
Informe de Fedespedi: Los puertos del norte del Adriático están creciendo, pero hablan esloveno y croata.
Milán
Assoporti representó la posición italiana sobre el RCDE UE en ESPO.
Roma
Petri: No a la aplicación indiscriminada de normas diseñadas para realidades territoriales profundamente diferentes.
DP World se asegura diez años más de gestión de la terminal multipropósito en el puerto de Luanda.
Dubái
Desde 2021, ha invertido más de 260 millones de dólares en ella.
El puerto de Nápoles, la Darsena di Levante - advierte Confindustria Napoli - ya no puede esperar
Nápoles
El nuevo tren lanzadera de Hupac entre Busto Arsizio/Gallarate y Barcelona
Ruido
El servicio, que tendrá una frecuencia de tres semanas, se inaugurará el 9 de noviembre.
Uniport: La resiliencia portuaria debe transformarse en crecimiento.
Roma
La asociación insta al gobierno a que establezca plazos claros para las infraestructuras y el dragado, a que otorgue mayor peso a las empresas en la toma de decisiones y a que modifique el RCDE UE.
Bangladesh busca aumentar la competitividad del sector de reciclaje de buques.
Daca
Se planea construir una planta para el tratamiento, almacenamiento y eliminación de los residuos resultantes del desguace de buques.
Tres buques mercantes chocaron en el Mar Negro en las zonas económicas especiales de Rumania y Bulgaria.
Bucarest/Sofía
Los accidentes han tenido graves consecuencias: dos muertos, varios heridos y toda la tripulación desaparecida.
HD Hyundai instala el primer sistema que elimina el amarre y desamarre de contenedores en los buques.
Seúl
Un buque portacontenedores de 13.000 TEU de CMA CGM ha sido equipado con él.
Continúan los ataques contra barcos en el estrecho de Ormuz.
Southampton/Londres
Otro buque fue alcanzado ayer. Se han registrado 93 incidentes en Oriente Medio desde principios de año.
Deep Wave amplía su plataforma digital a pasajeros y cruceros.
Graz
Inversión en la empresa austriaca MarineXchange
Han comenzado las obras de construcción de una terminal de cruceros en el puerto japonés de Naha.
Naha
Está previsto que las operaciones comiencen en marzo de 2028.
Assiterminal promueve la reforma portuaria, pero exige correcciones en Puertos de Italia.
Génova
Los operadores de terminales destacaron tres cuestiones críticas: el papel del proveedor de servicios publicitarios (AdSP), la superposición entre el otorgante y el concesionario, y la retroactividad de las nuevas regulaciones.
Buques de GNL y taxonomía: el Tribunal de Justicia de la UE rechaza la falta de límites para el metano.
La Comisión deberá establecer un umbral de emisiones de metano para los criterios del transporte marítimo. La apelación presentada por tres ONG fue parcialmente admitida.
Puertos: La Comisión Europea insta a Italia a rechazar el requisito de la bandera nacional para el remolque y el amarre.
Bruselas
Francia y España también recibieron un dictamen motivado: dos meses para cumplir con la normativa sobre servicios portuarios.
Otro barco fue atacado en el estrecho de Ormuz.
Southampton/Teherán
Irán se enfrenta a una escasez de productos básicos, que también se importan a través del Golfo Pérsico.
Corredores europeos: Italia se enfrenta al reto de 2030.
Bruselas
La infraestructura nacional cumple en gran medida con los requisitos, pero el calendario y la financiación de los proyectos clave siguen siendo inciertos.
Electrificación de puertos y aeropuertos: la red eléctrica es el nuevo cuello de botella.
Bruselas
El Ministerio de Transporte y Medio Ambiente pide que se agilicen las conexiones y que se supere el criterio de "el primero que llega es el primero en ser atendido".
Boluda gestiona la terminal polivalente del muelle Príncipe de Espanya en el puerto de Barcelona
Barcelona
El contrato de concesión tendrá una duración de 16 años.
El valor actual del Aeropuerto de Génova Spa se sitúa entre 14,9 y 15,9 millones de euros.
Génova
Evaluación de PwC presentada
FEPORT: El sistema de comercio de derechos de emisión de la UE no debería expulsar el transbordo fuera de Europa.
Bruselas
La federación de operadores de terminales insta a la comisión ENVI a reforzar las medidas contra la evasión fiscal y a destinar parte de los ingresos del Sistema de Comercio de Emisiones (ETS) a los puertos.
Nueva serie de ataques contra barcos en el estrecho de Ormuz.
Southampton/Teherán/Tampa
Tres buques cisterna fueron alcanzados por proyectiles. Otro barco se incendió.
Eurokai, mayores ingresos pero menores beneficios.
Hamburgo
Los ingresos aumentaron un 14,4% y el tráfico un 8,3%, pero el beneficio neto cayó un 8,3% debido a la menor cuota de mercado de Eurogate.
Impuesto sobre el alojamiento en Génova: el Tribunal Administrativo Regional falla a favor del Ayuntamiento.
Génova
El recurso presentado por los armadores y agentes navieros fue rechazado.
Carnival registra ingresos y beneficios récord en el trimestre de junio a agosto, a pesar de un aumento del 36% en los costes del combustible.
Miami
Los depósitos de los clientes están en su punto más alto. Se espera que los precios y la ocupación alcancen niveles récord el próximo año.
Ganadores y perdedores en la conectividad portuaria: la larga trayectoria de los altibajos de los puertos italianos.
Ginebra
Los índices de la UNCTAD revelan un Mediterráneo en transformación: Italia cae al séptimo puesto, La Spezia, Trieste y Vado Ligure crecen, mientras que el sur pierde terreno.
Los camiones eléctricos son más asequibles que los diésel en seis de los principales mercados de la UE.
Bruselas
Según T&E, en los países que representan el 46% de las ventas europeas, los vehículos eléctricos ya se han abaratado en cinco años. Italia, España y Polonia se encuentran rezagadas.
AP Moller Capital adquirirá una participación mayoritaria en Euroports.
Copenhague/Amberes
R-Logitech se desvinculará del capital, mientras que PMV y SFPIM seguirán siendo accionistas.
En China, las exportaciones están creciendo, pero la actividad en los puertos se está ralentizando.
Pekín
En agosto, el comercio exterior mundial aumentó un 19,8%, pero el volumen de mercancías internacionales gestionadas por los puertos marítimos disminuyó un 2,3%.
De Puertos del Estado a Puertos de Italia: la misma inspiración, un resultado opuesto.
Génova
Para la reforma portuaria, el gobierno se remite al modelo español, pero está construyendo justo lo contrario: otro contrapeso más, de esos que el espíritu empresarial italiano sabe inventar tan bien.
Sistema de comercio de derechos de emisión marítimo: Bruselas se abre a los ferris híbridos y eléctricos, pero Interferry exige más.
Bruselas
La revisión propuesta refuerza el mecanismo SMAP, pero deja la cuestión de las redes e infraestructuras portuarias en manos de AFIR y FuelEU Maritime.
Un marinero muere a bordo de un buque granelero atacado en el estrecho de Ormuz.
Nueva Delhi/Southampton/Teherán
Los demás miembros de la tripulación fueron rescatados.
El tráfico de mercancías en los puertos de Génova y Savona-Vado sigue oscilando entre signos de recuperación y ralentización.
Génova
En julio, los volúmenes aumentaron en ambos puertos de Liguria.
Trasportounito ofrece un sistema automático para ajustar las tarifas de transporte por carretera al precio del diésel.
Roma
Gente de mar, cinco años después de la entrada en vigor del Código de Conducta, la brecha entre la política y la realidad persiste.
Londres
El cumplimiento normativo por parte de las compañías navieras está aumentando, pero persisten problemas relacionados con la fatiga, la seguridad psicológica, las quejas y los costes de contratación.
El mes pasado, el tráfico marítimo en el Canal de Suez aumentó un 26,9%.
Ismailia
En los primeros ocho meses de 2026, fue cruzada por 9.602 barcos (+17,4%).
La decisión sobre el tramo ferroviario crucial del Corredor Escandinavo-Mediterráneo en Alemania se pospone nuevamente.
Hamburgo
Los operadores portuarios alemanes reclaman una aceleración tanto de la construcción de nuevas infraestructuras como del fortalecimiento de la línea existente.
Kuehne+Nagel acuerda una alianza estratégica a largo plazo con Amazon.
Schindellegi
El acuerdo incluye una opción de compra sobre las acciones existentes del grupo logístico.
MSC está en conversaciones para adquirir el grupo alemán de construcción naval Meyer Werft.
Nueva York
Actualmente, el 80,73% del capital está en manos del Gobierno Federal Alemán y del Estado de Baja Sajonia.
En agosto, los puertos de Liguria Occidental gestionaron 5,2 millones de toneladas de mercancías (+1,6).
Génova
En Génova se registró un aumento del +6,1%, mientras que Savona-Vado Ligure sufrió un descenso del -10,0%.
Raben Italia abre un nuevo almacén en Pomezia.
Milán
El objetivo es consolidar el posicionamiento y la expansión territorial en el transporte por carretera.
El puerto de La Spezia firma un acuerdo para desarrollar proyectos de economía azul y seguridad.
La Spezia
Fue firmado por la AdSP y la Fundación del Centro Nacional de la Dimensión Subacuática.
El puerto de Long Beach celebra un nuevo récord mensual de movimiento de contenedores.
Playa larga
Nuevo máximo histórico también en el trimestre de julio a septiembre.
Se ha abierto la licitación para la demolición parcial del muelle norte del puerto de Ancona.
Ancona
La intervención incluye la regularización de los fondos marinos correspondientes.
HMM invierte más de 1.600 millones de dólares en 12 nuevos buques portacontenedores.
Busan
Para 2029, se entregarán ocho buques de 13.000 TEU, tres buques de 2.800 TEU y un buque de 1.700 TEU.
Paolo Pessina confirmado como presidente de Federagenti
Roma
Votación unánime de la asamblea de la Federación
Han comenzado las negociaciones para renovar el convenio colectivo único del sector naviero.
Roma
Las partes han acordado un intenso calendario de reuniones.
El tráfico de contenedores en el puerto de Hong Kong creció un 15,1% en el tercer trimestre.
Hong Kong
En septiembre el aumento fue del +25,0%.
Formación marítima: Apelación ante el Tribunal Administrativo Regional (TAR) contra el aumento de tarifas de la Autoridad Portuaria.
Roma
ANIFORMAR, CONFORMAR y 15 centros de formación desafían el decreto del MIT-MEF: los aumentos alcanzan hasta el 149,3%.
El Grupo Spinelli ha inaugurado un nuevo depósito de contenedores vacíos en Novi Ligure.
Génova
Inversión por valor de 14 millones de euros.
Rhenus integra sus servicios logísticos en un único centro logístico en el Interporto de Padua.
Padua
El complejo reunirá transporte por carretera, transporte aéreo y marítimo, almacenamiento y servicios especializados.
Un camionero fallece en el puerto del canal de Cagliari.
Cagliari
Habría quedado aplastado por una carga de tuberías grandes.
Confitarma, empresa dedicada al sector marítimo, está preocupada por la incertidumbre que surge de la interpretación que hace la Agencia Tributaria.
Mitsubishi Heavy Industries planea ampliar su capacidad de construcción naval.
Tokio
La empresa planea invertir 100 mil millones de yenes.
Trasportounito: El gobierno está loco si piensa que la crisis del transporte por carretera se puede resolver por sí solo.
Roma
Se insta a la aplicación de la cláusula de ajuste del costo del diésel.
Emanuele Grimaldi es el nuevo presidente de la Asociación Internacional de Armadores de Malta.
La Valeta
Sucede en el cargo a Marily Frangista, quien ha estado al frente de la asociación desde abril de 2022.
La cuarta edición de la Green Logics Expo arranca mañana por la mañana en Padua.
Padua
Contará con la participación de más de 300 expositores y la celebración de 30 eventos de conferencias.
En el tercer trimestre de este año, el tráfico de mercancías en los puertos turcos disminuyó un -1,1%.
Ankara
Los volúmenes de tráfico desde y hacia Italia crecieron un +6,2%.
En Assiterminal, la flexibilidad de los PRP debe tener en cuenta el mercado relevante en el que operan los puertos.
Génova
PROXIMAS SALIDAS
Visual Sailing List
Salida
Destinación:
- orden alfabético
- nación
- aréa geogràfica
Cetus Maritime planea cotizar en la bolsa de valores Euronext Growth Oslo.
Hong Kong
Adquisición de 16 buques en preparación para su cotización en bolsa.
El sábado, un avión estadounidense impactó contra un buque granelero en el Golfo de Omán.
Tampa
Centcom: El barco había intentado imponer un bloqueo naval contra Irán.
Buque impactado cerca del estrecho de Ormuz
Southampton
Una bala provocó un incendio que posteriormente fue extinguido.
OOCL informa un crecimiento del 9,0% en los volúmenes transportados por buques en el tercer trimestre.
Hong Kong
El aumento del valor de las tarifas de flete marítimo provoca un incremento del +45,1% en los ingresos.
HD Hyundai Marine Solutions adquirirá la empresa estadounidense Goltens Worldwide.
Dubái/Seongnam
La empresa se dedica a la reparación y el mantenimiento de grandes motores marinos y maquinaria industrial.
UNATRAS al gobierno: Desbloquee de inmediato las medidas para reducir los precios del diésel.
Roma
Las asociaciones de transporte por carretera denuncian retrasos e incertidumbres en la aplicación del acuerdo del 22 de mayo y solicitan una reunión urgente.
Puerto de Taranto: Gugliotti reitera su solicitud al gobierno de financiación para el parque eólico del puerto.
Taranto
El proyecto —subrayó— no puede ni reducirse ni posponerse.
Ataque a un barco en medio del Golfo Pérsico.
Southampton
La UKMTO informó que varios proyectiles causaron bajas entre los miembros de la tripulación.
Gioia Tauro: Se aprueba la adenda al Plan Portuario actualizado.
Gioia Tauro
Este análisis nos permitirá evaluar las necesidades de personal y de contratación de la Agencia Portuaria.
Barcos haciendo cola, combustible desperdiciado: cómo esperar fondeado puede ahorrarle dinero.
Copenhague
El Foro Marítimo Global publica los resultados de las pruebas realizadas por Cargill en 16 viajes reales. Reducir la velocidad y llegar cuando el muelle está libre disminuye el consumo de combustible y las emisiones.
ZIM eleva sus previsiones para todo el año 2026.
Haifa
Se espera que el EBITDA ajustado y el EBIT sean de 2.700 millones de dólares/3.000 millones de dólares y de 1.400 millones de dólares/1.700 millones de dólares.
Gabriele Sangiorgi ha sido nombrado secretario general interino de la Autoridad Portuaria de Rávena.
Rávena
El mandato de Fabio Maletti ha expirado.
Puerto de Génova: Los trabajadores de la terminal de Messina se declaran en huelga durante una hora por un mes.
Génova
La empresa informa que uno de los miembros del sindicato no se presentó a la última reunión, en cumplimiento del procedimiento de reflexión previsto en el Convenio Colectivo Nacional.
Puerto de Taranto, acuerdo para participar en el desarrollo del Valbasento Interporto en Ferrandina.
Matera/Taranto
Se elaborará un plan maestro logístico-funcional en un plazo de 180 días.
En Ática, el déficit se reduce principalmente gracias a las ganancias de capital y la cobertura.
Kallithea
Primer semestre del año con menos cruces y un ligero aumento de los ingresos.
Desde principios de año, el número de pasajeros y mercancías en los buques de GNV ha aumentado un +2% y un +5%, respectivamente.
Marrakech
Asociación estratégica de tres años con la Oficina Nacional Marroquí de Turismo.
Escola Europea - Transporte Intermodal celebra su 20 aniversario
Barcelona
Un viaje por el Mediterráneo entre Barcelona, Civitavecchia, Palermo y Génova.
Filt Cgil reconoce que el trabajo marítimo y portuario es arduo.
Roma
El sindicato exige que se incluya una disposición clara al respecto en la próxima ley de presupuestos.
Un petrolero fue atacado en el estrecho de Ormuz.
Southampton
La unidad continuó su navegación con normalidad.
FS Logistix e Interporto Bologna presentaron el primer tren experimental italiano con convertidor de amplitud directa (DAC).
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
Sanilog lanza una campaña especial de prevención del cáncer.
Roma
Tres nuevas áreas dedicadas a la prevención de cánceres de cabeza y cuello y de cavidad oral y a la evaluación del riesgo vascular.
Se ha adjudicado el contrato para el dragado y la finalización de la electrificación de los muelles del puerto de Gioia Tauro.
Gioia Tauro
Serán llevadas a cabo respectivamente por Dravo y RTI Saet-Suardi.
Premio de estudiante de arquitectura naval otorgado en Génova
Génova
El Grupo d'Amico y la Real Institución de Arquitectos Navales reconocen la excelencia en la ingeniería naval.
El transporte de mercancías resulta más caro para Malta: 35 millones de euros al año entre ETS, FuelEU y BAF.
Zebbug
La asociación de transportistas insta al gobierno a cuestionar una política europea diseñada para el continente.
CMA CGM ha finalizado la adquisición de FedEx Supply Chain.
Marsella/Atlanta
Con esta transacción, la presencia de CEVA Logistics en Norteamérica se ha triplicado.
Contships para encargar 10 buques alimentadores con opciones para 10+10 adicionales.
Atenas
Carta de intención con la empresa china Hubei Guangji Green Energy Shipbuilding Group Co.
DP World firma un acuerdo para desarrollar un puerto de aguas profundas en el estado de Ogun, en Nigeria.
Dubái
El proyecto incluye aproximadamente cuatro kilómetros de muelles.
Se han aprobado las nuevas regulaciones portuarias para Civitavecchia, Fiumicino y Gaeta.
Civitavecchia
Se ha aprobado el acuerdo de procedimiento con Interminal en Gaeta.
Kotug adquiere una participación mayoritaria en Vortex Offshore.
Róterdam
La empresa, con sede en Dubái, presta servicios marítimos a la industria offshore en Oriente Medio.
Más de 1.900 millones de euros en España para mejorar las conexiones por carretera y ferrocarril entre puertos.
Madrid
Las autoridades portuarias aportarán 875,1 millones de euros.
Attica Holdings vendió el buque ro-pax Levka Ori por 8,3 millones de euros.
Kallithea
El ferry fue construido en 1987.
El servicio ro-ro Trieste-Damietta de DFDS pasará a ser quincenal a mediados de octubre
Copenhague
Insertar un segundo buque en la ruta
La Academia Italiana de la Marina Mercante incrementa su cooperación con el puerto de Durres.
Génova
Se ha firmado un memorando de entendimiento.
PUERTOS
Puertos italianos:
Ancona Génova Rávena
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Liorna Taranto
Cagliari Nápoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venecia
Interpuertos Italianos: lista Puertos del mundo: Mapa
BANCO DE DATOS
Armadores Reparadores navales y astilleros
Expedicionarios Abastecedores de bordo
Agencias marítimas Transportistas
MEETINGS
La cuarta edición de la Green Logics Expo arranca mañana por la mañana en Padua.
Padua
Contará con la participación de más de 300 expositores y la celebración de 30 eventos de conferencias.
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
››› Archivo
RESEÑA DE LA PRENSA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Reseña de la Prensa Archivo
FORUM de lo shipping y
de la logística
Intervento del presidente Tomaso Cognolato
Roma, 19 giugno 2025
››› Archivo
El viernes se presentará en Livorno un libro sobre la historia del sistema portuario toscano.
Livorno
Comparación de los actores portuarios: desde las reformas de la década de 1990 hasta los retos del futuro.
Suardiaz recibe un buque transportador de automóviles propulsado por GNL con capacidad para 5.000 vehículos.
Madrid
Se espera un segundo buque PCTC a mediados de 2027.
Hapag-Lloyd eleva aún más sus previsiones para 2026.
Hamburgo
La fuerte demanda y el aumento de las tarifas de flete al contado están impulsando a la empresa a incrementar significativamente sus previsiones de EBITDA y EBIT.
La reunión pública de UNIPORT se celebrará en Roma el 6 de octubre.
Roma
Debate sobre la reforma portuaria y otros aspectos relevantes del sector.
Tarros y Nurminen Logistics lanzan un nuevo servicio intermodal escandinavo-mediterráneo.
La Spezia/Helsinki
La ruta terrestre conecta Örebro, Parma y La Spezia.
Proyecto piloto para la producción y el uso de hidrógeno verde en el puerto de Savona.
Savona
Paroli (Autoridad Portuaria de Liguria Occidental): se ha identificado una zona portuaria para realizar trabajos.
Se ha colocado el primer cajón del rompeolas que protege la planta de regasificación frente a la costa de Rávena.
Rávena
La obra marítima tendrá una longitud aproximada de 900 metros.
Fincantieri y PT PAL firman un acuerdo para la modernización de un buque de la Armada de Indonesia.
Trieste
Esta es la unidad "Kri Sriwijaya" (antes "Giuseppe Garibaldi")
En Italia, la economía azul tiene un valor de 225 mil millones de euros, y solo la industria náutica supera los 10 mil millones en exportaciones.
Roma
La iniciativa Focus On de SACE se presentó en el Salón Náutico de Génova.
Incendio a bordo del buque ro-ro Blue Carrier 2 de Blue Star Ferries.
Kallithea
Las 29 personas a bordo fueron evacuadas.
Los costes y los plazos para la reconstrucción de los cuatro astilleros de la Armada estadounidense están aumentando exponencialmente.
Washington
Si en 2018 se estimaba un coste de 21.000 millones de dólares y 20 años de trabajo, hoy la estimación es de 200.000 millones y al menos 50 años.
El sector del transporte marítimo se enfrenta a un triple desafío: la descarbonización, la geopolítica y la nueva geografía de la industria automovilística.
Paja
En la Convención Euromed de Grimaldi, el sector se enfrenta a nuevas normativas medioambientales, rutas cada vez más expuestas y el desplazamiento de la producción automovilística hacia el sudeste asiático.
Orizzonte Sistemi Navali firma un contrato de 3.700 millones de euros para la adquisición de dos destructores.
Trieste
El PPA "Domenico Millelire" ha sido entregado a la Armada.
Livorno: El Tribunal Supremo de Casación revoca las condenas en el caso de los muelles de Darsena Toscana.
Roma
El fallo de apelación revocó la absolución dictada por el tribunal y condenó a tres acusados por falsificación ideológica.
El puerto de Rijeka prevé cerrar 2026 con un tráfico récord de contenedores de 800.000 TEU.
Río
Con la nueva terminal en la isla de Krk, el tráfico podría aumentar a 1,7 millones de TEU.
Financiación para la energía eólica marina: Pichetto tranquiliza a Taranto, pero Taranto exige certezas.
Taranto
La financiación para el puerto de Apulia en 2026 se reduce a 13,9 millones de euros. Gugliotti espera una confirmación formal de los recursos restantes en 2027.
Reforma portuaria: La mayoría sigue adelante con Porti d'Italia SpA.
Roma
La Comisión de Transportes de la Cámara rechaza las enmiendas represivas de la oposición.
El puerto deportivo de Gela, Porto Rifugio, ha recibido un dictamen favorable para el dragado de las aguas del puerto.
Palermo
Greenbrier Europe fabricará el sistema de transbordo NIK para TX Logistik.
Troisdorf/Berlín
Permite la carga rápida de semirremolques no aptos para grúa en trenes.
Maersk abre su propio centro logístico en el corazón de Alemania.
Herleshausen
Ubicado en Herleshausen, tiene una superficie de 71.800 metros cuadrados.
La empresa surcoreana HJ Shipbuilding & Construction Co. consigue pedidos para cuatro nuevos buques portacontenedores de 10.100 TEU.
Busan
El contrato tiene un valor total aproximado de 500 millones de dólares.
Partido Demócrata: La reforma portuaria del gobierno allana el camino a la privatización de los puertos italianos.
Roma
Ghio y Misiani: también les quita recursos y habilidades a los territorios.
Autoproducción portuaria: El Consejo de Estado niega la segmentabilidad de la autorización de conformidad con el artículo 16, párrafo 3.
Roma
La autorización "parcial" de Cartour en el puerto de Salerno ha sido suspendida.
El puerto de Miami cierra el año fiscal 2026 con un tráfico de cruceros récord.
Miami
Se ha superado el umbral de los diez millones de pasajeros, en comparación con los 8,56 millones del ejercicio económico anterior.
- Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA
tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Director: Bruno Bellio
Prohibida la reproducción, total o parcial, sin el explicito consentimento del editor
Búsqueda en inforMARE Presentación
Feed RSS Espacios publicitarios

inforMARE en Pdf
Móvil