| |
Ocean House
60 Guildford Street
Chertsey
Surrey KT16 9BE
England
Tel: 01932 560332 Fax: 01932 567084
Email: ap@osclimited.com
|
OCEAN
SHIPPING
CONSULTANTS
Limited |
| |
|
Directors:
Stephen A. Hanrahan
Andrew Pcnfold
|
THE PROPOSED DIRECTIVE
ON MARKET ACCESS TO PORT SERV1CES AND
CONTAINER TERMINAL. OPERATIONS
IN NORTHERN EUROPE
- a critical review
MAY 2005
by:
OCEAN SHIPPING CONSULTANTS LTD.
THE PROPOSED DIRECTIVE
ON MARKET ACCESS TO
PORT SERVICES AND
CONTAINER TERMINAL OPERATIONS
IN NORTHERN EUROPE
1: Introduction & Summary
The European Commission's proposed Ports Directive on Market Access to Port Services ('the Ports Directive') will have far-reaching implications for the ports sector and specifically for the container terminal market1. It is far from clear that the proposed approach is either consistent with other recent judgements from the European Commission or, indeed, that there is any lack of competition in this sector. This paper seeks to summarise the position with regard to the structure of competitive pressures in the market and to establish that (contrary to what may be assumed from the Ports Directive) the regional container terminals operate in a highly competitive market.
The approach taken is to initially establish other relevant opinions that have been issued by the European Commission's Competition Directorate in the field of deepsea and transshipment container terminal operations that are seen to be far from consistent with the Ports Directive.
Having established this inconsistency, the paper goes on to look for potential indicators of any lack of competitive pressures in this sector and to establish that, contrary to the Directive, the container terminal business is highly competitive.
This paper makes the points that:
- The European Commission has already accepted that the correct perspective for consideration of competition in container handling in northern Europe (i.e. the 'market') is between ports and not within ports.
- North European container terminals are productive in contrast to other world port markets and, further, they have become more productive in recent years. This is the result of effective existing competition in these markets.
- Typically, and short term changes notwithstanding, nominal container stevedoring prices have declined sharply in the period since the 1990s. When considered in real terms, this decline has been even more pronounced. This is another manifestation of the competitive structure of the market.
- There are significant scale economies in container shipping. This has resulted in ever higher volumes from major customers in north European ports. Competition for these customers is increasingly between ports and not between terminals in the same port.
- Stevedoring charges represent a small part of total transport costs and are already low in European ports in comparison with other major markets. It is unlikely that they act as an impediment to shortsea shipping or that there is scope for them to be significantly lowered,
- Terminal operators have been keen to invest and provide new capacity in most major ports in northern Europe. Difficulties encountered in delivering new capacity have been a function of the planning process (especially with regard to the environmental considerations) and have not been a manifestation of any lack of desire to provide competitive capacity.
|
1 The dominant mode for the shipping of general cargo between ports is the ISO container, with this system being especially important for the longhaul trades. Comparable data is available for container ports and the Commission itself has looked into these markets. Recent policy decisions are thus comparable. |
2: Definitions of Competition in the Container Port Sector
What is the appropriate definition of competition in the front rank container terminal market?
In the view of OSC, competition between container terminals in the north of Europe and, indeed, also in the Mediterranean, comprises overlaying and intersecting hinterlands. In the case of Belgium and the Netherlands there are immediate and direct competitive pressures between terminals in Zeebrugge, Antwerp and Rotterdam. It is price, capacity and service issues between terminals in these ports that set the competitive position for the market. In addition, these ports are also competing with terminals in Bremerhaven and Hamburg for major parts of the German market, the central and eastern European countries and northern, Italy. In the case of transshipment, UK and French terminals are also competing for the same business2.
It is far from clear that the number of container stevedores within a specific port is the key determinant of the level of competitive pressures in the market. Indeed, to assume this is to completely misunderstand the structure of the container stevedoring business.
It is our view that the focus for large vessels is competition between ports rather than within ports. This view has been accepted by the European Commission. For example (and most recently)3:
"Container terminal services
- In line with previous merger decisions, the notifying parties submit that the relevant product markets where Hutchison is active is the market for stevedoring services for deep-sea container ships, broken down by traffic flows to hinterland traffic and transshipment traffic. This market definition was confirmed by the market test."
"Container terminal services to hinterland traffic
- According to previous merger decisions, the geographic dimension of stevedoring services for hinterland traffic extends to the UK/Ireland on the one hand, and the Northern Continental ports on the other hand. It was left open whether the catchment area of the Northern Continental ports might be further broken down. The widest realistic range would be Hamburg-Le Havre. This range was supported by most terminal operators in the market test. A narrower range might be Hamburg-Antwerp, This range was suggested by shipping lines in the market test."
- "As the ports of Antwerp and Rotterdam are competing with the ports of Biemerhaven and Hamburg for the German hinterland with its high volumes, the conditions for the port range Hamburg-Antwerp are sufficiently homogenous to assume a single geographic market."
- "The geographic dimension of stevedoring services for transshipment traffic extends to Northern Europe, i.e. all deep-sea ports in the Le Havre-Gothenburg range including ports in the UK and Ireland. This was confirmed by the market test."
The acceptance that competition is between ports in the same defined geographic region cannot be considered consistent with the implication in the Directive that each individual port represents a separate and discrete market. However, this is the opinion that is manifested in the Ports Directive.
|
2 There are numerous examples of major lines switching all, or part, of their business between ports. In the past few years Mediterranean Shipping Co. has switched most of its European hub port business from Felixstowe to Antwerp. Maersk Sealand has relocated business from Rotterdam to Bremerhaven, and there has been continuing competition for various services amongst the major alliances between Antwerp and Rotterdam.
3 Case No. COMP/M.3575-ECT/PONL/Euromax 22/12/2004 |
3: Productivitv Comparisons Between North Eurooean and World Ports
If the regional container terminal sector were not competitive, then it would be reasonable to assume that productivity levels - as measured in terms of facility utilisation - would be poor and that there would be little evidence to suggest that they were improving.
Table 1
North West Europe Container Terminal Productivitv Productivitv 1995-2004
|
Port / Terminal |
1995 |
2001 |
2002 |
2003 |
2004 |
|
TEUs/hectare/annum |
12287 |
14244 |
15530 |
16607 |
18511 |
|
TEU/berth metre/annum |
621 |
760 |
781 |
874 |
973 |
Total for Major North and West European container terminals
Source: Ocean Shipping Consultants Ltd.
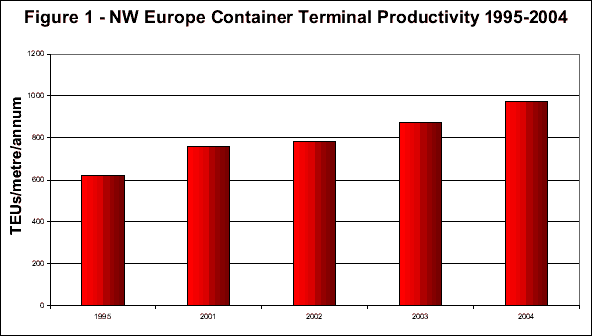
The reality is quite different. Table 1 summarises the development of container terminal productivity in terms of two key (and recognised) quantifiers of utilisation:
- TEUs per terminal per hectare per annum, and
- TEUs per container quay metre per annum,
When averages are calculated for the major terminals in the North Continent and UK markets, it is apparent that the former indicator has recorded an increase of some 51 per cent between 1995-2004 and the latter has increased by 57 per cent. The position for quay utilisation is further detailed in Figure 1.
Table2
Selected Asia and North America Container Terminals/Ports - Productivity
|
|
2000 |
2001 |
2002 |
2003 |
|
TEU per Berth Metre |
|
|
|
|
|
Japan Major Ports |
525 |
434 |
427 |
464 |
|
Total Selected US Ports |
618 |
636 |
670 |
711 |
|
Major NW Europe Ports |
725 |
760 |
781 |
874 |
|
Total Selected Asian Ports |
1071 |
933 |
974 |
1049 |
|
|
|
|
|
|
|
TEU per Hectare |
|
|
|
|
|
Japan Major Ports |
14605 |
13077 |
12709 |
13595 |
|
Total Selected US Ports |
9362 |
9624 |
10057 |
9947 |
|
Major NW Europe Ports |
13850 |
14244 |
15530 |
16607 |
|
Total Selected Asian Ports |
28328 |
25810 |
26812 |
28668 |
Source: Ocean Shipping Consultants Ltd.
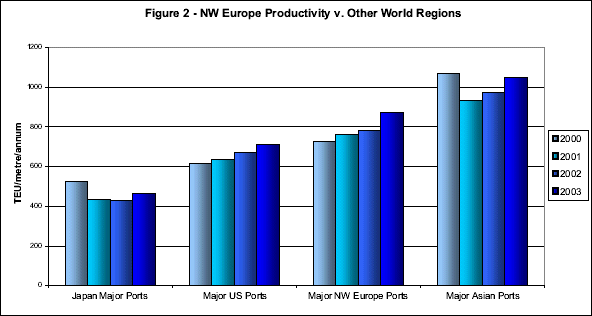
It is also relevant to contrast the current level and development of terminal productivity with the situation in broadly comparable regions in the world. Local conditions always make direct comparisons with other port markets complicated. However, Table 2 summarises the position between 2000-2003 for major ports in Japan, typical high volume ports in the US and the overall average noted in Asian ports as a whole. The development is also detailed in Figure 2.
It should be noted that:
- North European berth productivity is significantly higher than in major US ports. In 2003, the differential was placed at some 23 per cent. The difference with major Japanese ports is even more significant at around 88 per cent. These regions are at broadly similar stages of economic development and containerisation is well established in all three markets.
- Average utilisation is somewhat lower than in the major Asian ports as a whole. This follows from the different market structure in the region and is not a manifestation of any lack of competition.
In summary, productivity is high and increasing in major northern European container terminals. This is a manifestation of the highly competitive nature of the business, with standards of operation forced upwards by the requirements of the shipping line customers. It cannot be said that productivity in the region is a manifestation of any lack of competitive pressures.
4: Price Trends in the European Port Market
Another symptom of an anti-competitive situation in a market would be the maintenance of high and increasing prices. Attention is now turned to whether this is the situation manifested in the north European container port market.
Definition of pricing in these markets is highly complex. Published tariffs provide a starting point but there are significant discounts available for high volume and favoured customers. In addition, shifts in exchange rates also complicate the analysis. However, OSC have been analysing this market in some detail since the early 1990s and, although there are a number of sub-regional markets, in terms of pricing in north Europe the position for the centrally important Benelux region is summarised in Table 3. These are the handling prices charged per container for high volume line customers over the period quantified in terms of US dollars per move (in order to eliminate exchange rate issues over the earlier years). A weighted average of rates charged at the major deepwater terminals at the Delta in Rotterdam and on the River Scheldt in Antwerp have been selected as offering a typical 'marker' price for this activity over the period.
Table 3
Handlinag* Charges for North Continent Import/Export Containers 1994/2004
- US dollars per container
|
|
1994 |
1995 |
1996 |
1997 |
1998 |
1999 |
2000 |
2001 |
2002 |
2003 |
2004** |
|
Total Built-Up Charges |
|
|
|
|
|
|
|
|
|
|
|
|
Zeebrugge |
90.07 |
80.77 |
83.96 |
83.90 |
84.45 |
78.39 |
68.45 |
57.00 |
57.20 |
58.50 |
71.92 |
|
Antwerp - Inner |
90.78 |
89.15 |
88.05 |
81.95 |
80.57 |
74.93 |
67.99 |
63.15 |
64.00 |
66.20 |
75.34 |
|
Antwerp ' Scheldt |
110.13 |
109.45 |
105.33 |
104.98 |
105.07 |
101.02 |
94.20 |
91.20 |
92.00 |
94.50 |
109.20 |
|
Rotterdam - Delta |
149.72 |
145.65 |
137.82 |
134.00 |
131.58 |
122.49 |
110.87 |
98.50 |
98.00 |
101.00 |
112.50 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Average (Weighted) Charges |
|
|
|
|
|
|
|
|
|
|
|
|
Antwerp Scheldt & Rotterdam Delta |
142.50 |
139.79 |
129.98 |
127.28 |
126.98 |
113.71 |
104.00 |
95.08 |
95.31 |
98.19 |
111.11 |
* - from vessel to leaving/arriving at terminal
** - increase primarily due to exchange rate moves
Source: Ocean Shipping Consultants Ltd.
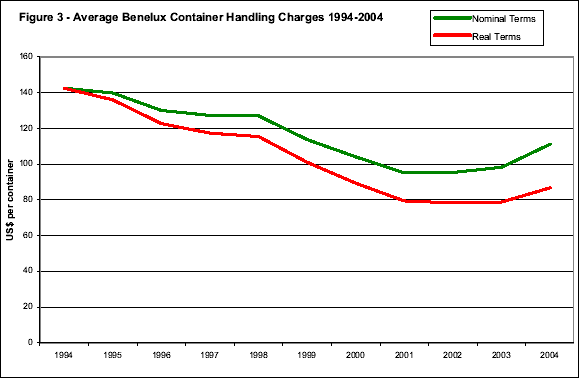
In nominal terms this marker price declined by some 33 per cent between 1994-2001 and has since recorded a limited recovery. The greater part of the recovery over 2003-2004 was the result of the decline in the value of the Dollar against the Euro over the period. In real terms, the level of increase has been moderate and has followed from the congestion that has been noted. This congestion has stemmed from very high demand growth and planning delays constraining the addition of further capacity.
The true extent of this decline has actually been more pronounced. The period has witnessed continuing general inflationary pressures and this has further undermined the level of prices in real terms. Figure 3 includes the impact of the CPI deflator on recorded prices and, from this perspective, the decline between 1994-2001 was even more acute - over 44 per cent. Indeed even after the impact of the post 2001 recovery is included shipping lines are currently paying only 61 per cent (in real terms) of the prices they were paying in 1994.
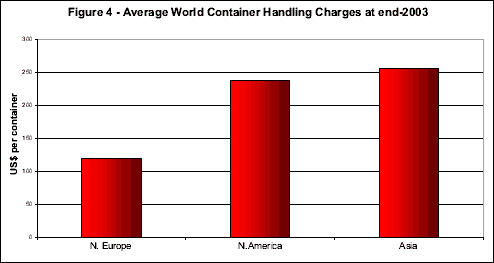
In order to place this in some further perspective, a comparison between prices charged in major north European ports with those in other trading zones has been prepared, and the situation for specific ports is summarised in Table 4. Data has been selected on the basis of relatively high volumes, common-user demand base and actual data availability. The result is a partial but realistic view of the handling prices in the regions under review. A simple average has been derived for the ports in each region.
The following important conclusions can be drawn from this data:
- Although there is a range of container handling prices noted in ports in the UK and the North Continent, there is a clear similarity between prices in, say Southampton.. and Felixstowe, Antwerp and Rotterdam or Bremerhaven and Hamburg. There is clearly a competitive mechanism between ports in these sub-regions.
- Overall, prices are significantly lower than those charged in North America (by around 50 per cent) and even lower in contrast to the position in the major listed Asian ports - around 53 per cent cheaper.
- Even the limited upturn in prices noted over 2004 will not have significantly impacted on these differentials.
The overall conclusion must be that the current system for container terminals in European ports has delivered very low container handling prices and that these have demonstrated a period of significant decline over the period since the mid-1990s. Only a restriction on the ability of terminal companies to proceed with their expansion plans (as a result primarily of the environmental restrictions) has had any impact on this situation. When viewed from the perspective of users of the terminals, the current competitive market structure has delivered very low prices.
The situation is further detailed in Figure 4.
Table 4
Containers Loaded on Vessels end 2003
- US$ per full container
|
|
|
Basic Handling Charge |
|
Asia |
Hong Kong (Kwai Chung) |
243.27 |
|
Singapore |
93.62 |
|
Tokyo |
283.70 |
|
Kobe |
303.63 |
|
Nagoya |
306.03 |
|
Yokohama |
304.34 |
|
Average |
255.77 |
|
N.America |
Los Angeles/Long Beach |
281.00 |
|
Seattle |
234.50 |
|
Vancouver |
178.95 |
|
New York |
253.00 |
|
Hampton Roads (Virginia) |
244.00 |
|
Average |
238.29 |
|
N. Europe |
Felixstowe |
123.38 |
|
Southampton |
127.69 |
|
Le Havre |
129.50 |
|
Antwerp (Scheldt) |
94.50 |
|
Rotterdam (Delta) |
101.00 |
|
Bremerhaven |
131.20 |
|
Hamburg |
133.40 |
|
Average |
120.10 |
Source: Ocean Shipping Consultants Ltd.
5: Scale Economies in Container Handling
The Ports Directive calls for the operation of multiple stevedoring companies for each business sector (including container handling) in each port. This is misguided. In order to provide a significant contribution to the North European container port market it is necessary that a major port provide sufficient capacity to attract, adequately service and maintain large volume shipping line customers. The consolidation of the customer base - together with increasing trade volumes - means scale economies are increasingly important.
Any insistence that more than one operator would be a requirement for a single port would effectively - mean that secondary ports would be excluded from the deepsea container handling market.
The rationale for the requirement for a large capacity terminal is summarised from the following perspectives:
- Market considerations;
- Commercial considerations;
- Logistics considerations; .
- Operational considerations;
- Environmental Considerations..
Market Considerations
The past few years have seen a process of concentration in ownership of container shipping lines and have also seen the development of relatively long-lasting consortia between some of the major shipping lines. When these trends are considered in conjunction with the steady increase in vessel sizes that has been recorded, it is apparent that the size of stevedoring contracts has increased sharply.
Table 5 presents a summary of the volumes of containers handled at major terminals in Antwerp and Rotterdam in 2002. At Antwerp, the largest customer is currently MSC, which shipped some 1.5m TEU via HNN terminals in that year and has since expanded further. In addition, other major lines include the Grand Alliance members and also CP Ships. In both cases, demand is currently approaching 0.5m TEU per annum and will continue to expand. The same position is noted at Rotterdam, where the Grand Alliance accounted for more than 1m TEU in 2002 and Maersk Sealand shipped more than 0.6m TEU via its own terminal in the port.
The process of concentration that is underway in container port operations is also a very important trend. The market share of major customers in the ports is increasing, so each terminal has to deal with fewer, much larger, customers in a rapidly expanding market. Table 6 illustrates this trend at Felixstowe, with the market share of the port's top rive customers increasing from 40.3 per cent of total demand in 1995 to 65 per cent last year. This is entirely representative of the position in other major regional ports.
It is apparent from this summary that major lines and groupings require capacities of between 0.5 and 1m TEU per annum at front rank regional container ports (and some generate considerably larger demand). It will be vital for a port to provide the capabilities to handle such demand.
The market is also forecast to expand at growth rates of between 5.4-7 per cent per annum in the period to 2010 and then between 4-6 per cent in the following period. Within this total, the deepsea and transshipment sectors will expand at a considerably more rapid pace. This means that not only will significant initial capacity have to be provided but, also, a port must be able to offer capacity to meet rapidly expanding requirements for large customers.
To insist on the availability of more than one stevedore would compromise the position of ports such as Dunkirk, Zeebrugge and Southampton in the market for deepsea containers.
The service level provided by a port is a function of numerous factors - vessel lime in port, container dwell lime, systems and port efficiency, etc. It is far from clear that the insistence of multiple terminals in a port would have any positive effects on these issues. Clearly, a fragmented container port would; more likely, result in additional port stay costs, higher intra-terminal transit traffic, costs from consolidating full barge and rail loads, etc. This would have the effect of decreasing the competitive position of the port.
Table 5
Container Terminal Volumes for Major Shipping Lines in Antwerp and Rotterdam in 2002
|
Port |
Terminal/Operator |
Customer |
Million TEUs |
|
|
|
|
|
|
Antwerp |
HNN |
MSC |
1.551 |
|
|
CP Ships |
0.374 |
|
|
Maersk-Sealand |
0.130 |
|
|
Delmas OT Africa |
0.139 |
|
|
Hapag Lloyd |
0.128 |
|
|
OOCL |
0.118 |
|
|
P&O Nedlloyd |
0.118 |
|
|
Evergreen |
0.107 |
|
|
United Arab |
0.090 |
|
|
Others |
1.151 |
|
|
Total |
3.906 |
|
|
P&O Ports |
P&O Nedlloyd |
0.204 |
|
|
CMA-CGM |
0.155 |
|
|
Hamburg Sud |
0.065 |
|
|
K-Line |
0.055 |
|
|
Hyundai MM |
0.031 |
|
|
Others |
0.205 |
|
|
Total |
0.715 |
|
|
Others |
|
0.156 |
|
|
Port Total |
|
4.777 |
|
|
|
|
|
|
Rotterdam |
ECT Delta |
Grand Alliance |
1.010 |
|
|
New World Alliance |
0.403 |
|
|
Hapag-Lloyd |
0.201 |
|
|
Hanjin |
0.246 |
|
|
CMA-CGM |
0.129 |
|
|
Others |
0.659 |
|
|
Total |
2.447 |
|
|
Maersk Delta |
Maersk-Sealand |
0.604 |
|
|
Safmarine |
0.085 |
|
|
New World Alliance |
0.150 |
|
|
Others |
0.147 |
|
|
Total |
0:986 |
|
|
ECT Home |
Evergreen |
0.205 |
|
|
Cosco |
0.111 |
|
|
Others |
0.737 |
|
|
Total |
1.053 |
|
|
Hanno/Uniport |
Yangming |
0.135 |
|
|
K-Line |
0.095 |
|
|
Hanjin |
0.085 |
|
|
China Shipping |
0.080 |
|
|
Zim Israel |
0.055 |
|
|
Others |
0.075 |
|
|
Total |
0.525 |
|
|
Others |
|
1.504 |
|
|
Port Total |
|
6.515 |
Source: Ocean Shipping Consultants Ltd.
Table 6
Customer Concentration in a Maior North EuroDean Container Terminal 1995.2004
- '000 TEUs
|
|
1995 |
1996 |
1997 |
1998 |
1999 |
2000 |
2001 |
2002 |
2003 |
2004 |
|
Top Five Customers |
760.1 |
838.8 |
977.2 |
1323.3 |
1544.6 |
1791.6 |
1861.0 |
1825.0 |
1563.1 |
1769.9 |
|
Total Demand |
1884.7 |
2013.9 |
2251.4 |
2461.8 |
2696.7 |
2793.2 |
2732.5 |
2712.9 |
2479.2 |
2722.1 |
|
% Share |
40.3 |
41.7 |
43.4 |
53.8 |
57.3 |
64.1 |
68.1 |
67.3 |
63.0 |
65.0 |
Source: Port of Felixstowe
Commercial Considerations
The costs of developing a container terminal decline on a unit of capacity basis as the facilities increase in size. That is to say, costs are heavily loaded towards the initial quay construction, together with marine works and associated infrastructure investment. The subsequent introduction of further phases of capacity will involve considerably lower costs than the initial phase. In terms of scale economies it is very important to maximise the capacity of the individual terminals. It is, therefore, very important not to unduly restrict the capacity of a particular port by splitting stevedore operations.
Logistical Considerations
Investment in supporting logistics is much easier to justify if the level of container demand is high. If capacity of an individual terminal were to be constrained by splitting operations between stevedores, then it would be difficult to justify large scale supporting logistics investments and significantly higher volumes of containers could be forced to rely on the road network.
Similar considerations also apply with regard to transshipment. A significant 'critical mass' is required if this business is to be maximised. Once again, any reduction in the size of the terminal would limit potential in this business sector. In both cases, large-scale capacity with frequent daily rail, barge and feeder links will be necessary to provide a competitive terminal.
Operational Considerations
It is al so important to maximise capacity of the terminal when the position is viewed from the priorities of operational issues - that is to say, from the perspective of terminal operation. It high capacity equipment is to be installed for ship to shore handling and in the container yard then it will be necessary to ensure high volume handling. Without such levels of demand it will not be possible to benefit from scale economies.
Environmental Considerations
The more individual container terminals there are in a port, then the greater total area must be made available for additional links - e.g. rail terminals, intra-port roads, intra-port rail tacks, internal roads etc. This will have the overall effect of reducing the annual throughput per hectare of a port.
It is obvious that the objective of increasing port market share and facilitating economic growth would be hampered if the Ports Directive were to oblige sub-optimal use of land. This would also have the effect of creating additional noise, pollution, dust generation for a given throughput of containers. This would clearly be inconsistent with other directives of the European Commission with regard to environmental protection.
6: Overall European Distribution Costs
It has been suggested that a lack of competitive pressures in the container stevedore market may be adversely impacting on the development of shortsea shipping. This is not the case. The overall importance of stevedoring in the total containerised transport cast chain has been analysed and the results are detailed in Table 7.
Table 7
Stevedoring Costs in the Transport Chain 2004
- Euro per 40' container
|
|
Shipping
Costs |
Port
Dues |
Stevedore |
Inland |
Total |
|
|
|
|
|
|
|
|
Shanghai to Milan |
|
|
|
|
|
|
via Rotterdam |
722.25 |
21.65 |
113.45 |
745.00 |
1602.35 |
|
via Antwerp |
722.52 |
15.72 |
92.46 |
721.00 |
1551.70 |
|
via Hamburg |
736.04 |
26.08 |
115.16 |
775.00 |
1652.28 |
|
via Gioia Tauro |
599.25 |
12.25 |
102.45 |
835.00 |
1548.95 |
|
Average % |
43.7 |
1.2 |
6.7 |
48.4 |
100.0 |
|
|
|
|
|
|
|
|
Shanghai to Munìch |
|
|
|
|
|
|
via Rotterdam |
722.25 |
21.65 |
113.45 |
704.00 |
1561.35 |
|
via Antwerp |
722.52 |
15.72 |
92.46 |
68500 |
1515.70 |
|
via Hamburg |
736.04 |
26.08 |
15.16 |
680.00 |
1557.28 |
|
via Gioia Tauro |
599.25 |
12.25 |
02.45 |
928.00 |
1641.95 |
|
Average % |
44.3 |
1.2 |
6.7 |
47.8 |
100.0 |
|
|
|
|
|
|
|
|
Shanghai to Vienna |
|
|
|
|
|
|
via Rotterdam |
722.25 |
21.65 |
113.45 |
815.00 |
1672.35 |
|
via Antwerp |
722.52 |
15.72 |
92.46 |
792.00 |
1622.70 |
|
via Hamburg |
736.04 |
26.08 |
115.16 |
685.00 |
1562.28 |
|
via Gioia Tauro |
599.25 |
12.25 |
102.45 |
1015.00 |
1728.95 |
|
Average % |
42.2 |
1.1 |
6.4 |
50.2 |
100.0 |
Source: Ocean Shipping Consultants Ltd.
This analysis summarises the costs of transporting (for example) a container from Shanghai to delivery at several representative major inland European destinations. Costs are summarised for deepsea shipping, stevedoring (at the European end of the chain only), port dues and typical inland delivery costs.
It is apparent that, for the shipment of containers to Milan and Munich, stevedoring charges represent just 6.7 per cent of the total costs of container delivery. For the more easterly markets (in this case represented by Vienna) the importance falls to just 6.4 per cent.
Clearly, the price level for container stevedoring (which has already been demonstrated to be competitive) does not distort the container market.
7: The Availabilitv of Capacitv
Over most of the period since the early 1990s there has been an oversupply of capacity for container handling in northern Europe. Despite this, the major stevedoring companies have invested very heavily in both new capacity and in improving the productivity of existing facilities. The recent congestion at major terminals has been the result of factors that are outside the contral of either Port Authorities or terminal operating companies - principally the environmental framework for project authorisation.
The terminal operating companies have brought forward massive capacity to meet anticipated demand growth. The delivery of this capability has only been obstructed by environmental opposition. To date, the current mechanism for the market has been very successful in delivering required capacity in a rapidly expanding business.
Application of the Ports Directive would severely undermine the system that has provided efficient and modern capacity in line with demand. There are two key threats here:
- The period of the concessions that have been proposed would not be sufficient to allow the adequate amortisation of container terminals and sophisticated container handling systems. It would be very difficult to attract the level of investment necessary for a smooth functioning of the container terminal sector under such conditions.
- The requirement to offer more than one concession would severely undermine the attraction of investment in a new terminal.
There is a clear and immediate danger that the application of the Ports Directive in its current form would undermine the commercial structure of Europe's container terminals. The existing system has been very successful in meeting strategic requirements. If this were to be radically changed, there is a clear threat to the provision of required future capacity.
Given the sheer scale of investment by the private sector that has been undertaken in the past few years - and will be needed to provide required capacity in the future - this could have a seriously negative effect.
8: Conclusion
The North European container port market is highly competitive and free operation of the current system of regulation has delivered a productive and competitive sector that well meets the requirements of European shippers. The major container terminals are productive and offer a low cost service to enable the functioning of the European economy and the Internal Market.
The system has also facilitated the mix of public and private funding that has been required to modernise and expand the port sector. The Ports Directive as currently configured would prejudice this achievement.
The container terminal system is effective and - as has been recognised by the Commission - there is significant competition between ports for this business. The Ports Directive is not appropriate to the efficient functioning of the container terminal sector.
Although this Report has focussed on the container port market, as comparable indicators are readily available, there is no reason to believe the competitive situation differs in other market sectors.






 - Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA


