testata inforMARE página de inicio
Cerca
07 de noviembre de 2026 - Año XXX
Periódico independiente sobre economía y política de transporte
15:34 GMT+1
LinkedInXFacebook
FORUM de lo shipping y
de la logística


Shipping and Shipbuilding Markets in 2004

I N D E X


The containership market in 2004


Huge orderbook 
Charter fortunes 
The charter market 
Slot charters follow the trend
Long term charters
The fleet
The operators
The second-hand market


After the 2001 traumas, the year 2002 was a year of convalescence and the full health was restored in 2003. As for 2004, it has been the year of the superlatives. It has witnessed a shipping boom unseen since the early 1970s oil-based boom.

This time, the international trade is sitting on a much larger base than 35 years ago, both in commodity variety and in geographical pattern. One country has however become an essential wheel: China. It is estimated that it is at the origin of one third of the world trade growth last year.

With its economy growing at some 9 % a year and containerised exports reaching a 30 % annual increase, China is itself at the origin of the containership shortage and the concomitant unprecedented levels of charter rates. But China is not alone to fuel the shipping frenzy. First, and it is important, it is inseparable from the purchasing power of the USA and of Europe. Second, there are other countries which are also witnessing high levels of exports, such as India, Thailand, Vietnam and Chile.

The rise of the Euro against the US Dollar and Asian currencies has also implications on the containership demand. It makes Asian products, and especially Chinese ones, cheaper for Europe. All along the year, volumes have soared on the Far East-Europe route, which needs more ships than the Asia-US route because of the longer distances.

Shipowners, liner operators and port operators have been taken by surprise by this surge. They can hardly cope with the volumes. Ships are full to capacity out of Asia and there are not enough of them to scoop up all the boxes that flow out from this continent. The congestion of terminals, especially in Europe and the US, compounds the problem, as they cause delays to busy ships and disrupt the tight schedules of usually well oiled weekly loops. This is a challenge for 2005.

In order to save ships, liner operators have rearranged loops and have cut capacity on the comparatively stagnant transatlantic trade in order to send ships on busiest routes. The optimisation of a number of services has also led to a better overall filling ratio, especially at each end of the loops (even if it means filling with empty boxes, which cannot be discounted as they have to be repositioned in one way or another).

Owners of hired container tonnage are rewarded above all expectations, with charter rates which are 50 % higher than the historical peaks. Leading liner operators have anticipated a further rise in demand for 2005 and beyond by chartering ships for periods much longer than usual and have committed themselves in huge newbuilding programmes.

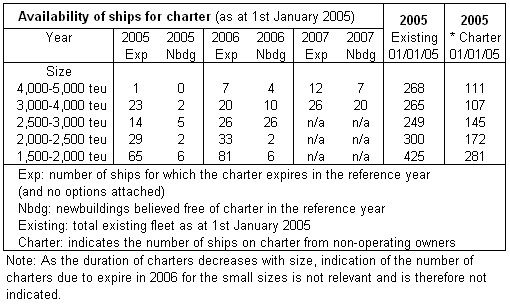
During the second half 2004, there has been intense chartering activity for ships to be delivered in 2005 so that the pool of ships left available has shrunken fast, which could in turn lead to a further round of charter rate rises once the Chinese New Year festivities (February) end.
 

Huge orderbook matches strong trade growth

In early 2005, the cellular ships orderbook stood at 3.9 million teu, representing 53 % of the existing fleet. As big as it is, it does not seem excessive, although it looks like somewhat on the high side, especially for the year 2007. The huge influx of capacity could reasonably be absorbed by the bullish international trade, itself supported by a strong world economic growth.

The world GNP growth has reached around 4-4.5 % in 2004 (against 2-3 % for the long term historical average). Although a slight softening is expected in 2005, the GNP growth should remain above the historical average, and this performance could be repeated in 2006, in the absence of unpredictable events.

As for the international trade, it is estimated to have grown by 7 % in US$ terms during 2004 (against 4-5 % for the long term average). Alas no figures are available in volumes, as it is difficult to assess because of the wide variety of goods.

The observation of long term trends shows that the cellular fleet has grown, roughly, twice as fast as the trade growth. It means that if the bullish trade growth of 7 % recorded for 2004 is to be prolonged during the next two or three years, then it will generate containerised volumes needing to be moved by a fleet growing at 14 % per annum. This is precisely the rate at which the fleet is expected to grow during the next three years, according to BRS-Alphaliner forecast.

Even in case of a softening, the supply-demand ratio of containerships is to remain on the owners side, at least in 2005 and 2006, because of the catch up effect: the shortage which has developed in 2004 must be compensated by deliveries higher than the natural growth.

Given this, the capacity coming on stream should be swiftly absorbed by the transportation demand during the coming months, while a return to a balanced supply-demand ratio could occur in 2006. This should mark a turning point in box rates and charter rates.

The situation in 2007 and beyond is another matter. Some forecasters say that the world economic and trade growths are to remain sustained for the remaining years of the decade, although not at 2004 levels as a softening is expected. The question is: what amplitude will take this softening ? The supply-demand balance for 2007 is thus difficult to assess. Trade growth should remain however higher than the historical average and it is a reasonable bet.

As for 2008-2009, the orderbook has yet to be filled in. So, orders of containerships for these two years may flow in the coming months. Assuming that a 6 % growth in trade is maintained, almost 1.3 million teu should be delivered in 2008 and 1.45 million teu in 2009 only to maintain the equilibrium.
If the omens for the second half of the decade are good, a number of worries must not be overlooked, which could affect the container shipping market. They are :

  • the weakness of the US dollar and uncertainties on exchange rates,
  • a possible hard landing of the Chinese economy,
  • a slowdown in the US consumption of imported products due to a weak dollar combined with possible interest rate increases.

More immediate and foreseeable, problems will affect container shipping in 2005 :

  • the shortage of cellular ships,
  • congestion in ports, leading to delays, accentuating the ship shortage,
  • strain on inland transportation networks.
Charter fortunes

Operators are living a strange paradox as they are rivalling to fix ships at peak rates for periods of three or four years, without knowing what the future has in store. Actually, the charter market is not led by demand alone as far as long term expectations are concerned. It is also propelled by skilled operators who play the shortage game, locking up charterers for years against discounts on rates. These discounts remain somewhat limited when one considers the progression of charter rates over the past two years.

With ships sometimes hired at twice their total operating costs (including repayment of capital), owners enjoy an unprecedented situation since container ships started to be offered for charter, some 35 years ago.

Owners of containerships derive profits which are reminiscent of those accumulated by oil tanker owners in the early 1970s (Onassis, Niarchos, YK Pao, CY Tung and a crowd of other more or less known names).

Indeed, a B-170 locked for three years at $ 27,000 per day will raise enough profit to order a brand new ship of the same size!

With this in mind, it is not surprising that charterers look at buying ships. But with exceptional returns expected on hires, sellers' conditions defy gravity and buyers think twice before taking the plunge. Over the last 12 months, prices of second-hand ships have roughly doubled!

Only a few operators have taken steps in order to be less dependent on chartered ships. It concerned mostly MSC and, to lesser extent, CMA CGM. Both have bought second-hand ships as well as existing newbuilding contracts. Far behind, PIL and Simatech have also bought second-hand tonnage. In another deal, Zodiac Maritime has bought eight Panamax containership contracts for assignment to the associated company Zim (which has sold ships as well).

Although there is a trend among operators to order tonnage in their name, they still rely heavily upon non operating owners, which have relentlessly continued to book ships all along the year.

There has been indeed a significant regular drop in the share of chartered ships in the cellular ship orderbook, from 63 % in January 2004 to 52 % January 2005. The lion's share of this reduction concerns the VLCS orderbook: their chartered component has shrunk from 58 % to 36 % (thanks, for a great part, to MSC buying or exercising purchase options on chartered units).

Conversely, existing ships have been sold to non operating owners. P&O Nedlloyd has sold en bloc 14 Panamax, while Zim has sold five 3,000 teu units and Hanjin five 4,000 teu ones. All these ships were sold with charters back to the sellers. However, these deals have more to do with financial engineering than with market play.

These diverging moves led actually to a slight increase in the chartered component of the existing cellular fleet, which stands at 47.4 %, against 47.0 % one year ago. German owners continues to dominate the charter scene, as they control 63 % of the chartered fleet, dwarfing Greek owners (11.5 %) and Japanese owners (7.2 %).

A few operators are however taking advantage of peak charter rates. As strange as it seems, they have been accepting, if not actually welcoming, ever increasing rates for longer and longer periods throughout the year. Maersk Sealand, MSC and CMA CGM have been keen rivals in this race to land as many possible ships, at the expense of others, who are either hesitant or simply do not have a sufficiently strong financial base to follow.

These three carriers have swooped on as much ships as they could (not to mention their unceasing order waves of newbuildings) and are thus in a position to strongly improve their market share.

Actually, with these peak charter rates, we are on the eve of a new era of precipitating the concentration of the fleet in a few hands with a new sort of natural selection. This may explain why there has been no hurry in attempts to take control of other operators last year.


The charter market

We had speculated in our last annual report that the highest rates observed in 2003 could well represent the average rate for 2004. Not only they did, but they went much higher!

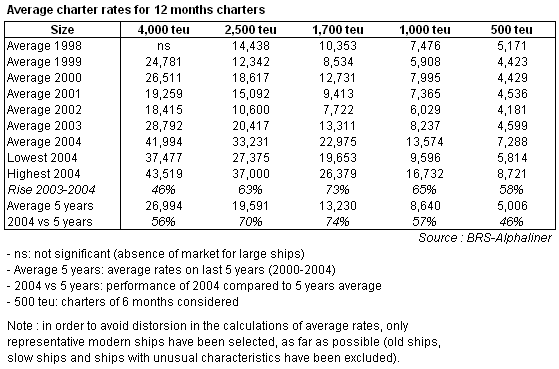
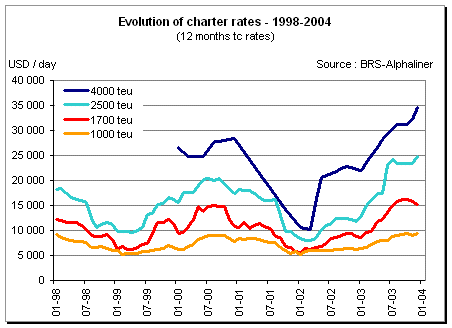
With ships as rare as ever, charter rates have exploded to levels which are 50-60 % above the historical highs observed during the summer 2000. Besides record rates, the year 2004 has been characterised by a lengthening of charter periods and by fixing ships six or twelve months in advance.

These two latter trends have dried up the pool of large ships (both existing and newbuildings) available in 2005. Charterers are now eating into the 2006 available fleet, and a market for sublets has started to emerge.

The rally on the charter market continues and owners are reaping the benefits of the shortage of tonnage. The lack of adequate tonnage to launch new intercontinental loops has thwarted the plans of several carriers.
In December 2004-January 2005, 4,000 teu ships were hired at $ 40-45,000 per day for 12 months period while 2,500 teu ships were valued at $ 35-37,000. Ships of 1,700 teu peaked at $ 27,000 for 4 years periods. 1,000 teu ships were negotiated at $ 18,000 for 6-12 months.

The tonnage scarcity and the high demand on regional and feeder trades have sent rates soaring for smaller ships as well. Cellular ships of 800-850 teu are not cheap, as they reach now the $ 15,000 mark for 12 months (against $ 8,000 end 2003). Modern ships of 500 teu ended the year at $ 9,000 for 12 months (against $ 4,400-4,800 during the three years pre-2004, and for periods of 3 to 6 months).

If top rates are good news for owners, carriers relying only upon chartered tonnage do not share the same enthusiasm. Among them are several niche regional carriers and feeder operators. They use small ships (under 1,500 teu), which until early 2004 could still be hired at fair rates, but have since reached such levels that services will have to be reviewed or cut.
 

Slot charters follow the trend

A little spoken aspect of the container trades concern slot charter rates. As ship charter rates have soared, so have slot charters. Some slot chartering agreements are referring to charter market conditions, and the slot charter rates are reviewed at regular intervals. Other ones are fixed for the duration of the agreement which is usually not more than two years.

Slot charter rates can be indexed on ship charter rates as well as other operational costs, such as voyage costs, including cost of bunkers, canal tolls or port dues. As the ship charter rates item is the heaviest one, it is then not surprising that slot charter hires have risen strongly, leading even to the non-renewal of some agreements.

In this period of tonnage scarcity, those who run the ships may find quite profitable to fill them at full capacity and may not wish to offer their precious earning space to others (which are after all rivals), unless they pay the price.

Operators are now very careful when it comes to enter slot exchange agreements with other lines, as they evaluate risks of failure of partners, especially in the case of small operators whose financial standing may not be strong enough to survive the high charter hires.

There has been during the past year a number of changes in partnerships and slot buyer participation, which may have been caused by tensions created by space shortage on a background of ship shortage and of peak charter rates. On the other side, several operators are teaming up to launch new services with chartered ships, thus sharing the burden of expensive charter hires while being able to offer the needed weekly frequency. Such a way of doing business is of course not new, but it is exacerbated by current market conditions.


Long term charters dominate the market

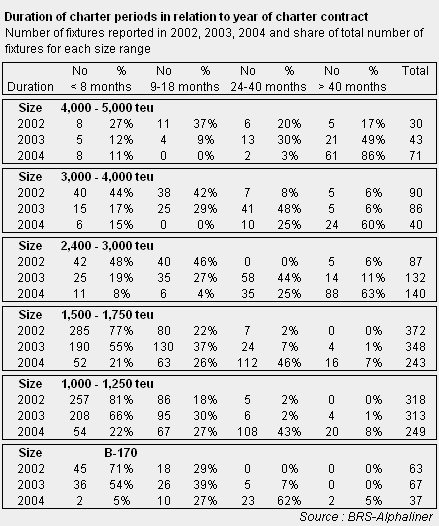
Periods of four years and more for 4,000-5,000 teu ships accounted for 86 % of the reported fixtures in 2004, against 49 % in 2003 and 17 % in 2002, according to a BRS-Alphaliner analysis. Smaller ships have also been fixed for much longer periods than the usual 12 months. Periods of 24 to 40 months for 1,500-2,000 teu ships accounted for 46 % of the reported fixtures in 2004, against 7 % in 2003 and only 2 % in 2002. The accompanying table details how the duration of charter periods evolved from 2002 to 2004.


The fleet

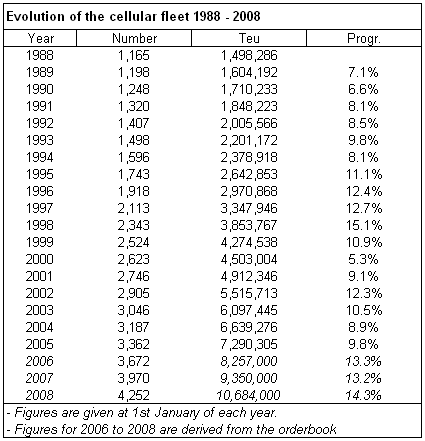
At 1st January 2005, the cellular fleet reached 3,362 ships for 7.29 million teu, in progression of 9.8 % on 12 months, a relatively modest increase as the average annual progression during the past 10 years has reached 10.7 %. The cellular fleet accounts for 89 % of the total fleet deployed on liner trades in teu terms.

The containership fleet counts 49 units of more than 7,500 teu and there are 165 more of these giants on order, some of them reaching the 10,000 teu mark. By the end of 2007, there will be enough of these leviathans to run 15 Asia-Europe and 15 Asia-US loops.
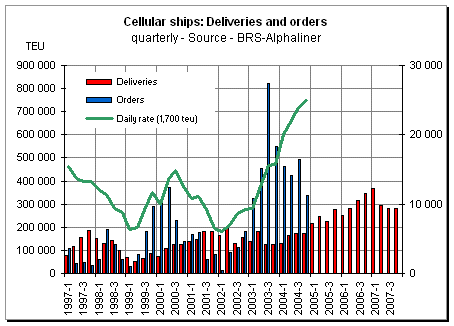


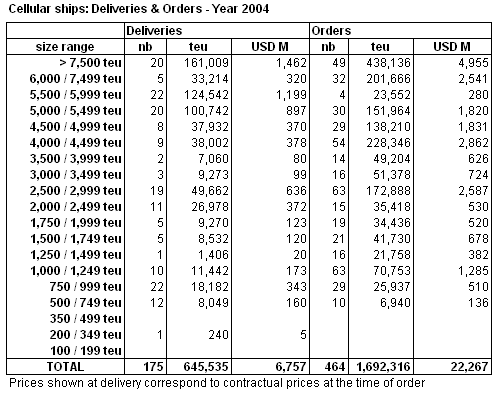
2004 deliveries stood at 175 ships for 645,000 teu (against 177 ships for 575,000 teu in 2003). Orders stood at 464 ships for 1,692,000 teu, which is significantly less than the record 520 ships for 2,123,000 teu ordered in 2003.

The total value of cellular ships ordered in 2004 reached almost $ 22.2 billion (using conversion rates at time of order), a figure similar to 2003, reflecting the steep rise in newbuilding prices ($ 13,150 per teu instead of $ 10,350 per teu in 2003 - raw figures unadjusted for capacity).

The total orderbook reaches 3.9 million teu in early 2005, representing 53 % of the existing fleet. It is dominated by large ships, with ships over 4,000 teu accounting for 74 % of the total orderbook. As for deletions, only five ships for 2,450 teu were sold for scrap last year.

The teu capacity which will enter the market during the three years 2005, 2006 and 2007 corresponds to 47 % of the existing fleet. In other terms, the fleet is to rise by almost 14 % per year, well above the 10 % average observed during the past 15 years. The cellular fleet is expected to reach 10.8 million teu in January 2008 (assuming no scrapping)


The operators

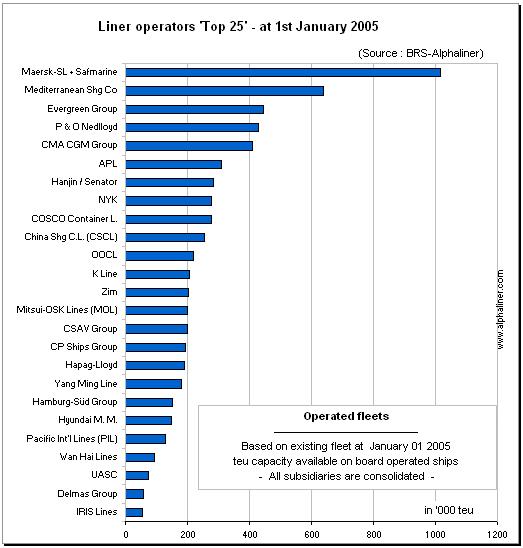
From 1st January 2004 to 1st January 2005, the combined fleet of the Top 25 carriers has grown from 5,955,000 teu to 6,640,000 teu (+11.5 %). Its share of the world fleet deployed on liner trades has risen from 79.6 % to 81.3 % in teu terms, confirming the concentration trend.

The five largest carriers alone operate 39 % of the capacity effectively deployed on liner trades.

The total teu capacity deployed on liner trades has grown by 9.1 % in 2004, reaching 8,168,000 teu st at 1st January 2005, against 7,485,000 teu one year earlier. In deadweight terms, the figure stands at 7.5 %, with 120 million dwt at 1st January 2005 against 111.5 million dwt one year earlier.

These figures take into account all the types of ships deployed on liner trades (cellular, multipurpose, ro-ro). The cellular fleet itself amounts to 7,290,000 teu (it represents 89.2 % of the total teu figure deployed on liner trades).

The two largest carriers, APM-Maersk and MSC contributed to 29 % of the fleet growth in teu terms, with 197,000 teu out of the 683,000 teu added (+101,000 teu for MSC and + 96,000 teu for APM-Maersk).

APM-Maersk became last December the first teu millionaire, as its fleet reached 1,016,000 teu on 1st January 2005. APM-Maersk controls Maersk Sealand, Safmarine, Norfolkline and APMSS-MCC. MSC comes at the second position with 637,000 teu.

These two leaders are however not among the top teu gainers in relative terms. MSC grew by 18.9 % and APM-Maersk by 10.4 %. They are distanced by four carriers (within the Top 25) which have logged growths of 28-33 %: CSAV, CSCL, Yang Ming and CMA CGM. Outside the Top 25, the emergence of two Chinese regional companies is worth noting: SYMS (+24.4 %) and SITC (+20.2 %).
On the mergers & acquisition side, no large mergers or takeovers occurred between rival carriers. The most significant one has been the buying by Costa Container Line of its compatriot Gilnavi. It appears that aggressive carriers (read: potential buyers) have found ways to increase market share in securing as many ships as they can, leaving conservative ones with what is left, i.e. not much choice and pricey.

On the other side, some potential targets have protected themselves from raiders, such as NOL-APL or TUI-Hapag-Lloyd, in steering clear of market listing. Despite this, there is still a choice of first class carriers which remain potential targets: CP Ships, Royal P&O Nedlloyd, Hanjin-Senator and Hyundai M.M.

There has been however important initiatives on the corporate side, such as Temasek Holdings, the Singapore state investment vehicle, taking control of NOL, parent company of APL, in what can be seen as a move to keep at home the Singapore historical carrier, until then listed on the local Stock Exchange. Other large deals concerned the purchase by Royal Nedlloyd of the whole stock of P&O Nedlloyd and the takeover of Zim by the Ofer Group.

CSCL made the news with its listing on the Hong Kong Stock Exchange in June, while intentions to list Hapag-Lloyd faded away as parent company TUI changed its mind and preferred to keep the full control of its Hamburg jewel.

There has been numerous smaller deals, which are summed up in the accompanying table.
 

Operators : transactions and significant moves in 2004

Straight sales & mergers

  • Temasek Holdings (Singapore) has taken full control of NOL, parent company of APL.
  • Royal Nedlloyd B.V. (Netherlands) has taken 100% control of P&O Nedlloyd Containers Ltd (UK) through the purchase of the 50 % stake held by the Peninsular and Oriental Steam Navigation Co (i.e. P&O Group). The resulting company, Royal P&O Nedlloyd Ltd, is listed on the Amsterdam Stock Exchange.
  • The Ofer Group (Israel) has taken control of Zim Navigation, since renamed Zim Integrated Shipping Services Ltd.
  • Costa Container Line took over the deep sea liner trades of Gilnavi srl di Navigazione, the liner arm of the Grimaldi-Genoa branch.
  • The Carlyle Group has sold Horizon Lines to private equity firm Castle Harlan. - STX Corp. (Korea) has bought 67 % of Pan Ocean Shipping Co (Korea).
  • Neptune Orient Lines (NOL - APL parent company), Singapore, agreed to sell its 28.7 % stake in Lorenzo Shipping Corp to National Marine Corp. (both Philippines).
  • Neptune Orient Lines Ltd (NOL) has sold Neptune Associated Shipping Pte Ltd (NAS) (tankers & bunkering).
  • Eimskip (Iceland) and Faroe Ship (Faeroe Islands) have merged.
  • Euro Container Line AS (ECL) (Norwegian company co-owned by Eimskip and Wilson Line) took over Norwegian operator CoNor Line.
  • Rickmers Reederei GmbH & Cie KG (Bertram Rickmers Group), has taken over all of the shares in CCNI GmbH (Deutschland) from Compa''a Chilena de Navegaci'n Interoce'nica SA (Santiago).
  • Egyptian company MISR Shipping has been absorbed by its compatriot National Navigation Co (NNC).
  • Trailer Bridge Inc. (USA) bought 100 % of Kadampanattu Corp. (K. Corp.) from the Estate of Malcom P. McLean (USA)

Transfers and moves within operating groups

  • NYK and its affiliate TSK have decided to spin off their respective domestic liner service operations and related businesses, to set up NYK Line Japan Ltd (effective April 2005).
  • China Shipping Container Lines (CSCL) boosted its share in the Shanghai Puhai Shipping Co, Ltd (SPS) from 50 % to 90 % held by other China Shipping units.
  • Hamburg-S'd abandoned its trade name Ellerman Line.

New operators of liner services

  • Manson Shipping (Taiwan) - services Taiwan-Hong Kong-Vietnam-Philippines.
  • Winland Shipping Co, Ltd (China) - services Weihai-Japan.
  • Dalian Beiliang Logistics Containers (China) - service Dalian-Weihai-Japan.
  • HAL Shipping (Halship) (Canada) - service Halifax-USEC.
  • Delphis NV (Belgium) is incorporated (intra Europe services).
  • AC Forwarding (ACF) and Hudig Veder & Dammers (HVD) form AC Ireland Line.
  • Black Sea Container Shipping Co launches intra Black Sea service.

Cessations of activity in liner shipping

  • CT Navigation (Taiwan) closed its services (Taiwan-Hong Kong-Vietnam-Philippines).
  • Hong Kong Ming Wah (HKMW) has closed its only service (Hong Kong-North China), marketed under the Chiu Lun Transportation name.
  • SPM Shipping (St Pierre & Miquelon) ceased its activity- service Halifax-USEC.
  • Armada Line closes its North Europe-Med service.
  • Blue Container Line (Greece) closed its services (Intra Med and Black Sea).

Significant other moves

  • China Shipping Container Lines (CSCL) has been listed on Hong Kong Stock Exchange.
  • Norwegian shipowner John Fredriksen has bought stakes of 3 to 10% in Hanjin Shipping, Hyundai Merchant Marine, Royal P&O Nedlloyd and NOL.
  • EOX Group Bhd has been renamed HubLine Berhad.
  • The liner division of Unicorn Lines has been renamed Ocean Africa Container Line (OACL).
  • TECO Lines is created by Samskip and Estonian Shipping Co.
  • DAL left the West Africa trades.
  • Steamers Maritime (Singapore - Keppel Group) has sold its whole fleet of ten containerships.
 
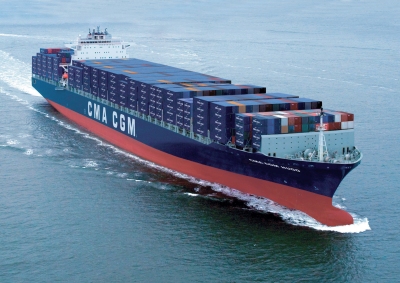
CMA CGM Hugo
100,400 dwt, delivered in 2004 by Hyundai, owned by Conti Reederei, operated by CMA CGM
(Copyright CMA CGM)
 
The second-hand market for containerships in 2004
2004, an exceptional vintage! This is certainly true for almost all shipping markets. The year 2004, with no less than 265 sales of pure containerships (of which 44 resales of ships under construction or ordered) and 126 other ro-ro and multipurpose ships, compared to respectively 181 and 104 ships last year. Nonetheless this leaves a feeling of frustration for a number of buyers who were not able to achieve all their intended investments.

This frustration is caused by the evident lack of tonnage for sale, even at very high prices. Many owners, due to lack of prompt yard slot availability, preferred to go on the charter market for periods sometimes as much as 3, 4 or 5 years, but who can blame them'

A simple example illustrates the mood that reigned throughout the second half of the year: the owner of the m/v 'Lissy Schulte' (B170 - 1,730 teu, built in 1995) refused an offer of no less than $ 30 million and has finally been fixed firm to P&O for 48 months at level of $ 26,500 per day! According to our calculations the result of this charter is equivalent to about $ 35 million. We now understand why this ship has not been sold even at such a price level.

The other specificity of the second-hand market for containerships in 2004 is, without any doubt, the number of sales in the 500 to 2,000 teu size range, and more precisely from 800 to 1,200 teu. There were no less than 15 to 20 potential buyers who found themselves chasing the rare units being put on the market. There was again this year an outright winner in the person of Mr Aponte (MSC, Geneva), with a total of some thirty ships bought in 2004, to which should be added the purchase of some ten newbuilding contracts initially ordered by German owners.

German owners bought some sixty ships. It is interesting to note in this respect that it is virtually impossible to compete with a German buyer on a modern ship offered on the market when it is controlled by German interests. A good lesson in self-protection!

Also, whilst in the past ships already under long-term charter were gaining popularity amongst buyers, this year ships that were "time-charter free" were by far the most sought after. In the absence of charter free tonnage in 2004, a large number of buyers went after containerships still employed up until the end of 2005.

Despite the high prices paid, buyers had to be patient for several months before they were able to benefit from a chartering market for which they hope it will stay at least as good as today's levels. As to liner operators, purchases of this kind proved to be essential once they had to ensure operating the necessary tonnage on their regular services.

The principal "en-bloc" sales which can be reported this year are:

  • 5 x 3,500 teu and 9 x 4,200 teu (14 ships) built in 1991, 92, 93, 94 and 95 from P&O Nedlloyd to MPC Capital for a total of $ 660 million.
  • 4 x 2,824 teu Hyundai contracts for delivery between 2005 and 2006 resold by Erck Rickers to CMA CGM for $ 44 million each.
  • 8 x 4,250 teu Dalian New contracts for delivery between 2006 and 2007 resold by Bertram Rickmers to Zodiac.
  • 7 x 1,538 / 1,658 teu built between 1998 and 2000 by Jiangnan and HDW, from clients of Silver Line (who bought the entire fleet in 2001 for $ 100 million) to MSC for $ 130 million.
  • 10 ships of 369 to 1,012 teu, sold by Keppel Group (Steamers) to Interorient for $ 91 million. 
  • 4 x 5,050 teu, Hanjin shipyard contracts for delivery in 2006, resold by Rickmers to MSC for $ 63.5 million each.
  • 5 x 3,039 teu built between 1990 and 1992 by HDW, sold by Zim to Torvald Klaveness and Icon Capital for $ 35 to $ 38 million each, with a bare-boat charter back to Zim.
  • 4 x 2,394 teu (20 knots) built in 1994 in Spain, sold by Zodiac Maritime to MSC for just over $ 30 million each.
  • 4 x 2,524 teu built by Kvaerner in 2003 and 2004, sold by an Andreas Ugland-associated company to the bare-boat charterer of the ships, Hamburg-Sud, for $ 35 million each.
Number of pure containerships sold by size:
Less than 900 teu: 82 
From 900 to 2,000 teu: 83
From 2,000 to 3,000 teu: 42 
Over 3,000 teu: 58 (of which 28 contract resales)
Total number of ships sold in 2004: 265
Total capacity of ships sold in 2004:  500,145 teu

  Containerships under 900 teu

Together with the normal flow of activity this year, we have seen a search by certain buyers for ships smaller than what they originally needed. Prices for some ships have occasionally doubled between mid-2003 and end 2004. Even ships that can hardly been classified as "suitable" on this market, such as a slow-speed vessels or those with gears unable to perform a standard loading/unloading rate, have found buyers at more than favourable conditions for their owners.

Buyers based in the Far East, Germany and Greece were, in this order, the most active within this size category.

Interorient's deal of buying the feeder fleet of the Keppel Group for $ 91 million fairly well reflects the mood of the market this year. A fleet which has been on the market throughout the whole year 2003 and which was finally sold at the beginning of 2004. Since then, one can estimate the theoretical gain in the value of each ship to be at about 50 to 60 %.

Containerships of 900 to 2,000 teu

This has been by far the most active sector of the second-hand containership market! A cascade of sales, dozens of buyers, ships sometimes for sale, sometimes withdrawn, escalating negotiations with the seller rising his price at each stage of the negotiation'.. in short a happy shambles within the context of euphoric freight rates and second-hand prices.

This situation is particularly true since the summer of 2004. At that time buyers were struggling with the steady disappearance of charter-free ships. The few units still available in 2004 and 2005 will become targets for owners such as MSC, Zim or CMA CGM'

Containerships of 2,000 to 3,000 teu

This sector saw only a small progression this year with some fifteen more ships sold compared to last year. At the end of the year owners of newbuilding contracts for delivery in 2005 did not hesitate to ask for ' 45 million ($ 60 million) for a gearless ship of 2,700 teu. In short, the lack of tonnage explains some excess in ship's valuations.

Containerships of 3,000 teu and more

Fifty percent of the 58 deals done this year were newbuilding contract resales. This segment of the market was dominated by Zodiac, MSC and above all the German KGs, always very keen about ships of this size, which combine several favourable factors to investors: 

  • a market predominately stable and secure,
  • a popular size and already well-known in Germany, thus a relatively good market knowledge by investors,
  • a satisfactory "liquidity" of the assets and reliable charterers.

One of the rare pure second-hand operation done this year was the one involving the 3 ships of 3,187 teu controlled by Talcar, Israel, built respectively in 1986, 1986, and 1988 at a price of $ 80 million en-bloc with delivery in 2005 to MSC.
 

Demolition

Out of the 52 ships demolished in this category, only 5 were pure containerships, the latter totalling a mere 2,450 teu. The others were either multipurpose or conventional cargo ships. This low scrapping level is a direct consequence of the firmness in the freight market. Scrap metal price levels have been hovering in the region of $ 400 per lightweight ton
 

Conclusion

The world cellular fleet has increased this year by 9.8 % to reach 3,362 ships (7,290,000 teu). This evolution is in line with the annual average growth of the past 15 years. However we already know by now that the shipyards will deliver a capacity of 47 % of the existing fleet in the course of the next 3 years. This represents a growth of about 14 % per year!

The demolition market usually hits ships of 27 years or more on average, which in the best case will only shrink the world fleet by 3.2 % of its current capacity.

The question is therefore: will Asia, and especially China whose strong export industry has continued to expand, be able to absorb this additional tonnage? A large number of players, both on the industrial as well as the shipping side, believe that it will. It is however a very complex exercise to predict the strength of such a market. As we all know, to simply maintain it at its present levels, it depends upon China and its neighbours, whose growth in turn seems to be in their own hands.
 

›››Archivo
DESDE LA PRIMERA PÁGINA
Alfa Laval adquiere Navtor por 700 millones de dólares.
Lund/Egersund
La empresa noruega que ofrece soluciones digitales para el transporte marítimo se integrará en la división Ocean del grupo sueco.
Boluda Towage adquiere la empresa holandesa de remolque Muller Dordrecht.
Dordrecht/Valencia
Cuenta con una flota de 16 remolcadores y ocho barcazas.
El mes pasado, el tránsito de buques por el Canal de Suez aumentó un 32,1%.
El Cairo
Crecimiento del +86,8% en tonelaje y del +94,1% en derechos de tránsito.
El ferrocarril, el espacio y el medio ambiente figuran entre las prioridades que surgen de las reuniones sobre el nuevo Plan de Ordenación Portuaria para los puertos de Génova y Savona-Vado.
Génova
La primera fase del proceso de consulta del AdSP ha concluido con 65 audiencias y la participación de más de 120 partes interesadas.
Fincantieri firma acuerdos con JA Solutions, Navantia y Naval Group.
París
Colaboración intensiva con la empresa danesa en el campo de los sistemas modulares y en contenedores avanzados para unidades navales reconfigurables.
Menos contenedores, más ingresos: la división marítima de Maersk crece al ritmo de las tarifas de flete.
Copenhague
En el tercer trimestre, los volúmenes cayeron un -0,8%, pero las tarifas y la congestión elevaron el EBIT de Ocean a 2.600 millones.
De Egipto a Marruecos, pasando por Gioia Tauro: ¿el ETS desvía los contenedores a puertos fuera de la UE?
Bruselas
Un estudio promovido por Assarmatori detecta indicios de transferencia ya en marcha y exige correcciones.
ONE buques transportaron volúmenes récord de contenedores en el tercer trimestre.
Singapur
Los ingresos aumentaron un 36,5%. Este desempeño se vio impulsado por la demanda de envíos transpacíficos.
Wallenius Wilhelmsen registra un tercer trimestre con ingresos récord que, sin embargo, crecen menos que los costos.
Lysaker
Ligera disminución en el volumen de vehículos transportados por la flota.
Canal de Suez: Señales de recuperación del tráfico marítimo en septiembre
Ismailia
Sin embargo, las repercusiones de la crisis en el Mar Rojo persisten.
En Taranto, la crisis del acero sigue lastrando el puerto.
Taranto
El transporte de carga líquida a granel está manteniendo los volúmenes, pero el tráfico general ha disminuido un 5,7 % en los primeros nueve meses de 2026. El tráfico de contenedores sigue siendo volátil.
Aranceles portuarios estadounidenses a buques chinos, coalición comercial pide suspensión permanente
Washington
Cientos de asociaciones han escrito a Greer antes de la fecha límite del 9 de enero de 2027. Entre ellas se encuentra el Consejo Mundial del Transporte Marítimo.
T&E: El ETS debería convertirse en el motor de las inversiones en combustibles sintéticos para aeronaves y buques.
Bruselas
Las exigencias de la organización para la reforma del ETS: más recursos europeos, un fondo específico y subastas bilaterales.
En el primer semestre de 2026, el tráfico de mercancías en el puerto de Livorno cayó un -3,6%.
Livorno
Los puertos de Elba también experimentaron un descenso (-3,3%). El puerto de Piombino, en cambio, se desmarcó de esta tendencia con un aumento del +5,7%.
El volumen de carga disminuyó en los puertos del sur del Adriático durante el primer semestre de 2026.
Bari
El sistema pierde 676 mil toneladas en comparación con 2025, casi todas entre los dos puertos más grandes.
En el tercer trimestre, el tráfico marítimo en el Canal de Panamá se mantuvo estable.
Panamá/Balboa
Sin embargo, el tonelaje de los buques y el volumen de mercancías en tránsito están aumentando.
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
El sistema marítimo de comercio de derechos de emisión (ETS) y FEPORT apoyan las medidas contra la evasión fiscal relacionadas con la carga.
Bruselas
Es la solución más eficaz —afirma la federación de operadores de terminales europeos— para proteger la competitividad de los puertos de la UE.
COSCO Shipping, ingresos +29% y beneficios +82%: el mérito se debe a las tarifas de flete, más que a los volúmenes.
Hong Kong
El mercado transpacífico es el motor que impulsa las cuentas del grupo chino.
Norwegian Cruise Line Holdings registra un aumento en sus ingresos netos, pero una disminución en sus márgenes durante el tercer trimestre.
Miami
APM Terminals firma una nueva fase de expansión para el puerto marroquí de Tánger Med.
Rabat
Se prevé una inversión de más de 800 millones de dólares para construir 1,2 kilómetros de muelles.
El puerto de Barcelona lanza un proyecto para reducir las terminales de cruceros de siete a cinco.
Barcelona
Revisión de la concesión de Creuers del Port de Barcelona
Boluda y Samskip, una nueva fusión en el transporte marítimo de corta distancia europeo.
Valencia/Róterdam
El grupo español ha firmado un acuerdo para adquirir todas las actividades del grupo holandés y ampliar su plataforma multimodal.
Astilleros indios en la lista de reciclaje de buques de la UE, ECSA pide a los eurodiputados que la aprueben.
Bruselas
Llamamiento para rechazar una moción que se opone a la propuesta de la Comisión.
CVC DIF ha adquirido una participación mayoritaria en el astillero español Cernaval.
Schiphol
La empresa ibérica emplea aproximadamente a 275 personas.
Contship Italia adquiere el grupo Tarros.
Melzo/La Spezia
Todas las actividades y activos que conforman el sistema de servicios integrados del grupo La Spezia cambian de manos.
El crucero residencial de Villa Vie Residences fue suspendido.
Fort Lauderdale/Sihanoukville
La compañía atribuye el encallamiento del buque al aumento del precio del combustible y está trabajando en un plan de reestructuración y recapitalización.
Wallenius Wilhelmsen encarga cuatro PCTC de 9.900 CEU más ocho opciones.
Lysaker
Acuerdo con el astillero chino Jinling Shipyard (Jiangsu)
Royal Caribbean registra ingresos trimestrales récord de 5.590 millones de dólares. Se revisan al alza las previsiones para el año completo 2026.
Miami
EBITDA de 2.530 millones y 2,68 millones de pasajeros en el período julio-septiembre
La seguridad marítima, el sistema de transporte de emisiones (ETS), los pabellones y el empleo son los temas centrales del informe del presidente de Confitarma.
Roma
Zanetti aboga por una alianza europea para la libertad de navegación, un pacto nacional para la transición y menos burocracia para la bandera italiana.
Global Ports Holding firma un acuerdo de concesión para el puerto de cruceros de San Vicente.
Estanbul
El acuerdo tiene una duración de 30 años.
La familia Sunde vende Color Line a Stena.
Gotemburgo
Un grupo sueco de ferris adquiere la mayor compañía de ferris de cruceros de Noruega.
Puertos chinos, la carrera se está ralentizando.
Pekín
Tras 25 años de crecimiento, el tráfico de mercancías está prácticamente paralizado, pero los contenedores siguen batiendo récords.
Lorenzo Sanna es el nuevo presidente de ANPAN
Sestri Levante
Parmigiani: En lo que respecta al Protocolo de Alta Mar, deberíamos retomar la declaración escrita del comandante.
2027 volverá a ser un año récord para la industria italiana de cruceros.
Livorno
Se prevé la llegada de aproximadamente 16 millones de pasajeros, con un crecimiento del +4%.
Reforma portuaria: la Comisión debate la posibilidad de reservar y rechazar únicamente buques.
Roma
La Cámara de Diputados no ha aprobado ninguna enmienda en tres semanas. La única excepción es el personal de la Autoridad Portuaria.
Transporte por carretera, tregua inminente. El gobierno libera fondos para combustible diésel y reformas estructurales.
Roma
Se aprueba un decreto de emergencia con créditos fiscales, prohibición de arrendamiento y protección contra el recargo por combustible.
La flota de portacontenedores y buques de transporte de automóviles de combustible dual supera las 500 unidades.
Washington
Un incremento del 41% en comparación con septiembre de 2025. Las inversiones del sector han superado los 200.000 millones de dólares.
Corredores marítimos verdes: China lidera la carrera.
Llevar a la fuerza
Casi una quinta parte de los proyectos de desarrollo a nivel mundial involucran un puerto chino. El informe del Foro Marítimo Global destaca el combustible y la colaboración como puntos fuertes, mientras que la demanda sigue siendo débil.
En el tercer trimestre, el tráfico de mercancías en los puertos españoles creció un +2,1%.
Madrid
La carga a granel está marcando la tendencia. La carga en contenedores se mantiene estable.
La UE invierte en la revolución verde de los mares.
Bruselas
Desde el amoníaco hasta el e-metanol, desde los transbordadores eléctricos hasta la captura de CO2: proyectos que están transformando el futuro del transporte marítimo europeo han recibido financiación.
Las asociaciones de transporte por carretera piden que se ponga fin a los bloqueos de carreteras en el sur del país.
Roma/Módena
Tras la reunión con Salvini, los sindicatos instaron a Piantedosi a intervenir. Ruote Libere respondió: escuche a los manifestantes, no los reprima.
APM Terminals y Hateco firman un acuerdo para desarrollar una red de terminales de carga ferroviaria en el norte de Vietnam.
Copenhague
La inversión inicial se estima en alrededor de 3.500 millones de dólares.
IFM Investors adquirirá las participaciones de CPPIB y OMERS en Associated British Ports.
Londres
Se ha alcanzado un acuerdo para la transferencia del 63,9% del capital del grupo portuario británico.
Los sectores de transporte marítimo y aéreo, y logística contractual impulsan el tercer trimestre, mientras que el transporte por carretera se ralentiza.
Copenhague
La división de carreteras sufre problemas tras la integración de Schenker.
Descarbonización del transporte marítimo: El Reino Unido debería aprender de los errores de FuelEU Maritime.
Londres
La Cámara Naviera del Reino Unido presenta al gobierno un documento con las lecciones aprendidas de los dos primeros años de aplicación del reglamento europeo.
El puerto de Amberes-Brujas vuelve al crecimiento en el tercer trimestre, con un aumento del 2,5% tras dos trimestres de descenso.
Amberes
Los contenedores, el transporte ro-ro y el transporte de graneles secos están impulsando la recuperación, mientras que el acero y los productos energéticos siguen atravesando dificultades.
Interferry reitera su preocupación por el aplazamiento de la inclusión del transporte por carretera en el RCDE UE.
Victoria
Roos: Las cargas y los desafíos de la descarbonización no pueden ser asumidos por sectores individuales.
El puerto de Trieste se recupera en el tráfico de contenedores en el tercer trimestre, pero el ferrocarril sigue en dificultades.
Trieste
El volumen de líquidos está en aumento.
Tráfico récord de cruceros trimestral en las terminales de Global Ports Holding
Estanbul
Únicamente las cifras en la región del Mediterráneo oriental y el Adriático están disminuyendo.
Rheinmetall confirma su asociación con MSC para la adquisición del astillero rumano en Mangalia.
Düsseldorf
El precio de compra, de aproximadamente 138 millones de euros, será pagado conjuntamente por los dos socios.
Estrecho de Ormuz: Otro fin de semana de ataques a buques
Teherán/Southampton
Primer uso de un cohete antitanque RPG disparado desde una embarcación pequeña.
Puerto de Rotterdam: El tráfico de carga general disminuye en el tercer trimestre, mientras que el tráfico de carga a granel aumenta.
Róterdam
En los primeros nueve meses de 2026 se manipularon 323,2 millones de toneladas (+0,9%).
Nace el Observatorio de Construcción Naval de Liguria: un sector valorado en dos mil millones de euros y que emplea a más de 10.000 personas.
Génova
AdSP, Confindustria Genova y Unione Industriali Savona lanzan un seguimiento permanente del sector
La BPA afirma que el crecimiento del sector de contenedores en el Reino Unido depende de la inversión, no de las fugas de carbono.
Londres
Un informe de la asociación británica refuta al Observatorio Español: el indicador en teu-millas no mide volúmenes reales y amplifica el efecto del orden de los puertos de escala.
El sistema de comercio de emisiones (ETS, por sus siglas en inglés) representa el 10% de las emisiones, pero paga casi el 20% de la factura.
Bruselas
Estudio de ECSA: Los armadores europeos solicitan cuotas triples del SMAP para combustibles y tecnologías sostenibles.
AP Moller Capital adquirirá Portek International Port Group.
Copenhague
Será comercializado por la empresa japonesa Mitsui & Co.
La disputa portuaria entre Washington y Madrid amenaza con convertirse en una guerra comercial.
Washington
La FMC propone un gravamen de 200 mil dólares por viaje a los buques con bandera española y restricciones a la importación de ciertos productos.
Reforma portuaria: la Comisión rechaza los cambios en la gobernanza de Puertos de Italia.
Roma
Ayer, la Comisión de la Cámara de Diputados votó el artículo 9 del proyecto de ley 2925: las enmiendas de la oposición fueron rechazadas; su posterior examen se ha aplazado a otra sesión.
El puerto de Singapur establece un nuevo récord histórico de movimiento trimestral de contenedores (TEU).
Singapur
Las ventas de combustible marino ponen de manifiesto la continua transformación del mercado de combustibles.
Dos buques portacontenedores fueron alcanzados por proyectiles mientras transitaban por el estrecho de Ormuz.
Southampton/Singapur
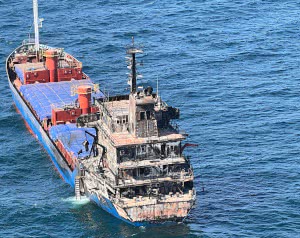
El "GFS Pride" sufrió daños y un incendio a bordo, y posteriormente se hundió.
Ataques a barcos y puertos: el ETF hace un llamamiento a los líderes de la UE.
Bruselas
"Necesitamos acción, no otra declaración de preocupación": el sindicato exige que la seguridad de los trabajadores sea el eje central de la respuesta europea en el Mar Negro.
Según el tribunal de Génova, RINA es responsable del hundimiento del Al Salam Boccaccio '98 .
Génova
La empresa manifiesta su profundo desacuerdo y recuerda las conclusiones de otras investigaciones.
Perú planea un segundo puerto nacional importante
Archivo
El puerto de Corío se construirá en la costa sur del país para servir también a las exportaciones brasileñas.
Los ataques contra barcos en el estrecho de Ormuz y el mar Negro se están multiplicando.
Sofía/Southampton/Nueva Delhi
Dos embarcaciones resultaron heridas en la zona económica especial de Bulgaria.
Fincantieri y Republikorp forman una empresa conjunta para fortalecer la industria de construcción naval de Indonesia.
París
El Propeller Club Port of Sardinia se fundó hoy en Cagliari.
Génova
Es el club número 27 de la asociación nacional, que cuenta con más de 1.600 miembros.
La empresa india Adani Ports adquiere al operador de terminales holandés Evos.
Ahmedabad/Ámsterdam
Transacción por valor de 2.560 millones de euros.
Hapag-Lloyd ha completado la adquisición de una participación del 25% en APM Terminals Maasvlakte II.
Hamburgo
La junta directiva de Interferry ha sido renovada.
Victoria
Nombramientos en la conferencia del 50 aniversario de la asociación en Bangkok.
DIS reporta un crecimiento en sus ganancias durante el tercer trimestre de 2026.
Luxemburgo
Tras el auge del segundo trimestre, la rentabilidad se mantiene en niveles altos.
Arsenio Domínguez seguirá al frente de la OMI hasta finales de 2031.
Londres
El Consejo ha tomado una decisión. El nombramiento debe ser ratificado por la asamblea.
DHL experimentó un crecimiento en el tercer trimestre, impulsado por los servicios de mensajería urgente y transporte de mercancías, que generaron ingresos y beneficios.
Bonn
Ingresos de 22.700 millones de euros (+12,6%) y EBIT de 1.700 millones de euros (+16,2%).
El Tribunal General de la UE ha anulado la retirada del reconocimiento del registro naval ruso.
Luxemburgo
La prohibición de inversiones y la prohibición de transacciones siguen vigentes.
El bioGNL italiano busca hacerse un hueco entre el ETS, FuelEU y los incentivos nacionales.
Rimini
Assogasliquidi solicita procedimientos de certificación más sencillos y medidas para que la producción nacional sea competitiva.
Fincantieri y Leonardo llegan a un acuerdo para reforzar el papel de Orizzonte Sistemi Navali.
Trieste/Roma
Las empresas pretenden consolidar el papel industrial y comercial de la empresa conjunta.
Puerto de Rijeka: Diversas cargas impulsan el avance de Luka Rijeka, mientras que la terminal de contenedores Adriatic Gate pierde terreno.
Rijeka
En los primeros nueve meses de 2026, el tráfico total cayó un -15% hasta los 3,83 millones de toneladas.
Confetra: El gobierno quiere abolir el impuesto sobre las parcelas pequeñas.
Roma
Satisfacción con las decisiones del gobierno en el proyecto de ley de presupuesto.
Se ha establecido una comunidad portuaria de energías renovables en Taranto.
Taranto
Entre los objetivos, destaca el desarrollo del puerto de Apulia como centro energético.
Filt y Uilt, el sistema de trabajo portuario temporal no es anacrónico.
Roma
Definirlo de esta manera —denuncian los sindicatos— significa distorsionar la naturaleza y la función del artículo 17 de la Ley 84/94.
Nuevo récord trimestral de tráfico de mercancías en los puertos albaneses.
Tirana
En el período julio-septiembre, el número de pasajeros disminuyó un -5,4%.
Los beneficios de FedEx están aumentando, pero el beneficio neto cae un 68%.
Memphis
La pérdida de capital no monetaria relacionada con la escisión de FedEx Freight pesa mucho
Kalmar registró un crecimiento del 22% en nuevos pedidos en el tercer trimestre.
Helsinki
Facturación estable. Beneficio neto un 14% inferior.
En el tercer trimestre, las ventas de contenedores producidos por CIMC aumentaron un 30%.
Hong Kong
La actividad comercial se vio impulsada por los contenedores secos (+36%). Las unidades refrigeradas disminuyeron un 28%.
Puertos, nuevas inversiones en Toscana y Cerdeña
Livorno/Cagliari
Se han aprobado los presupuestos para 2027 de las dos autoridades portuarias. Entre los proyectos más destacados se incluyen el muelle de Piombino, las obras en Livorno y los proyectos de dragado y electrificación en los puertos de Cerdeña.
Encontrar personal cualificado en los puertos italianos es cada vez más difícil.
Nápoles
Un análisis realizado por Randstad Research de 13 perfiles profesionales también pone de manifiesto un marcado desequilibrio de género.
COSCO Shipping Ports registra ingresos récord en el tercer trimestre.
Hong Kong
En el período de julio a septiembre, el beneficio neto fue de 102,5 millones de dólares (+3,4%).
Aprobación del presupuesto previsto para 2027 y del Plan Operativo de Transporte (POT) para el periodo 2027-2029 de la Autoridad Portuaria del Sur del Mar Tirreno y Jónico.
Gioia Tauro
El documento de previsiones muestra unos ingresos de aproximadamente 24 millones de euros y unos gastos de aproximadamente 88 millones.
Bongiovanni, natural de Ravenna, ha sido confirmado como presidente del Comité Juvenil de la Federación.
Roma
Renovación de la junta directiva de la federación
Se ha aprobado el Plan Operativo Trienal 2027-2029 para el Sistema Portuario del Adriático Central.
Ancona
Se prevén inversiones por valor de 308 millones de euros, de los cuales 218 millones se destinarán a la región de Las Marcas y 91 millones a Abruzzo.
Se ha aprobado el presupuesto previsto para 2027 de la Autoridad Portuaria de Liguria Occidental.
Génova
El nuevo recargo sobre los productos se pospone hasta 2028.
DP World inaugura un almacén con temperatura controlada cerca de Bolonia.
Bolonia
Superficie de 22 mil metros cuadrados
Saipem gana dos nuevos contratos de perforación en alta mar.
Milán
El valor total de los pedidos asciende a aproximadamente 121 millones de dólares.
Hanwha pone el astillero naval de Filadelfia bajo el control de la División de Defensa.
Arlington
El objetivo es integrar la construcción de buques comerciales y militares.
Los puertos de La Spezia y Carrara aprueban el Programa Trienal de Obras Públicas 2027-2029 y el Presupuesto 2027.
La Spezia
Pisano: PTLP concreto y coherente con los recursos actualmente disponibles.
Concesiones portuarias: El Tribunal Administrativo Regional (TAR) bloquea el aumento de tarifas de 2025.
Roma
Se ha aceptado el recurso presentado por Assiterminal y dieciséis empresas portuarias.
Wärtsilä registra aumentos trimestrales en los pedidos, pero no en el segmento marítimo.
Helsinki
En el periodo julio-septiembre la empresa registró un beneficio neto de 125 millones de euros (-31%).
Montaresi fue nombrado secretario general de la Autoridad Portuaria del Mar de Liguria Oriental por otros cuatro años.
La Spezia
Renovación del mandato a propuesta del Presidente Pisano
Doble ceremonia para dos barcos de Explora Journeys en el astillero Fincantieri en Génova.
Génova
Lanzamiento del "Explora V" y ceremonia de colocación de la primera moneda del "Explora VI".
La empresa italiana CMD pasa a estar bajo el control del grupo emiratí EDGE.
Abu Dabi/Roma
Los primos Mariano y Giorgio Negri conservan una participación significativa.
La Autoridad Portuaria del Tirreno Septentrional presenta el nuevo diseño del puerto de Piombino.
Livorno
Gariglio: Un paso concreto hacia la reconversión industrial y el futuro de Piombino.
FS Logistix ha adquirido seis nuevas locomotoras CZ LOKO para servicios de transporte de mercancías y maniobras.
Roma/Praga
Este es el cuarto pedido de este tipo que recibe la empresa checa en diez años.
Puerto de Bremerhaven: El crucero Mein Schiff 3 colisionó con dos buques portacontenedores.
Bremen
No hubo heridos. El crucero fue cancelado.
Paolo Moretti ha sido nombrado consejero delegado de RINA Spa.
Génova
Giosuè Vezzuto ha asumido el cargo de director ejecutivo de RINA Services.
HD Hyundai y Kiewit establecerán una empresa conjunta en un nuevo astillero en Estados Unidos.
Houston/Seúl
Está prevista la construcción de buques tanto militares como comerciales.
Los pedidos trimestrales de equipos portuarios de Konecranes disminuyen a medida que aumentan los ingresos.
Helsinki
El tercer trimestre de Kuehne+Nagel fue muy positivo.
Schindellegi
Crecimiento de los resultados económicos y operativos en todos los segmentos de negocio.
La apuesta de Wildcat por la defensa estadounidense: acuerdo exclusivo con el histórico astillero de Fraser.
Superior
El funcionamiento del fondo de Miami Beach forma parte del plan del gobierno para relanzar la industria naval estadounidense.
Puerto de Ancona: Se emite la primera autorización ZES individual.
Ancona
Se ha desbloqueado una inversión de tres millones de euros en la construcción de yates.
El acceso al puerto de Ravenna está autorizado para buques con un calado máximo de 11,00 metros.
Rávena
Benevolente: es un paso fundamental para el desarrollo económico y estratégico del aeropuerto.
El puerto de Génova extiende la autorización de inspección de alimentos a la terminal PSA SECH.
Génova
La disposición del Ministerio de Salud amplía las categorías de productos que pueden estar sujetos a control.
PROXIMAS SALIDAS
Visual Sailing List
Salida
Destinación:
- orden alfabético
- nación
- aréa geogràfica
El jueves, la Unione Interporti Riuniti presentará el proyecto ELODIE en la Cámara de Diputados.
Roma
El objetivo es crear una federación digital de interpuertos.
ABB registra pedidos récord por valor de 12.000 millones de dólares en el tercer trimestre.
Zúrich
Los ingresos y las ganancias también aumentaron, mientras que el grupo anunció una empresa conjunta con Mitsubishi Electric.
En el tercer trimestre de 2026, el volumen de contenedores en el puerto de Barcelona disminuyó un -9,2%.
Barcelona
El descenso se debió a una reducción del 19,9% en el tráfico de transbordo.
Las terminales de COSCO Shipping Ports establecen un nuevo récord trimestral de procesamiento de contenedores.
Hong Kong
En el período julio-septiembre también los volúmenes manejados por CMPort
En agosto, los puertos de Liguria Occidental gestionaron 5,2 millones de toneladas de mercancías (+1,6).
Génova
En Génova se registró un aumento del +6,1%, mientras que Savona-Vado Ligure sufrió un descenso del -10,0%.
Raben Italia abre un nuevo almacén en Pomezia.
Milán
El objetivo es consolidar el posicionamiento y la expansión territorial en el transporte por carretera.
El puerto de La Spezia firma un acuerdo para desarrollar proyectos de economía azul y seguridad.
La Spezia
Fue firmado por la AdSP y la Fundación del Centro Nacional de la Dimensión Subacuática.
El puerto de Long Beach celebra un nuevo récord mensual de movimiento de contenedores.
Playa larga
Nuevo máximo histórico también en el trimestre de julio a septiembre.
Se ha abierto la licitación para la demolición parcial del muelle norte del puerto de Ancona.
Ancona
La intervención incluye la regularización de los fondos marinos correspondientes.
HMM invierte más de 1.600 millones de dólares en 12 nuevos buques portacontenedores.
Busan
Para 2029, se entregarán ocho buques de 13.000 TEU, tres buques de 2.800 TEU y un buque de 1.700 TEU.
Paolo Pessina confirmado como presidente de Federagenti
Roma
Votación unánime de la asamblea de la Federación
Han comenzado las negociaciones para renovar el convenio colectivo único del sector naviero.
Roma
Las partes han acordado un intenso calendario de reuniones.
El tráfico de contenedores en el puerto de Hong Kong creció un 15,1% en el tercer trimestre.
Hong Kong
En septiembre el aumento fue del +25,0%.
Formación marítima: Apelación ante el Tribunal Administrativo Regional (TAR) contra el aumento de tarifas de la Autoridad Portuaria.
Roma
ANIFORMAR, CONFORMAR y 15 centros de formación desafían el decreto del MIT-MEF: los aumentos alcanzan hasta el 149,3%.
El Grupo Spinelli ha inaugurado un nuevo depósito de contenedores vacíos en Novi Ligure.
Génova
Inversión por valor de 14 millones de euros.
Rhenus integra sus servicios logísticos en un único centro logístico en el Interporto de Padua.
Padua
El complejo reunirá transporte por carretera, transporte aéreo y marítimo, almacenamiento y servicios especializados.
Un camionero fallece en el puerto del canal de Cagliari.
Cagliari
Habría quedado aplastado por una carga de tuberías grandes.
Confitarma, empresa dedicada al sector marítimo, está preocupada por la incertidumbre que surge de la interpretación que hace la Agencia Tributaria.
Mitsubishi Heavy Industries planea ampliar su capacidad de construcción naval.
Tokio
La empresa planea invertir 100 mil millones de yenes.
Trasportounito: El gobierno está loco si piensa que la crisis del transporte por carretera se puede resolver por sí solo.
Roma
Se insta a la aplicación de la cláusula de ajuste del costo del diésel.
Emanuele Grimaldi es el nuevo presidente de la Asociación Internacional de Armadores de Malta.
La Valeta
Sucede en el cargo a Marily Frangista, quien ha estado al frente de la asociación desde abril de 2022.
La cuarta edición de la Green Logics Expo arranca mañana por la mañana en Padua.
Padua
Contará con la participación de más de 300 expositores y la celebración de 30 eventos de conferencias.
En el tercer trimestre de este año, el tráfico de mercancías en los puertos turcos disminuyó un -1,1%.
Ankara
Los volúmenes de tráfico desde y hacia Italia crecieron un +6,2%.
En Assiterminal, la flexibilidad de los PRP debe tener en cuenta el mercado relevante en el que operan los puertos.
Génova
Cetus Maritime planea cotizar en la bolsa de valores Euronext Growth Oslo.
Hong Kong
Adquisición de 16 buques en preparación para su cotización en bolsa.
El sábado, un avión estadounidense impactó contra un buque granelero en el Golfo de Omán.
Tampa
Centcom: El barco había intentado imponer un bloqueo naval contra Irán.
PUERTOS
Puertos italianos:
Ancona Génova Rávena
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Liorna Taranto
Cagliari Nápoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venecia
Interpuertos Italianos: lista Puertos del mundo: Mapa
BANCO DE DATOS
Armadores Reparadores navales y astilleros
Expedicionarios Abastecedores de bordo
Agencias marítimas Transportistas
MEETINGS
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
El jueves, la Unione Interporti Riuniti presentará el proyecto ELODIE en la Cámara de Diputados.
Roma
El objetivo es crear una federación digital de interpuertos.
››› Archivo
RESEÑA DE LA PRENSA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Reseña de la Prensa Archivo
FORUM de lo shipping y
de la logística
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› Archivo
Buque impactado cerca del estrecho de Ormuz
Southampton
Una bala provocó un incendio que posteriormente fue extinguido.
OOCL informa un crecimiento del 9,0% en los volúmenes transportados por buques en el tercer trimestre.
Hong Kong
El aumento del valor de las tarifas de flete marítimo provoca un incremento del +45,1% en los ingresos.
HD Hyundai Marine Solutions adquirirá la empresa estadounidense Goltens Worldwide.
Dubái/Seongnam
La empresa se dedica a la reparación y el mantenimiento de grandes motores marinos y maquinaria industrial.
UNATRAS al gobierno: Desbloquee de inmediato las medidas para reducir los precios del diésel.
Roma
Las asociaciones de transporte por carretera denuncian retrasos e incertidumbres en la aplicación del acuerdo del 22 de mayo y solicitan una reunión urgente.
Puerto de Taranto: Gugliotti reitera su solicitud al gobierno de financiación para el parque eólico del puerto.
Taranto
El proyecto —subrayó— no puede ni reducirse ni posponerse.
Ataque a un barco en medio del Golfo Pérsico.
Southampton
La UKMTO informó que varios proyectiles causaron bajas entre los miembros de la tripulación.
Gioia Tauro: Se aprueba la adenda al Plan Portuario actualizado.
Gioia Tauro
Este análisis nos permitirá evaluar las necesidades de personal y de contratación de la Agencia Portuaria.
Barcos haciendo cola, combustible desperdiciado: cómo esperar fondeado puede ahorrarle dinero.
Copenhague
El Foro Marítimo Global publica los resultados de las pruebas realizadas por Cargill en 16 viajes reales. Reducir la velocidad y llegar cuando el muelle está libre disminuye el consumo de combustible y las emisiones.
ZIM eleva sus previsiones para todo el año 2026.
Haifa
Se espera que el EBITDA ajustado y el EBIT sean de 2.700 millones de dólares/3.000 millones de dólares y de 1.400 millones de dólares/1.700 millones de dólares.
Gabriele Sangiorgi ha sido nombrado secretario general interino de la Autoridad Portuaria de Rávena.
Rávena
El mandato de Fabio Maletti ha expirado.
Puerto de Génova: Los trabajadores de la terminal de Messina se declaran en huelga durante una hora por un mes.
Génova
La empresa informa que uno de los miembros del sindicato no se presentó a la última reunión, en cumplimiento del procedimiento de reflexión previsto en el Convenio Colectivo Nacional.
Puerto de Taranto, acuerdo para participar en el desarrollo del Valbasento Interporto en Ferrandina.
Matera/Taranto
Se elaborará un plan maestro logístico-funcional en un plazo de 180 días.
En Ática, el déficit se reduce principalmente gracias a las ganancias de capital y la cobertura.
Kallithea
Primer semestre del año con menos cruces y un ligero aumento de los ingresos.
Desde principios de año, el número de pasajeros y mercancías en los buques de GNV ha aumentado un +2% y un +5%, respectivamente.
Marrakech
Asociación estratégica de tres años con la Oficina Nacional Marroquí de Turismo.
- Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA
tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Director: Bruno Bellio
Prohibida la reproducción, total o parcial, sin el explicito consentimento del editor
Búsqueda en inforMARE Presentación
Feed RSS Espacios publicitarios

inforMARE en Pdf
Móvil