testata inforMARE
Cerca
02 de octubre de 2026 - Año XXX
Periódico independiente sobre economía y política de transporte
15:41 GMT+2
LinkedInXFacebook
FORUM de lo shipping y
de la logística


The dry bulk market in 2003

 Due to last, but for how long?


The freight market:
     Capesize - Panamax - Handymax & Handysize
The second-hand market:
     Capesize - Panamax - Handymax & Handysize


Twelve months ago we started our review of the dry bulk market with the heading 'towards a brighter horizon?', largely due to the fact that freight rates had tripled during the previous quarter, and we ended by stating 'the future is always right!'. A number of factors could have had a negative influence on the dry bulk transport demand at that time: with the question of the world economic recovery, and principally the American one, being continually pushed back to a later date by the forecasters.

Some of the aspects that clouded the picture were:

  • commercial trade had come to a standstill and for the first time in ten years showed no sign of progress,

  • an imminent Iraqi conflict which nobody could predict the outcome,

  • a drop in confidence on the part of American consumers, the mainstay of the economy, as well as that of managers and in consequence on investment,

  • the persistent deep recession in Japan.

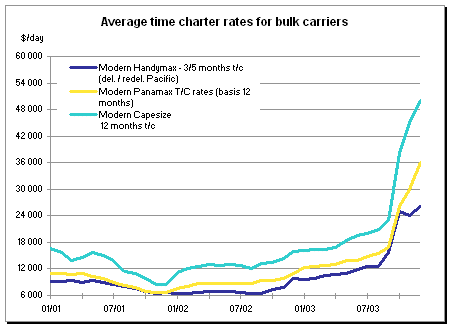
 However 2003 has been historically speaking a year of records for all sizes, with the dry bulk market hitting levels that have never been seen before. Time-charter rates reached and over several months remained more than $80,000 per day, even occasionally $100,000 per day on certain movements for modern Capesize, whereas rates for Panamax and Handymax reached levels of $40,000 and $30,000 respectively.


However 2003 has been historically speaking a year of records for all sizes, with the dry bulk market hitting levels that have never been seen before. Time-charter rates reached and over several months remained more than $80,000 per day, even occasionally $100,000 per day on certain movements for modern Capesize, whereas rates for Panamax and Handymax reached levels of $40,000 and $30,000 respectively.

The explosion of the freight futures market this year, which should continue to grow, was between $4.5 and $6 billion in 2003 as compared to $3 billion a year earlier, is also a sign that the players are facing a market which is unpredictable.

It would be presumptuous to try and give an exhaustive explanation to such a phenomenon. The shipping industry is above all cyclical and every 7 to 10 years there are peaks, followed by long depressions, of which the last peaks go back to 1988 and 1995.  However, these were not of the same amplitude as today's one.

Certain elements leave one to believe that we have not yet reached the end of this growth cycle, which while it may experience some hiccups, could also, according to some analysts, continue for another 2 to 10 years - which illustrates the uncertainty of forecasting.

Amongst the causes that 'explain' the year 2003, which are more prevalent and numerous than a year ago, therefore suggesting that the trend will continue, we can mention:

  • commercial trade, according to WTO, was on the rise after a year of stagnation, and which should increase by 3% in volume over 2003, but 15% in value during the first half, and which should continue to expand by more than 4% in 2004,

  • the enormous appetite for energy and raw materials in China to meet its sustained economic growth of around 9% in 2003 and forecasts of not less than 7% in 2004,

  • this strong trend in growth could continue until 2008 at least, with the prospect of organising the Olympic Games being a showcase to the World: the Three Valleys dam, the development of the Chinese car industry, and the plethora of industrial investments which will require imports of iron-ore, of which China is a modest producer, and of coking coal,

  • world steel production which rose to 864 million tons for the firsts 11 months of the year according to IISI sources, an increase of 6.6% over the previous year, but with important divergences by country. The Euro zone only registered an increase of 0.8%, whereas China can boast of an increase of 21% and broke the historic barrier of 200 million tons, over twice that of Japan, its immediate rival. China has thus become the largest steel producer, whereas in 1990 production was only 66 million tons, and helped contribute to break all records for world steel production. Analysts in the Japan Iron and Steel Federation even predict that Chinese steel production could reach 500 million tons in 2010! In this respect on December 15th the lifting of duties imposed on imported steel by the Bush administration since March 2002 will alleviate trade and prevent a commercial war against the US which was being prepared by their trading partners,

  • the investment projects of two steel giants Thyssen-Krupp and Arcelor in China to develop the mining potential. The reactivating of mining development projects in Australia for a total of $800 million in order to respond to future demand,

  • the rise in price of nickel, zinc, copper, plus tight stocks and growing demand, mainly Chinese, will incite new developments in this sector and expansion should be concentrated within the Pacific zone,

  • the more discrete emergence of India, both as importer and exporter. Following a recent study carried out by Goldman Sachs, India should surpass the US and Japan in terms of GDP in a handful of decades. The lack of infrastructure in this country and the size of its population should in themselves contribute to a growth in domestic needs for raw materials. Growth in steel production for example was 11.3% during the first 11 months, at over 28 million tons and is now bigger than that of Italy,

  • the unexpected economic growth in the US, due in part to the lowering of taxes, the weakness of the dollar and an unswerving confidence by Americans in their economic policies. After wavering between recession and growth, the latter should achieve around 3% in 2003 and between 3.5-4% in 2004, it has hit 8.2% in the third quarter - its best performance over the last 20 years,

  • 2003 also saw a growth of around 2.7% in the GDP of Japan after years of recession, and the recovery of South Korea, which had a more modest growth of nearly 1 %. For part of the year Japan underwent a prolonged shutdown of 17 out of 51 its nuclear power plants, which produce 30% of domestic energy needs, resulting in a large increase in the import of steam coal,

  • even the Euro zone has revised its forecasts upwards, and France could achieve 1.7% in 2004, somewhat above the initial government forecast.

The combination of these factors should enable the upward trend that has prevailed throughout the last year to continue.

In respect of the dry bulk fleet, certain conditions have contributed to a reduction in available capacity:

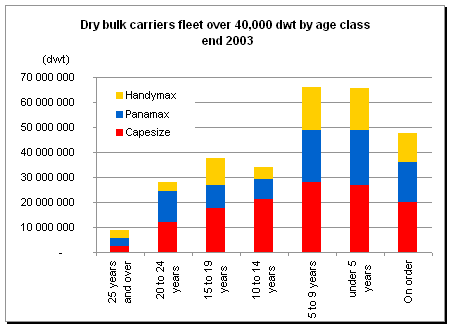
  • a small number of Panamax being delivered, only 20, for the first time in several years, and the moderate additions to the fleet for Capesize, which will also be the case for 2004,

  • congestion in a number of Australian ports, mainly due to the volume of exports. As an example, Australian ports have exported around 215 million tons of coal in 2003 against just over 200 million tons in 2002.

2003 witnessed a dramatic revival of orders for Capesize on behalf of Japanese and Chinese owners. Mitsui at the end of the year announced the firm order for 30 ships, of which some were destined for the Chinese market.

Orders for Panamax and Handymax sizes were also omnipresent, with certain Chinese and Japanese yards being able to offer early deliver dates, due to a slack orderbook and thanks to ever-increasing gains in productivity.

Construction prices remained stable for the first half of the year before seeing increases in the third quarter. The price of a Capesize moved up from $40 million in January 2003 to nearly $50 million by the end of the year.

The size of the last Capesize ordered has varied on one hand towards over-Panamax coal carriers of 90,000 dwt, as well as a considerable number of big ore carriers of 200,000 dwt or more, whilst the standard size of 170,000 dwt is always in strong demand. The Chinese steel giant Baosteel even has on the drawing board a project for a ship of 545,000 dwt, but for which the feasibility has still to be proved. In the Panamax category, the 'Kamsarmax' design of 82,000 dwt has also had significant success. The standard size of Handymax is moving more and more towards 60,000 dwt. The Japanese yard Mitsui took in orders for 43 Handymaxes of the '56' type in 2003.


The debate within the shipping community about the worthiness of introducing double-hulls, which should get decided by the IMO in 2004 with an application as from 2007, has been anticipated by a certain number of owners who have placed orders for such vessels, which require an additional 500 tons of steel for Capesize.

In the industrial sector, the weakness of the dollar risks to weigh heavily against European steel plants if it persists, and some companies such as Corus are going through a difficult period with results much lower. In face of the pull of attraction towards China, yearly negotiations for supplies by Japanese steel companies are likely to open in a tense atmosphere.

The main merger/acquisition took place in the aluminium sector, which after their abortive marriage two years ago, saw Alcan take control over Pechiney (previously first in terms of capital on the French stock market), and to become close competitor of Alcoa, the leader in this sector.
 

The evolution of freight rates over the year

The reference index of the Capesize market on the Baltic Exchange, the BCI, went from 2,993 points on January 2nd 2003 to 6,734 points just before Christmas. This historic rise goes without comment! Apart from a slight correction during the first three weeks of November, freight rates followed a particularly strong upward curve as from September. These increases apply both to spot rates as well as time-charters.

A few examples can clearly illustrate this incredible ascent. On the classic iron-ore route from Brazil to China, the rates per ton went from less than $7.00 at the beginning of the year to achieve $17.00 at mid-year, and over $33.00 in October and end December, which were the two high points in the period. In the coal market the rise was slightly less spectacular. Liftings from Richards Bay to the Continent went from $9.00 in January to $11.00 in June to finish at $26.00 at year-end. In the Pacific we find a similar trend with rates for iron ore out of Australia to China at less than $6.00 at the start of the year only to finish near the $18.00 level in December.

Perhaps even more impressive were the time-charter equivalent rates, which illustrate the inexorable rise that was experienced over the last 12 months. Fronthaul trips for delivery to the Continent via Brazil with redelivery in the Far East started out at $24,000 at the beginning of the year, to climb to around $36,000 in June/July, and to finish at over $80,000 in October and November. By comparison, the same ships were obtaining 12-month rates at the end of 2001 of $9,000 per day.

The financial results of some operators are not however always in line with the tenor of the market, to the extent that certain contracts were made at the bottom, and moreover, to 'relet' a vessel in a strong market is not always easy. As a result in the second half of the year, we saw an increasing number of fixtures for periods up to 5 years in order to balance out the excesses, either up or down. The 12-month time-charter rates, for modern ships went from around $18,000 per day at the start of the year to over $60,000 in December. Smaller and older vessels of the China SB type saw their charter rates go from $16,000 per day at the beginning of the year to $38,000 by the end. The extreme tightness of the Capesize market this year was on some occasions illustrated by the use of two Panamaxes to replace a Capesize on certain shipments, thus helping to bolster the market of the smaller sizes.
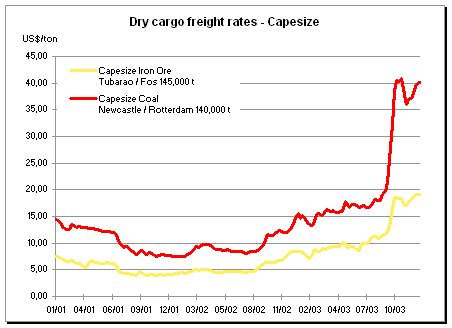
As to scrappings, there were very few since only 6 Capes for 0.731 million dwt went to the breakers. The historic highs for scrap prices were not enough in comparison to the attraction of the spot freights, which allowed owners of old vessels to achieve substantial profits. Thirty-five ships for 5.6 million dwt joined the existing fleet and the forecasts for 2004 are for 38 ships and 6.6 million dwt. Nonetheless, the 78 new units for 13 million dwt, which were ordered in 2003, could result in a tighter position in 2005 and beyond, if the rise in the dry bulk movements should run out of steam.
 

As predicted, the Panamax market saw an extremely limited number of new units enter the fleet in comparison to previous years and for those to come. Only some twenty vessels joined the ranks in this category in 2003. 2004, 2005 and beyond will see numbers greatly increased with 73 and 122 units anticipated. These figures however are expected to vary considerably as a number of contracts are concluded at the last minute and the construction time of a Panamax is only a matter of months between keel laying and delivery.

At the time of writing a number of recent ships have been fixed for one year around $32,000 to $33,000 per day, rates which seem ridiculous with respect to those at the beginning of 2003. At that time, a Panamax could obtain about $12,000 per day, compared to the end of 2001, when rates had dropped to around $5,000 per day.

The Panamax market, like the Capesize, benefited from the healthy performance of iron-ore and especially coal, but also from the continuous rise of other bulks mainly into China. Demand for bauxite and alumina should continue to increase in 2004, as well as the volumes being transported. Within the main bulk markets only cereal should stay flat or slightly regress over the next two seasons due to climatic conditions, for a quantity of some 204 million tons.

On the spot market important gains were recorded across the scene, with the grain route between the Gulf of Mexico to Japan doubling between January and December, going from $25.00 per ton to $50.00 per ton. The transatlantic route also improved by the same proportions going from $15.00 to $30.00. The poor harvests in Northern Europe due to the drought will have an effect on the zone, being traditionally a large exporter.

Demand from other bulks in the Far East and the active market of fertilisers out of the Baltic and Black Sea, enabled fronthaul rates to reach highs, as well as transatlantic round voyages, to increase from $12,000 per day up to $17-20,000, and to finish the year at above $30,000. The situation in the Pacific and the Indian Ocean offered even more spectacular opportunities within the coal trade, with rates for local trips jumping from $13,000 to $40-43,000 per day at the end of the year. Two years earlier, rates for modern ships on similar voyages were being concluded around $5,000 per day. What a way we have come!
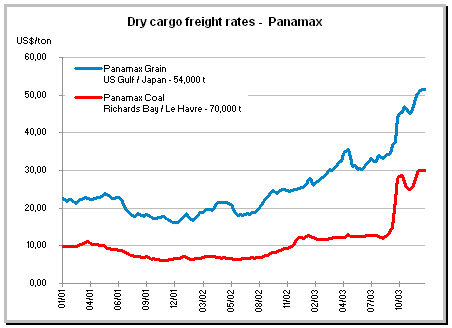
As with the Capes, the figures for scrapping remain very low, with only 8 ships totalling less than 0.6 million dwt being demolished, compared to 24 a year earlier. A total number of 119 of ships have been ordered, and others will follow shortly, as there still remain some available berths for delivery in 2006. The number of orders is however subject to revision as some contracts are still to be confirmed.
 

As for the Panamaxes, this category of ship, which now extends up to 60,000 dwt, enjoyed a much more active market than during 2002. Sugar, scrap, coal and all that is traditionally included in this size of vessels are on the increase, based on available provisional sources. But it is above all the increased volumes of coal heading for India and China, plus iron-ore from Australia to China, which have had such an effect on the rates in the region.

Handymax rates on fronthaul voyages have gone from $11,000 at the start of 2003 to nearly $27,000 end December and ships of 50,000 dwt and more in the Pacific have climbed up to $25-26,000. In the same way the Handysize of 25,000-35,000 dwt have benefited from an extremely favourable market due to their scarcity. For example, a modern 28,000 dwt ship chartered for $5,000 at the beginning of the year finished at nearly the double. Period charter rates as with the Capes and the Panamax went rocketing, moving from $ 7,000 in January for a modern Handy of 28,000 dwt to $ 13,000 several months later, while as Super-Handymax (grabbed) saw levels for 12 months, shoot from $ 9,400 at the beginning of the year to over $ 28,000 end 2003 for short periods and $ 26,000 for 12 months.

Contrary to the Capes and Panamax, scrapping figures were not so much affected by the strong state of the market, doubtless due to the high number of old vessels which remain in this segment. 73 ships, as compared to 108 in 2002, were demolished. Deliveries this year should reach around 70 ships of 25,000 to 38,000 dwt and 63 ships over 50,000 dwt. A total of 359 ships is on order, but given the variety of building sites, delays, bankruptcies and the fact that some Chinese yards will not be able to honour all their orders, again cause the figures to be liable to fluctuation.
 

Prospects

 What factors could be a possible source of problems for conditions continuing as in 2003?

  • the devaluation of the dollar, which has lost 25 % of its value compared to the euro in a year and, if it continues, it will have a negative effect of European exports, but it is difficult to see how it could affect developments of China in the short term.
  • The steel agreement between the US and its partners is now behind us, but the monetary debate between the US and China, with the latter pushed to re-evaluate their currency, is still unresolved.
  • A resurgence of the SARS virus or something similar could easily come to upset business and trade within the Asian zone.
  • The major concern is perhaps, as outlined by Alan Greenspan, the amount of the American deficit, which has reached giddy heights and the debt which must sooner or later be reimbursed (but probably not in an election year) and could put growth at risk in the US.
  • The Iraqi conflict, America getting bogged down there or the problems spreading to other adjoining states?

Notwithstanding and compared to a year ago, we can nonetheless state that the positive elements far outweigh the negative ones.


The second-hand market


The second-hand market for Capesize (80,000 dwt and more) 2003

In line with freighting levels, prices obtained for the large bulk carriers did not stop beating record after record since the beginning of the year. Between January and December 2003, the average value of ships has appreciated by about 70 % and even more in some cases. No less than some 40 sales have been reported, of which some were for the same ship within an interval of several months.

The buyers? Once again the award goes to Greek owners with 50 % of the sales. Owners such as Lykiardopulo with 5 ships, or Overseas Marine, have distinguished themselves in particular. Just behind them is Bocimar, who purchased 5 ships of which the famous 'H hull' initially ordered by Transmed for $ 36 million in June 2002, then resold for $ 38 million to Metrostar Management in April 2003, who then sold again the hull to Bocimar in October 2003 for $ 48 million, finally the latter reportedly committed the same ship to Ocean Longevity at a price of $ 60 million last October, but a final sale was however not concluded.

                                               January 2003           December 2003

150,000 dwt, 10 years                  $ 21 m                      $ 33-34 m
170,000 dwt, 5 years                    $ 30-31 m                 $ 48-49 m

This episode is very symptomatic of the crazy evolution of the market during the year. We have to go back to the years 1991 and 1995 to find anything similar. However the absence of any slipways available before 2007 in shipyards, combined with the excellent prospects for steel and energy needs in Asia and more particularly in China, is creating a situation which on the face of it, looks likely to hold at current levels, if not get even tighter. But for how long? Some project a positive cycle of several years.

Nonetheless, opinions can differ as to the correction more or less drastic, which could occur in the short/medium term. Being brokers we would only hope that the market calms down, which can only be beneficial to all players including owners. Chinese economic authorities are trying in turn to control from their side the surge of their GDP growth in order that it will stay firm and steady.

Faced with such a tense market, who can blame owners for preferring to charter out their ships on the spot market (up to $ 100,000 per day being achieved!) to the sometimes tantalising offers of buyers in search for tonnage. One thing is sure for the moment: all owners of a Capesize delivered in 2003 can congratulate themselves for their investment'

Outside of Golden Union and Metrostar, who benefited from the market take-off to resell their shipbuilding contracts at a more than comfortable profit, all owners who placed orders in the last two years have resisted the temptation for a quick sale and have turned towards chartering out.

Logically the number of ships sold for scrapping has remained quite modest, with only 5 ships being withdrawn from the fleet this year.

Three-quarters of ships sold in 2003 (31) were less than 10 years old, including the resale of ships under construction. Owners of older ships, already more or less amortised, have preferred in the manner of the owner Zodiac, to operate them and to collect over the year revenues that are sometimes greater than the book value of the ship.

2003 has therefore been an exceptional vintage for the Capesize market and prospects are still more than reassuring for owners!
 

The Panamax, Handymax & Handy bulk carrier second-hand market

What a year has 2003 proven to be. For those of us involved in shipping, it is times such as the past few months that we have been waiting and hoping for. Adjectives describing freight rates and ship values as 'fantastic', articles in the shipping press talking about 'party times' and 'owners re-writing the rules' can give some idea of what took place and still is taking place in the dry bulk markets.

In our last year's annual review covering these sizes we were 'expecting values to remain stable with a slight upward trend over the next few months.' We were correct for the first six to nine months of 2003, but, like most professionals in this industry, we were caught totally unaware of the dramatic increase of freight rates experienced in the fourth quarter of the year, which led to 'booming' prices in all sizes and age categories.

At the end of 2003 second-hand values of dry bulk tonnage seem to behave in a similar manner as the stock exchange markets were behaving in 1999-2000. It is our opinion that prices will remain at such levels and will continue to record further gains should the chartering markets remain at such healthy levels.

Record prices were achieved on a weekly basis with 'new benchmarks' lasting only for a couple of days - 'today's extremely firm price' became 'tomorrow's normal market price' and a few weeks later it was considered as 'cheap'.

Prices across the board increased by 10 to 15 % during the first 8/9 months of the year and skyrocketed during the last 3 months resulting in an overall price increase at the end of 2003 which in some cases reached as much as 60 to 65 %.

A total of 341 ships reportedly changed hands during 2003, almost the same (330) number of transactions as during 2002. We also note that when looking closer at the three size segments, the number of sales is almost the same as the previous year.

  • Panamax sales: 76 ships in 2003 against 70 ships in 2002.
  • Handymax sales: 127 ships in 2003 against 117 ships in 2002.
  • Handy sales: 138 ships in 2003 against 143 ships in 2002.

As expected at times of booming freight markets, nobody would like to sell for demolition and this therefore has led the number of ships reported sold for recycling during 2002 being significantly less than the those sold during the previous year.

  • Panamax: about 0.3 million dwt were removed this year, 5 vessels, representing a decrease of about 66.6 % over the figures for 2002.
  • Handymax: about 0.45 million dwt were removed during 2003, 11 vessels, representing a decrease of about 48.0 % over the figures for 2002.
  • Handysize: about 1.9 million dwt were removed this year, 70 vessels, representing a decrease of about 10.0 % over the figures for 2002.

As freight rates increased on a daily basis, the number of ships offered for demolition decreased. This naturally led to a sharp increase of prices obtained per light displacement ton from buyers of such tonnage, which at the end of 2003 for a bulk carrier stands at about $ 270-275 per ton and could soon break the $ 300 mark if freights continue to increase or even stabilise at present levels.


  • Panamax (55 500-77 000 tpl)

    A 10 year-old Panamax bulk carrier was worth about $ 19.0-20.0 million in December 2003, representing an increase of about 60-66 % over a period of 12 months, a 5 year-old Panamax bulk carrier was worth about $ 28.0 million, which represents about 65 % appreciation when compared to the value of one year earlier in December 2002.

  • Handymax (36 5000 ' 55 500 tpl)

    End 2003, a 10 year-old Handymax bulk carrier was worth about $ 16.0 million, representing an increase of about 50-52 % over a period of 12 months, a 5 year old Handymax bulk carrier was worth about $ 20.0 million which represents a 38-40 % appreciation when compared to the same period one year earlier in December 2002.

  • Handysize (18 000 ' 38 500 tpl)

    A 10 year-old Handysize bulk carrier was worth about $ 10.75-11.0 million at the end of the year, representing an increase of about 35 % over a period of 12 months, a 5 year-old Handysize bulk carrier is worth about $ 14.5 million which represents a 28-30 % appreciation when compared to how much it was worth one year earlier in December 2002.

* * *

Concluding this year's review of the second hand dry bulk carrier markets, all parties involved in shipping, be it owners, charterers or brokers do not forget the basic laws of physics such as 'What goes up, eventually comes down, and the higher it reaches the greater the fall ''. However the crucial question is not 'Will the market come down?' but 'When will it come down?'

If the world economic indicators available can be considered reliable, then we would expect the dry bulk freight market to remain at levels considered as very firm and we would not therefore expect bulk carrier prices to ease off any time soon.

In fact we would expect prices to firm further. So for those contemplating an investment in dry bulk tonnage the sooner this is undertaken the better it will be. Do not forget 'Today's extremely firm price becomes tomorrow's normal market price and a few weeks later it is considered as cheap'.


Shipping and Shipbuilding Markets in 2003

I N D E X

›››Archivo
DESDE LA PRIMERA PÁGINA
Puertos: La Comisión Europea insta a Italia a rechazar el requisito de la bandera nacional para el remolque y el amarre.
Bruselas
Francia y España también recibieron un dictamen motivado: dos meses para cumplir con la normativa sobre servicios portuarios.
Otro barco fue atacado en el estrecho de Ormuz.
Southampton/Teherán
Irán se enfrenta a una escasez de productos básicos, que también se importan a través del Golfo Pérsico.
Corredores europeos: Italia se enfrenta al reto de 2030.
Bruselas
La infraestructura nacional cumple en gran medida con los requisitos, pero el calendario y la financiación de los proyectos clave siguen siendo inciertos.
Electrificación de puertos y aeropuertos: la red eléctrica es el nuevo cuello de botella.
Bruselas
El Ministerio de Transporte y Medio Ambiente pide que se agilicen las conexiones y que se supere el criterio de "el primero que llega es el primero en ser atendido".
Boluda gestiona la terminal polivalente del muelle Príncipe de Espanya en el puerto de Barcelona
Barcelona
El contrato de concesión tendrá una duración de 16 años.
El valor actual del Aeropuerto de Génova Spa se sitúa entre 14,9 y 15,9 millones de euros.
Génova
Evaluación de PwC presentada
FEPORT: El sistema de comercio de derechos de emisión de la UE no debería expulsar el transbordo fuera de Europa.
Bruselas
La federación de operadores de terminales insta a la comisión ENVI a reforzar las medidas contra la evasión fiscal y a destinar parte de los ingresos del Sistema de Comercio de Emisiones (ETS) a los puertos.
Nueva serie de ataques contra barcos en el estrecho de Ormuz.
Southampton/Teherán/Tampa
Tres buques cisterna fueron alcanzados por proyectiles. Otro barco se incendió.
Eurokai, mayores ingresos pero menores beneficios.
Hamburgo
Los ingresos aumentaron un 14,4% y el tráfico un 8,3%, pero el beneficio neto cayó un 8,3% debido a la menor cuota de mercado de Eurogate.
Impuesto sobre el alojamiento en Génova: el Tribunal Administrativo Regional falla a favor del Ayuntamiento.
Génova
El recurso presentado por los armadores y agentes navieros fue rechazado.
Carnival registra ingresos y beneficios rĂŠcord en el trimestre de junio a agosto, a pesar de un aumento del 36% en los costes del combustible.
Carnival registra ingresos y beneficios récord en el trimestre de junio a agosto, a pesar de un aumento del 36% en los costes del combustible.
Miami
Los depósitos de los clientes están en su punto más alto. Se espera que los precios y la ocupación alcancen niveles récord el próximo año.
Ganadores y perdedores en la conectividad portuaria: la larga trayectoria de los altibajos de los puertos italianos.
Ginebra
Los índices de la UNCTAD revelan un Mediterráneo en transformación: Italia cae al séptimo puesto, La Spezia, Trieste y Vado Ligure crecen, mientras que el sur pierde terreno.
Los camiones eléctricos son más asequibles que los diésel en seis de los principales mercados de la UE.
Bruselas
Según T&E, en los países que representan el 46% de las ventas europeas, los vehículos eléctricos ya se han abaratado en cinco años. Italia, España y Polonia se encuentran rezagadas.
AP Moller Capital adquirirá una participación mayoritaria en Euroports.
Copenhague/Amberes
R-Logitech se desvinculará del capital, mientras que PMV y SFPIM seguirán siendo accionistas.
En China, las exportaciones están creciendo, pero la actividad en los puertos se está ralentizando.
Pekín
En agosto, el comercio exterior mundial aumentó un 19,8%, pero el volumen de mercancías internacionales gestionadas por los puertos marítimos disminuyó un 2,3%.
De Puertos del Estado a Puertos de Italia: la misma inspiración, un resultado opuesto.
Génova
Para la reforma portuaria, el gobierno se remite al modelo español, pero está construyendo justo lo contrario: otro contrapeso más, de esos que el espíritu empresarial italiano sabe inventar tan bien.
Sistema de comercio de derechos de emisión marítimo: Bruselas se abre a los ferris híbridos y eléctricos, pero Interferry exige más.
Bruselas
La revisión propuesta refuerza el mecanismo SMAP, pero deja la cuestión de las redes e infraestructuras portuarias en manos de AFIR y FuelEU Maritime.
Un marinero muere a bordo de un buque granelero atacado en el estrecho de Ormuz.
Nueva Delhi/Southampton/Teherán
Los demás miembros de la tripulación fueron rescatados.
El tráfico de mercancías en los puertos de Génova y Savona-Vado sigue oscilando entre signos de recuperación y ralentización.
Génova
En julio, los volúmenes aumentaron en ambos puertos de Liguria.
Trasportounito ofrece un sistema automático para ajustar las tarifas de transporte por carretera al precio del diésel.
Roma
Gente de mar, cinco años después de la entrada en vigor del Código de Conducta, la brecha entre la política y la realidad persiste.
Londres
El cumplimiento normativo por parte de las compañías navieras está aumentando, pero persisten problemas relacionados con la fatiga, la seguridad psicológica, las quejas y los costes de contratación.
El mes pasado, el tráfico marítimo en el Canal de Suez aumentó un 26,9%.
Ismailia
En los primeros ocho meses de 2026, fue cruzada por 9.602 barcos (+17,4%).
La decisión sobre el tramo ferroviario crucial del Corredor Escandinavo-Mediterráneo en Alemania se pospone nuevamente.
Hamburgo
Los operadores portuarios alemanes reclaman una aceleración tanto de la construcción de nuevas infraestructuras como del fortalecimiento de la línea existente.
Kuehne+Nagel acuerda una alianza estratégica a largo plazo con Amazon.
Schindellegi
El acuerdo incluye una opción de compra sobre las acciones existentes del grupo logístico.
MSC está en conversaciones para adquirir el grupo alemán de construcción naval Meyer Werft.
Nueva York
Actualmente, el 80,73% del capital está en manos del Gobierno Federal Alemán y del Estado de Baja Sajonia.
Trafigura crea una nueva compañía naviera dedicada al transporte de petróleo.
Ginebra
Inicialmente, Volare Shipping cuenta con una flota de seis VLCC, además de ocho en construcción.
Los armadores están pidiendo a los Estados miembros de la UE que aprueben la inclusión de dos astilleros indios en la lista europea de instalaciones de reciclaje de buques.
Bruselas
Se ha inaugurado en Génova la nueva sede de la Academia Italiana de la Marina Mercante.
Génova
Los puertos franceses registraron un equilibrio entre aumentos y descensos en el segundo trimestre.
París
El tráfico total alcanzó los 71,1 millones de toneladas (-0,2%). El tráfico de contenedores aumentó un 8,1%.
El Plan Director del Puerto de Génova, el muelle de Pra' y los depósitos de productos químicos de Multedo son los temas más espinosos en las conversaciones con los operadores y la zona local.
Génova
Crosetto: La Armada italiana garantizará el tránsito seguro de los buques italianos a través del estrecho de Bab el-Mandeb.
La Spezia
Tenemos —subrayó el Ministro de Defensa— la capacidad para proteger su paso.
Assiterminal: La certeza sobre el lecho marino y el dragado planificado son esenciales para la competitividad del puerto.
Génova
Mordeglia: No solo necesitamos una regla más sencilla, sino una predecible.
Alemania está reformando el IVA para hacer que sus puertos sean más competitivos.
Hamburgo
La Conferencia de Ministros de Finanzas aprueba el modelo de compensación que debería eliminar la prefinanciación del impuesto a partir de 2030.
Arabia Saudí denuncia que los hutíes están llevando a cabo una política destinada a "estrangular el estrecho" y a mantener como rehén a la comunidad internacional.
Nueva York
El Consejo de Seguridad de la ONU está dividido entre las condenas y los llamamientos a la negociación.
OMC: Una reforma del sistema comercial podría aumentar el PIB mundial en un 3% para 2050.
Ginebra
El Informe sobre el Comercio Mundial 2026 advierte de los costes de la fragmentación: hasta un 7 % menos de PIB mundial en un mundo dominado por los acuerdos de libre comercio.
Uno de cada diez contenedores no cumple con los estándares.
Washington
WSC publica los datos de inspección de 2025: de las 93.079 unidades inspeccionadas en siete países, 9.645 presentaban deficiencias.
El Consejo Mundial de Transporte Marítimo (WSC), la asociación internacional que representa a los principales armadores de buques portacontenedores del mundo, ha instado a los estados miembros...
Maersk y Hapag-Lloyd reanudarán cuatro servicios en la ruta del Canal de Suez.
Copenhague/Hamburgo
Las líneas conectan Asia con Europa/Mediterráneo.
Los grupos Neri y Nova Marine Carriers controlarán la terminal Calata Orlando
Lugano
La terminal de Livorno será objeto de una importante inversión.
Cavotec y EVIAS firman un acuerdo para la recarga en movimiento de vehículos eléctricos portuarios.
Estocolmo
La empresa sueca se convierte en distribuidora e instaladora exclusiva para el sector portuario de las tecnologías de la empresa francesa.
Hapag-Lloyd firma un acuerdo con DP World para asegurar capacidad de terminal en África.
Hamburgo
El acuerdo concierne a los puertos de Dakar, Luanda, Dar es Salaam, Banana y Maputo.
La amenaza para el transporte marĂ­timo en el Mar Rojo aumenta a medida que los hutĂ­es se apoderan de la isla de Perim.
La amenaza para el transporte marítimo en el Mar Rojo aumenta a medida que los hutíes se apoderan de la isla de Perim.
Saná/Hamburgo
Los armadores alemanes advierten que la posibilidad de volver a la ruta de Suez se aleja aún más.
Nuevos ataques contra barcos en el estrecho de Ormuz.
Southampton/Teherán
La Armada de la Guardia Revolucionaria Islámica ataca a un dron naval estadounidense.
El puerto de Long Beach registra un tráfico récord de contenedores en agosto.
Playa larga
En los primeros ocho meses de 2026, los volúmenes crecieron un +1,3%.
WSC informa que los contenedores llenos de baterías de litio pueden enviarse sin ser identificados como mercancías peligrosas.
Washington
Kramek: Personas, puertos, barcos y el medio ambiente marino en riesgo
La revisión del Régimen de Comercio de Derechos de Emisión (RCDE) para el transporte marítimo propuesta por la Comisión Europea supone un paso adelante con ciertas reservas.
Bruselas
Sin embargo, si el sistema se extiende a pequeñas unidades navales —subraya la asociación—, las exenciones y las excepciones corren el riesgo de anular su impacto climático.
El trĂĄfico ferroviario de mercancĂ­as transalpino sigue bajo presiĂłn a pesar de la recuperaciĂłn econĂłmica.
El tráfico ferroviario de mercancías transalpino sigue bajo presión a pesar de la recuperación económica.
Berna
La carretera va más rápido que el tren.
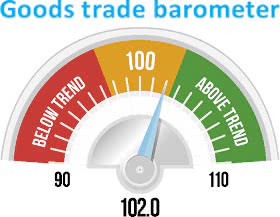
La inteligencia artificial impulsa el comercio mundial, a pesar de Oriente Medio y los aranceles.
Ginebra
El barómetro de la OMC está en alza. La demanda de semiconductores y componentes electrónicos está compensando las tensiones geopolíticas.
Luz verde a una inversión de 1.350 millones de euros en el puerto de Bremerhaven.
Bremen
Se trata de la mayor cantidad de fondos que el gobierno federal ha destinado jamás a un proyecto en el estado.
APM Terminals firma un acuerdo para desarrollar el puerto de Badagry en Nigeria.
Copenhague
Se construirían cuatro kilómetros de muelles con un calado de -18 metros.
Renaissance Partners ha firmado un acuerdo vinculante para adquirir De Wave Group.
Génova/Milán
La empresa genovesa será vendida por la empresa estadounidense Platinum Equity.
Descarbonizar el transporte marítimo: un reto de 36.000 millones de euros y una oportunidad de 45.000 millones de euros para Italia.
Cernobbio
Sin inversiones en puertos, Italia corre el riesgo de perder 80.000 millones de euros en valor añadido para 2050.
Los sindicatos canadienses quieren que BC Ferries construya nuevos transbordadores en la Columbia Británica.
Delta
El último pedido de la empresa fue a la empresa china CMI Weihai.
Filt, Fit y Uilt deberían retirar la enmienda que pone en riesgo a las empresas y cooperativas portuarias en virtud del artículo 17.
Roma
Los sindicatos temen la sustitución progresiva de una función estructural del puerto por formas de trabajo precarias.
Norwegian Nor Cruises firma un memorando de entendimiento con la empresa china SWS para la construcción de 2+3 nuevos cruceros.
Llevar a la fuerza
Las unidades tendrían un tonelaje bruto de 84.000 toneladas.
En julio, el tráfico marítimo en el Canal de Suez aumentó un 27%.
El Cairo
En los primeros siete meses de este año, el tráfico marítimo fue de 8.244 buques (+15,9%).
Mañana Kombiverkehr inaugurará una conexión intermodal entre Ratisbona y el Interporto Quadrante Europa.
En mi opinión, el Marco de Cero Emisiones Netas sigue estancado: aún no se ha llegado a un acuerdo sobre la fijación de precios del carbono.
Londres
38 estados votaron a favor y 17 en contra. La adopción formal se pospuso hasta diciembre.
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
Se ha adjudicado el contrato para el dragado y la finalización de la electrificación de los muelles del puerto de Gioia Tauro.
Gioia Tauro
Serán llevadas a cabo respectivamente por Dravo y RTI Saet-Suardi.
Premio de estudiante de arquitectura naval otorgado en Génova
Génova
El Grupo d'Amico y la Real Institución de Arquitectos Navales reconocen la excelencia en la ingeniería naval.
El transporte de mercancías resulta más caro para Malta: 35 millones de euros al año entre ETS, FuelEU y BAF.
Zebbug
La asociación de transportistas insta al gobierno a cuestionar una política europea diseñada para el continente.
CMA CGM ha finalizado la adquisición de FedEx Supply Chain.
Marsella/Atlanta
Con esta transacción, la presencia de CEVA Logistics en Norteamérica se ha triplicado.
Contships para encargar 10 buques alimentadores con opciones para 10+10 adicionales.
Atenas
Carta de intención con la empresa china Hubei Guangji Green Energy Shipbuilding Group Co.
DP World firma un acuerdo para desarrollar un puerto de aguas profundas en el estado de Ogun, en Nigeria.
Dubái
El proyecto incluye aproximadamente cuatro kilómetros de muelles.
Se han aprobado las nuevas regulaciones portuarias para Civitavecchia, Fiumicino y Gaeta.
Civitavecchia
Se ha aprobado el acuerdo de procedimiento con Interminal en Gaeta.
Kotug adquiere una participación mayoritaria en Vortex Offshore.
Róterdam
La empresa, con sede en Dubái, presta servicios marítimos a la industria offshore en Oriente Medio.
Más de 1.900 millones de euros en España para mejorar las conexiones por carretera y ferrocarril entre puertos.
Madrid
Las autoridades portuarias aportarán 875,1 millones de euros.
Attica Holdings vendió el buque ro-pax Levka Ori por 8,3 millones de euros.
Kallithea
El ferry fue construido en 1987.
El servicio ro-ro Trieste-Damietta de DFDS pasará a ser quincenal a mediados de octubre
Copenhague
Insertar un segundo buque en la ruta
La Academia Italiana de la Marina Mercante incrementa su cooperación con el puerto de Durres.
Génova
Se ha firmado un memorando de entendimiento.
El viernes se presentará en Livorno un libro sobre la historia del sistema portuario toscano.
Livorno
Comparación de los actores portuarios: desde las reformas de la década de 1990 hasta los retos del futuro.
Suardiaz recibe un buque transportador de automóviles propulsado por GNL con capacidad para 5.000 vehículos.
Madrid
Se espera un segundo buque PCTC a mediados de 2027.
Hapag-Lloyd eleva aún más sus previsiones para 2026.
Hamburgo
La fuerte demanda y el aumento de las tarifas de flete al contado están impulsando a la empresa a incrementar significativamente sus previsiones de EBITDA y EBIT.
La reunión pública de UNIPORT se celebrará en Roma el 6 de octubre.
Roma
Debate sobre la reforma portuaria y otros aspectos relevantes del sector.
Proyecto piloto para la producción y el uso de hidrógeno verde en el puerto de Savona.
Savona
Paroli (Autoridad Portuaria de Liguria Occidental): se ha identificado una zona portuaria para realizar trabajos.
Tarros y Nurminen Logistics lanzan un nuevo servicio intermodal escandinavo-mediterráneo.
La Spezia/Helsinki
La ruta terrestre conecta Örebro, Parma y La Spezia.
Se ha colocado el primer cajón del rompeolas que protege la planta de regasificación frente a la costa de Rávena.
Rávena
La obra marítima tendrá una longitud aproximada de 900 metros.
Fincantieri y PT PAL firman un acuerdo para la modernización de un buque de la Armada de Indonesia.
Trieste
Esta es la unidad "Kri Sriwijaya" (antes "Giuseppe Garibaldi")
En Italia, la economía azul tiene un valor de 225 mil millones de euros, y solo la industria náutica supera los 10 mil millones en exportaciones.
Roma
La iniciativa Focus On de SACE se presentó en el Salón Náutico de Génova.
Incendio a bordo del buque ro-ro Blue Carrier 2 de Blue Star Ferries.
Kallithea
Las 29 personas a bordo fueron evacuadas.
Los costes y los plazos para la reconstrucción de los cuatro astilleros de la Armada estadounidense están aumentando exponencialmente.
Washington
Si en 2018 se estimaba un coste de 21.000 millones de dólares y 20 años de trabajo, hoy la estimación es de 200.000 millones y al menos 50 años.
El sector del transporte marítimo se enfrenta a un triple desafío: la descarbonización, la geopolítica y la nueva geografía de la industria automovilística.
Paja
En la Convención Euromed de Grimaldi, el sector se enfrenta a nuevas normativas medioambientales, rutas cada vez más expuestas y el desplazamiento de la producción automovilística hacia el sudeste asiático.
Orizzonte Sistemi Navali firma un contrato de 3.700 millones de euros para la adquisición de dos destructores.
Trieste
El PPA "Domenico Millelire" ha sido entregado a la Armada.
Livorno: El Tribunal Supremo de Casación revoca las condenas en el caso de los muelles de Darsena Toscana.
Roma
El fallo de apelación revocó la absolución dictada por el tribunal y condenó a tres acusados por falsificación ideológica.
El puerto de Rijeka prevé cerrar 2026 con un tráfico récord de contenedores de 800.000 TEU.
Río
Con la nueva terminal en la isla de Krk, el tráfico podría aumentar a 1,7 millones de TEU.
Financiación para la energía eólica marina: Pichetto tranquiliza a Taranto, pero Taranto exige certezas.
Taranto
La financiación para el puerto de Apulia en 2026 se reduce a 13,9 millones de euros. Gugliotti espera una confirmación formal de los recursos restantes en 2027.
Reforma portuaria: La mayoría sigue adelante con Porti d'Italia SpA.
Roma
La Comisión de Transportes de la Cámara rechaza las enmiendas represivas de la oposición.
El puerto deportivo de Gela, Porto Rifugio, ha recibido un dictamen favorable para el dragado de las aguas del puerto.
Palermo
Greenbrier Europe fabricará el sistema de transbordo NIK para TX Logistik.
Troisdorf/Berlín
Permite la carga rápida de semirremolques no aptos para grúa en trenes.
Maersk abre su propio centro logístico en el corazón de Alemania.
Herleshausen
Ubicado en Herleshausen, tiene una superficie de 71.800 metros cuadrados.
PROXIMAS SALIDAS
Visual Sailing List
Salida
Destinación:
- orden alfabético
- nación
- aréa geogràfica
La empresa surcoreana HJ Shipbuilding & Construction Co. consigue pedidos para cuatro nuevos buques portacontenedores de 10.100 TEU.
Busan
El contrato tiene un valor total aproximado de 500 millones de dólares.
Partido Demócrata: La reforma portuaria del gobierno allana el camino a la privatización de los puertos italianos.
Roma
Ghio y Misiani: también les quita recursos y habilidades a los territorios.
Autoproducción portuaria: El Consejo de Estado niega la segmentabilidad de la autorización de conformidad con el artículo 16, párrafo 3.
Roma
La autorización "parcial" de Cartour en el puerto de Salerno ha sido suspendida.
El puerto de Miami cierra el año fiscal 2026 con un tráfico de cruceros récord.
Miami
Se ha superado el umbral de los diez millones de pasajeros, en comparación con los 8,56 millones del ejercicio económico anterior.
El Grupo Grimaldi ha recibido el nuevo buque transportador de automóviles y camiones Grande Egitto.
Nápoles
Su capacidad de carga alcanza los 9.800 CEU.
La reforma portuaria se debatirá en Génova el 2 de octubre.
Génova
Taller organizado por AdSP y la asociación Altero Matteoli.
Fratelli Cosulich refuerza su red logística con la apertura de Express Global Dubai.
Dubái
Teresa Cosulich será la responsable de la nueva oficina de logística.
"Un mar de Suiza" se celebrará en Lugano el 9 de octubre.
Lugano
Novena edición del Foro Internacional sobre Transporte e Infraestructura
Brullo Group encarga tres buques tanque para petróleo y productos químicos con una capacidad de 40.800 toneladas de peso muerto.
Roma
Pedido al astillero chino Anhui Shipyard
Nuevo ataque a un barco en el estrecho de Ormuz.
Southampton
Una bala causó heridas leves a dos miembros de la tripulación.
Se inaugura en Trieste un nuevo centro de producción, mantenimiento y almacenamiento de megayates.
Trieste
Trieste Shipyards fue fundada por Seadock (grupo Samer) y Yachting Expertise y es propiedad de Friulia.
Confitarma aplaude la iniciativa del gobierno para proteger a los buques italianos en el Mar Rojo.
Roma
Zanetti: La seguridad marítima es, en efecto, un componente de la seguridad económica nacional.
Los sindicatos aprueban la plataforma para el convenio colectivo único del sector naviero.
Roma
Filt, Fit y Uilt se estructura en torno a tres elementos centrales como salario, protección, participación y trece solicitudes concretas.
FHP Intermodal está aumentando la frecuencia de su servicio de transporte ferroviario de mercancías entre Fiorenzuola e Incoronata/Bari.
Milán
Llega hasta cinco días a la semana.
Este año, más de 2.000 grandes yates operaron a lo largo de las costas italianas.
Roma
Más un 10% para embarcaciones propias y una tendencia sustancialmente estable para las alquiladas.
El evento "Ciberresiliencia en el sector marítimo: defensa, normativa y cooperación europea" se celebrará en Roma el martes.
Roma
Está organizado por Var Group y Confitarma.
Con la adquisición de HTG, Smeup amplía su cartera en el sector de la logística y el transporte.
Erbusco
La empresa, con sede en Turín, se especializa en el desarrollo de software propietario.
Puertos de Arabia Saudita: El volumen de carga líquida a granel disminuirá drásticamente en 2025.
Riad
El tráfico total descendió a 298,3 millones de toneladas (-10,9%).
Una delegación del puerto lituano de Klaipeda visitó el puerto de Livorno.
Livorno
Comparación en profundidad de sus respectivos planes de desarrollo de infraestructura.
Nuevo servicio de OOCL entre el Mediterráneo occidental y Canadá.
Hong Kong
Colaboración con las compañías de Ocean Alliance y otras navieras.
El futuro del puerto es el tema central del evento que celebra el 80 aniversario de Assosped Venezia y Asamar Veneto.
Venecia
La conferencia del viernes será el plato fuerte del festival.
Aumento de trabajadores portuarios en los puertos de Monfalcone y Milazzo.
Roma
Luz verde de la Dirección General de Puertos, Logística e Intermodalidad del Ministerio del Interior.
El tráfico de mercancías en los puertos griegos está disminuyendo drásticamente.
El Pireo
Estancamiento en el número de pasajeros
Mercitalia Shunting & Terminal ha adquirido ocho locomotoras bimodales Eurolight Dual.
Roma
PUERTOS
Puertos italianos:
Ancona Génova Rávena
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Liorna Taranto
Cagliari Nápoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venecia
Interpuertos Italianos: lista Puertos del mundo: Mapa
BANCO DE DATOS
Armadores Reparadores navales y astilleros
Expedicionarios Abastecedores de bordo
Agencias marítimas Transportistas
MEETINGS
Evento de Assologistica para debatir la estrategia mediterránea para la competitividad italiana.
Roma
Se celebrará el próximo 30 de octubre en Nápoles.
La reunión pública de UNIPORT se celebrará en Roma el 6 de octubre.
Roma
Debate sobre la reforma portuaria y otros aspectos relevantes del sector.
››› Archivo
RESEÑA DE LA PRENSA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Reseña de la Prensa Archivo
FORUM de lo shipping y
de la logística
Intervento del presidente Tomaso Cognolato
Roma, 19 giugno 2025
››› Archivo
El tráfico de contenedores en el puerto de Hong Kong creció un 22,1% el mes pasado.
Hong Kong
El total para los primeros ocho meses de 2026 se mantiene sin cambios.
AGV Expo, una nueva feria europea dedicada a los vehículos autoguiados, se celebrará en Piacenza el próximo mes.
Génova
El evento también contará con un amplio programa de conferencias.
Se descubre un fraude transnacional masivo en el sector del transporte por carretera.
Chieti
Empleo ilegal de trabajadores no pertenecientes a la UE
El tráfico de carga en el puerto de Singapur disminuyó un -4,9% en agosto.
Singapur
En los primeros ocho meses de 2026, el puerto gestionó 30,7 millones de contenedores (+4,2%).
Cochin Shipyard y Drydocks World desarrollarán conjuntamente un nuevo centro internacional de reparación naval en Cochin.
Bombay
Un buque mercante iraní fue alcanzado en el estrecho de Ormuz.
Teherán/Southampton
Un marinero falleció y otros cuatro miembros de la tripulación resultaron heridos.
En julio, el tráfico de mercancías en el puerto de Ravenna creció un +6,7%.
Rávena
Se espera un fuerte descenso del -21,2% en agosto.
Giulio Stoppa es el nuevo secretario general de Trasportounito
Roma
Una elección de continuidad que al mismo tiempo marca el comienzo de una nueva fase.
La ceremonia de botadura del Viking Astrea tuvo lugar en el astillero Fincantieri en Ancona.
Ancona/Los Ángeles
El consejo de administración de Viking ha autorizado un programa de recompra de acciones de hasta 1.000 millones de dólares.
Meyer Werft comienza la construcción del crucero Carnival Tropicale.
Papenburg
Con un tonelaje bruto de 180.000 toneladas, podrá albergar a más de 6.000 pasajeros.
VTG vende su filial británica VTG Rail UK al fondo de pensiones USS.
Hamburgo
La empresa opera en el sector del arrendamiento de vagones de mercancías por ferrocarril.
La Guardia Costera de Génova alcanza su inspección número 100 de Control del Estado del Puerto en 2026.
Génova
Hasta el momento se han detectado más de 250 deficiencias.
ABB y Oceanly colaboran para integrar y optimizar el rendimiento y las operaciones de los buques.
Génova
Acuerdo estratégico entre Federlogistica y el Puerto de Xiamen.
Génova
Estudio de viabilidad para una conexión marítima entre el puerto chino y Génova.
El tráfico de contenedores en el Puerto de Los Ángeles se mantuvo estable en agosto.
Los Ángeles
El aumento de garajes vacíos ha compensado la disminución de los garajes llenos.
Gulftainer adquirirá una participación en la terminal de Suksawat en Tailandia.
Sharjah/Bangkok
Está ubicado a orillas del río Chao Phraya, en Bangkok.
Robo.ai crea una empresa especializada en seguridad marítima y submarina.
Abu Dabi
Al-Mansory: Produciremos localmente y ofreceremos soluciones para mercados de todo el mundo.
Kombiverkehr ha tomado el control total de la empresa española Combiberia.
Fráncfort del Meno
Las acciones fueron adquiridas de los otros 20 miembros.
Las fuerzas estadounidenses atacaron cinco petroleros iraníes.
Tampa
Ataques en el Golfo de Omán y cerca de la isla de Kharg.
Condiciones cumplidas para la adquisición de AD Ports por el fondo soberano de Abu Dhabi.
Abu Dabi
- Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA
tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Director: Bruno Bellio
Prohibida la reproducción, total o parcial, sin el explicito consentimento del editor
Búsqueda en inforMARE Presentación
Feed RSS Espacios publicitarios

inforMARE en Pdf
Móvil