testata inforMARE página de inicio
Cerca
18 de noviembre de 2026 - Año XXX
Periódico independiente sobre economía y política de transporte
14:52 GMT+1
LinkedInXFacebook
FORUM de lo shipping y
de la logística


Shipping and Shipbuilding Markets in 2003

I N D E X


The containership market in 2003


The charter market 
The fleet
The operators
The second-hand market


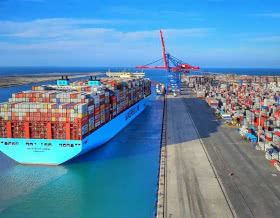
After the 2001 traumas, the year 2002 was a year of convalescence, and full health was restored in 2003. And what health! The seaborne containerised trades have boomed, box rates have risen on most trades and virtually all operators have renewed with profits. The year 2004 has opened on a rare optimistic note, which has not been seen since the early 1970s boom. 

Demand in containerships has reached record levels. An unprecedented wave of orders has poured into shipyards. Charter rates have soared and have yet to reach their climax. Opinions differ depending of course who you ask, but as one charterer puts it, 'The charter rates will probably be the only cloud in the otherwise blue sky'. 

This rise in container transportation, and international trade as a whole, is explained by several factors. First, the adjustment effect following a stagnant year 2002, then, a lot of countries saw their industrial production booming again, and third, one of these countries is China, with its already huge economy having logged a 9 % growth in 2003 and is export-oriented. 

The slump of 2001-2002 led to fears of durable overcapacity. In fact, the strong growth in transport demand observed over the past 18 months combines both the long term growth and a post-slump adjustment in volumes carried, although it owes much to the Chinese export boom. 

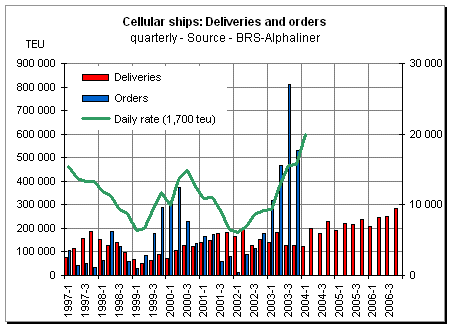
Taking a long-term view, the planned fleet expansion, in relation to the orderbook, will just match the growth of the demand - at least until end 2005. The balance is to remain in favour of owners for the whole of 2004 and for most of 2005. In late 2005 or 2006, the pendulum could swing back given the calendar of ship deliveries (the supply-demand balance may reach a critical stage). 

However, the depression -if any- could be temporary should there be a drop in deliveries in 2007. And with shipyards filling rapidly their 2007 building slots with tankers and bulk carriers (also much in demand), less capacity will be left to order big containerships in large quantities.
 

The China effect 

In 2003, Chinese ports have handled 48 million teu, against 37 million teu in 2002, i.e. an increase of some 30 % in one year (and daily movements of 100,000 teu). The performance may be difficult to be repeated in 2004, but even with a lesser rise, it will be a boon for carriers. 

So, the big question for 2004 (and the years to come) is: Will it go on? 

China has benefited for several years of a transfer of manufacturing activities from mature economies. There is no doubt that this movement is far from being completed, given China's large reservoir of cheap manpower. But it may slow down at some point, and exports may not rise as fast as they did. 

On the other side, as Chinese citizens get richer, they can afford more and more imported consumer products, or industrial components needed to manufacture consumer products. A side effect of these trends is that it would reduce trade imbalances. 

There are also uncertainties. It is too early to know if the Asian Bird Flu will have an impact on trade, but if the SARS epidemic is a guide, tourism could suffer, but trade would not (except for the poultry business). 

The Euro appreciation effect 

Another key factor is the dramatic evolution in currency rates, with the euro having appreciated by 20 % against the dollar during 2003, while most Asian currencies did not appreciate at the same rate, far from it. 2004 will witness the full year impact of the high purchasing power of the euro vis-a-vis Asian currencies, which will boost the Asia-Europe trade westbound, but may also deepens the eastbound-westbound imbalance. 

As for the Asia-US trades, the relative weakness of the dollar against most Asian currencies may dampen American buying of Asian products and may have a positive effect on the trade imbalance. However, it does not work for the China-US trade, as the Chinese yuan remains pegged to the dollar, despite pressing US demands to re-evaluate it. 

If trade remains as healthy as it is, one can wonder how far charter rates can go if the 2004 transpacific summer season sees volume grow by 8-10 %, not to mention the rises expected on Asia-Europe. It will lead to an acute shortage of containerships. Contrary to other peak times (such as the summer 2000), conbulkers will not be of great help as they obtain still higher rates on the bulk market than on the container market.
 

The charter market
 

Keeping the market share in 2004 will be a costly exercise for the operators which have been late to react. Those who have chartered ships several months in advance for 2004 delivery, will be more at ease. MSC has even gone further, buying 34 ships of 1,000 to 3,500 teu in 2003, which will allow savings on charter hires (despite the relatively high price paid for some of them). 

Of course, charterers react, but they have not much room to manoeuvre. The main sweetener to sky high rates is the length of charter periods. During the second half 2003, duration of 36 months have become a rule for ships of more than 2,500 teu, with owners conceding 10-15 % discount against the 12 months daily rates. 

With only a very few large ships left available in 2004, the most dynamic operators will have no options but to accept ultra high rates to snatch ships which arrive at the end of their charter from their current operators, who will obviously be ready themselves to pay the price to extend them. 

For these latter ones, losing the bid would lead to the disruption of well oiled weekly norias - unless of course they receive a sufficient number of large newbuildings or have covered their 2004 positions with charters negotiated in 2003, which is the case for half a dozen of the large operators. 

A number of operators have indeed covered their positions and protected themselves from possibly sky-high rates in 2004. Operators with a high component of owned ships in their fleet will be also in a quite confortable position. Conversely, high charter rates are a real burden for operators engaged with 100 % chartered tonnage, and box rates are far from having risen at the same pace. 

The latter ones count niche operators and some common feeder carriers. Now that their previous, relatively cheap charters arrive at their term, they have to extend the ships at the high rate. It may effectively encroach on their margins, and some of them are trying to rationalise their services in order to save one ship or two. Happily enough, they run a lot of smaller ships (under 1,500 teu) for which the rates remain reasonable. 

Similarly, large operators may cut down services for which the profitability is jeopardised by high charter rates, opting instead for alternatives, such as slot buying or partnership with rivals. 

As ships of around 4,000 teu are to remain a very scarce commodity during the year 2004, and even beyond, owners are in a position to ask, and obtain, rates of $ 40,000 for the few ships seeing their charter periods expire this year. Charterers will have to accept such high rates if cargo volumes dictate, to maintain their market share. 

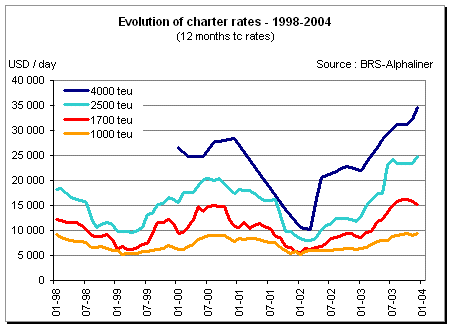
The charter market for 4,000 teu ships took off in 1999 and peaked in the summer 2000 at $ 29,000 before sinking in the 2001 gloom. It has since well recovered. 

In September 2003, an historical high of $ 32,500 has been reached for a 4,158 teu ship chartered for a period of six months. It is the first to be known as having broken the psychological $ 30,000 level. Two months later, a 4,038 teu ship went at the same $ 32,500 rate, but for a much longer period of 2.5 years (meaning that, had the ship been fixed for a 12 months period, the rate would have passed the $ 35,000 mark). 

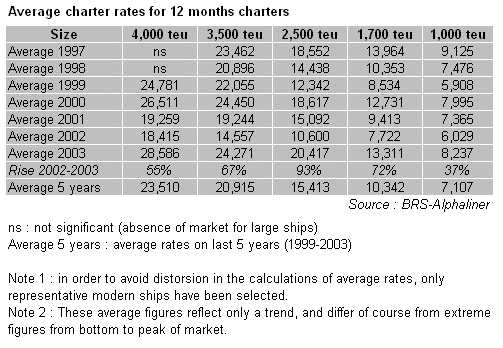
Ships of 2,500 teu have scored the highest rate rise in 2003, with average rate levels 93 % higher than in 2002, as can be seen from the accompanying table. 2,500 teu ships closed the year with daily hires of $ 24,750 for 12 months periods, up from the depressing lows of early 2002, when owners had to accept a miserable $ 8,000. And rates are still going up, with a 2,500 teu ship having reached an historic $ 30,000 for 12 months in early 2004. 

By comparison, the least advantaged size, 1,000 teu, gained only 37 % to $ 8,237, and is still well below the $ 10,500-11,000 averages observed in the mid-1990s. 

As for ships of 1,700 teu, they are traded in the same way that tramp cargo ships were traded 40 or 50 years ago, acting as stop gap ships and as sweeping ships on east-west trades as well as playing a key role on many secondary trades. 

Ships of this size come and go, with sometimes surprising movements in charter rates. This trend was well illustrated in December-January: while rates for B-170s (the 'barometer ship') fell just under $ 10,000 for 2 or 3 months periods, they remained above $ 15,000 for ships fixed for 12 months periods, and going up once the Chinese New Year festivities ended, with a all time record of $ 20,000 recorded in February 2004 for a B-170 fixed for 3 months. 

Rate rises have been much more modest for ships of around 1,000 teu. But rates could be pushed up in 2004 as charterers may be forced to charter smaller ships than they wish if the scarcity effect reach the 1,500-2,000 teu size. 

Actually, the highest rates observed in 2003 could well represent the average rate for 2004, if the world economy remains as sustained as it is, especially the Chinese one, as far as seaborne transportation is concerned. 

As for ships above 5,000 teu, they are not yet played on the daily charter market and are contracted for long periods (above five years). Ships of 5,500 teu are negotiated at around $ 28,000 for 7-10 years periods. As for charter rates for 8,000 teu ships hired for long periods (10 to 12 years), they stood in the $ 29,500 to $ 31,000 range in 2003, with a trend towards $ 32,000-33,000 in early 2004. Such ships could be ordered at a price of $ 70 million in early 2003, rising to around $ 80 million in early 2004.


Long-term charters become the rule

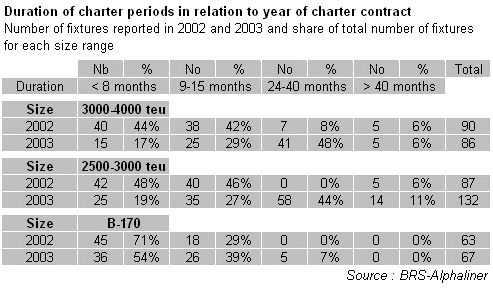
Periods of 24 to 40 months for 3,000-4,000 teu ships accounted for 48 % of the reported fixtures in 2003, against 8 % in 2002, according to a BRS-Alphaliner analysis, For 2,500-3,000 teu ships, the figure stands at 44 % in 2003 while no charters of such a duration was reported in 2002. The accompanying table details how the duration of charter periods evolved from 2002 to 2003.


The fleet

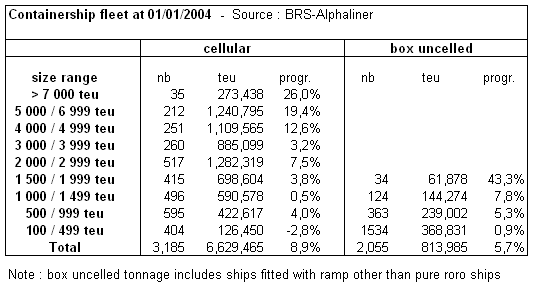
At 1st January 2004, the cellular fleet reached 3,185 ships for 6.63 million teu, in progression of 8.9 %, a relatively modest increase as the average annual progression during the past 10 years have reached 10.7 %. The cellular fleet accounts for 88.5% of the total fleet deployed on liner trades in teu terms.

2003 deliveries stood at 177 ships for 575,000 teu (against 201 ships for 646,000 teu in 2002). Orders stood at a record number of 520 ships for 2,123,000 teu, sending the total orderbook to 2.7 million teu in early 2004, representing 41 % of the existing fleet. The total value of cellular ships ordered in 2003 reached almost $ 22 billion. By comparison, in 2002, only 82 ships for 363,000 teu were ordered for $ 3.7 billion. As for deletions, 34 ships for 32,839 teu were sold for scrap last year (in 2002: 59 ships for 74,001 teu).

The cellular fleet is expected to reach 9.15 million teu in January 2007 (assuming no scrapping), i.e. an average annual progression of 11.3 % within the three years to come. Furthermore, virtually all the large ships are capable of speeds over 24 knots, meaning that the transport potential will rise even faster.

Given the schedule of deliveries, the size of the fleet may enter the 'danger zone' in the second half of 2005, and 2006 could be a year of low charter rates.

The value of such warnings is however very relative, because it is impossible to forecast the level of the demand with a sufficient accuracy in two or three years time. After all, supposing that Chinese exports remain sustained (even at a lower rate than observed in 2003) and that both the USA and Europe economies are healthy, driving with them other countries as well, it could lead to a transportation demand which could absorb the huge capacity which is to come on stream.

But sooner or later, a political or economic event of an unforeseeable nature will make the bubble burst, with the resulting nightmare that nobody wants to dream about.


The year of the 8,000 teu ship

Eighty percent of the capacity ordered in 2003 concerned ships of more than 4,000 teu. Among these large ships are 109 ships of over 7,500 teu, boosting the order book for such ships to 126 units at 1st January 2004, while only 30 ships above 7,500 teu are in service.

VLCS (Very Large Container Ships) of 8,000-10,000 teu will be the workhorses of the Asia-US and Asia Europe route during the second half of the decade. At the beginning of 2007, 140 ships of more than 7,500 teu will ply the high seas. It will be enough to run 12 Asia-Europe loops and 12 Asia-US loops (offering a weekly capacity of 100,000 teu on each of these two routes). In 2010, there could be as much as 300 of these giants in service.

The injection of VLCS on high volume routes will displace 5,000 teu tonnage on secondary east-west routes, while 3,000-4,500 teu ships will be displaced on niche east-west routes (such as those launched in 2003 between Asia and Black Sea) and of course on north-south routes.

This raises a question: what size range will be the most affected by the cascading triggered by massive deliveries of VLCS? Before trying an answer, it must be considered that 2,400-2,700 teu ships have also been much in favour in 2003, with 64 orders in this size range.

Actually, 2,500 teu ships are expected to play in 2006-2007 the roles currently ensured with 1,700 teu ships. There are already a lot of 2,500 teu ships around. These existing ships and the new ones will make redundant 1,700 teu ships on many trades.

In early 2007, there will be some 280 ships of 2,400-2,700 teu and there could be as much as 370 in the 1,500-1,750 teu range. It appears to be difficult to displace as much ships on feeder trades or regional trades. Thus the 1,500-1,700 teu ships will probably be the size which will suffer most from the cascading effect.

General cargo carriers tenfold increase in size 

Back in the 1960s, when containers started to appear on the decks of conventional cargo ships plying international routes, one would have been more than sceptical of hearing of 100,000 dwt general cargo carriers plying the high seas. It would have been interpreted as a year 2000 extravaganza. 

Such giant ships are today amongst us, with the generalisation of the 8,000 teu ship. Such ships allow a new step on the productivity scale to be climbed. An Asia-Europe service operated with eight ships of 8,000 teu plying at 25 knots carries about the same cargo quantities than eight services of conventional cargo vessels of the 1960s. 

In these pre-box times, a typical full scale Asia-Europe service employed about 20 ships of 10,000 dwt and 16 knots. In other words, a single 8,000 teu ship has a transport capacity matching the capacity of some 20 cargo vessels of 1960s vintage (taking into account dwt capacity, speed, and time spent in port). 


The operators

In 2003, the total teu capacity deployed on liner trades has grown by 9.3 %, reaching 7,485,000 teu as at 1st January 2004, against 6,850,000 teu one year earlier, according to BRS-Alphaliner data.

In deadweight terms, the figure stands at 7.3%, with 111.5 million dwt at 1st January 2004 against 104 million dwt one year earlier. These figures take into account all the types of ships deployed on liner trades. The cellular fleet itself amounts to 6,625,000 teu, i.e. 88.5 % of the total teu figure deployed on liner trades.

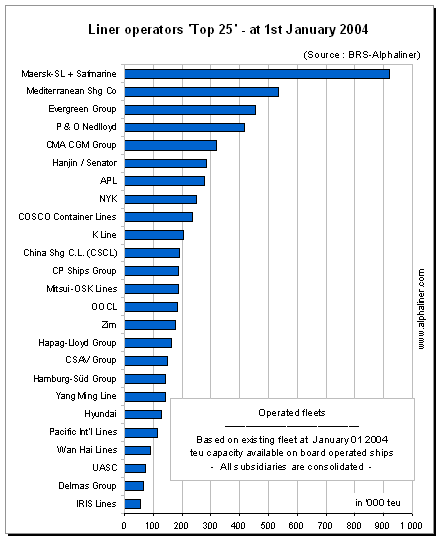
The capacity of the fleets of the Top 25 operators has grown by 12.3 % during the year 2003, which is in line with the average Top 25 growth rate observed since 1997. From 1st January 2003 to 1st January 2004, the Top 25 fleet has grown from 5,302,000 teu to 5,955,000 teu.

Its share of the world fleet deployed on liner trades has risen during the period from 77.4 % to 79.6 % in teu terms, confirming the concentration trend. The five largest carriers alone concentrate 35 % of the capacity effectively deployed on liner trades.

The largest of them, Maersk-SeaLand, operates a capacity of 920,000 teu, representing 12.2 % of the global active capacity in teu terms. The next in size is MSC, with 536,000 teu and 7 % of global market share.

Among the ten largest operators, CMA CGM is the incontestable teu gainer, as it has seen its fleet rise by 36 % in 2003. It has also logged the second strongest growth in absolute teu terms, with the addition of 84,414 teu, boosting its capacity to 319,180 teu.

CMA CGM has climbed from rank 8 to rank 5, passing Cosco, APL and Hanjin-Senator. While APL logged a fleet growth of 13.6%, Cosco and Hanjin-Senator saw their fleet decrease by 1.4% and 7.2% respectively.

On the mergers & acquisition side, the largest transaction concerned the buying of the Kien Hung Line services by Hamburg-S'd, enriching the already consistent network developed by this company on South America trades. The China Navigation Co, the shipping arm of the UK-based John Swire Group, has bought two multipurpose services, the Bank Line Europe-South Pacific service (bought from Andrew Weir) and the Indotrans US Gulf-South Asia service (bought from Oldendorff carriers). The other transactions are summed up in the accompanying table.

A new US-based carrier is born, U.S. Lines, which has launched a South China-California service in December, with 1,500-1,700 teu ships.

2004 will see the emergence of two new players on the Asia-Europe route, Pacific International Lines (PIL - Singapore) and Wan Hai (Taiwan). Both lines will offer a joint service employing eight ships averaging 2,500 teu (owned or chartered in 2003 for delivery in Q1 and Q2 2004). Although they are to start from scratch on this trade, both operators have strong trump cards to play because of their vast networks east of Suez, which allows them to offer much more than a mere east-west service.

2003 has been also marked by the launching of fully fledged Asia-Med services dedicated to regions usually feederised, such as Turkey and Black Sea or, to a lesser extent Adriatic. These initiatives have been launched by CMA CGM, MSC and Lloyd Triestino (all three lines dealt already with large volumes via feeders in these areas). These services employ a total of 22 ships of 2,000-3,000 teu,

These new services (to only mention them) have of course exerted a significant pressure on the charter market, and have helped to soak up the pool of available ships in the 2,400-3,000 teu range.

It must also be added that, in 2003, the extra volumes carried during the transpacific summer season have been dealt with in an orderly manner, i.e. through the launching of well defined extra loops, in contrast with 2002, when extra ships were chartered for single trips or round voyages, out of any schedules, and acting as sweeping ships.


Operators: transactions and significant moves in 2003 

Straight sales 
  • Hamburg-S'd bought the Kien Hung Liner services from the Kien Hung Shipping Co.

  • The China Navigation Co (Swire group) bought the Bank Line service from Andrew Weir

  • The China Navigation Co (Swire group) bought the Indotrans service from Oldendorff Carriers.

  • H. Stinnes Linien bought Ellerman share in the Beacon service from Hamburg-S'd

  •  Van Uden Maritime bought the Baltic Express Line (BEL) from Kersten Hunik.

  • Seawheel Ltd was bought by its management from the Simons Group.

  • Samskip bought 50 % of T&E Esco Container Lines A/S from Tschudi & Eitzen.

  •  Scandlines Deutschland GmbH bought T&E Esco Roro Line A/S from Esco.

  • Mann & Son Holdings Ltd (UK) bought Esco Eurolines from ESCO.

  • The P&O Group sold its remaining 50 % interest in Associated Bulk Carriers Ltd (ABC) to Eurotowers Holdings SA (Ofer Group) and wished to sell its 50 % share in P&O Nedlloyd.

  • MISC bought American Eagle Tankers (AET) from NOL - APL's parent company.

  • Clipper Elite Carriers (CEC) bought Tonnevold & Clausen A/S (T&C).

  • Spliethoff's has taken control of Wijnne & Barendsz.

  • Beluga Schiffahrt took over General Shipping & Chartering (GenChart).

  • The Clipper Group took control of 100% of Van Ommeren Clipper Shipholdings (VOC) with the acquisition and of the one-third share held by Vopak and of the one-third share held by Fortis Private Equity Netherlands.

  • The Clipper Group bought Lasco Shipping (USA), renamed Clipper Bulk (Portland) Inc. 

Transfers and moves within operating groups 
  • A.P. M'ller has merged the two companies A/S D/S Svendborg and D/S 1912 A/S into a single one: A.P. M'ller-Maersk.

  • Costa Container Lines and Grimadi-Genoa (Gilnavi) form a joint venture (with CCL as manager).

  • Hamburg-S'd abandoned its trade names 'Columbus Linie' and 'Crowley American Transport'. 

Cessations of activity 
  • Laline (Norway) closes its only container service (Benelux-Norway).

  • The Kien Hung Shg Co (Taiwan) and its Singapore subsidiary Powick Shipping Co cease to exist.

Significant other moves 
  • Foundation of U.S. Lines, USA - New transpacific operator.

  • Melfi Container Line, Cuba, launched a Med-Canada-Cuba service (replacing Coral C.L. service)

  • Tolteca Feeder Line (a jv of Wilh. Wilhelmsen and Mexican investors) launched a Mexico-Los Angeles service - Closed after two months of operation.

  • CSX Lines was renamed Hoizon Lines following its purchase by the Carlyle Group.

  • Ecomarine International Seatrade launch a West Africa feeder service

  • Swan Container Line Ltd., Isle of Man, is formed by Eurogate International, D'hle Schiffahrts Agentur and Fesco (service Germany-St Petersburg).

  • Kraftmar Container Line, a new operator based in Cyprus, launch intra Med services.

  • Smart Shipping Co Ltd, Hong Kong, develops ship operating activities.

  • The two main shareholders of Swedish Orient Line (SOL), Navalmar Transportes Maritimos Ltda and Imperial Shipping won their bid to took control of more than 75 % of the company, which was de-listed.

  • Marconsult & Thode Schiffahrt (MTC) split two years after the merger of MarConsult and Johs. Thode

 
The containership second-hand market in 2003

There were a total of 285 sales concluded in 2003 of which 181 fully-cellular containerships, 63 multi-purposes, 21 ro-ros, 5 ro-los and 15 conbulkers, for a total of nearly 460,000 teu. These figures show an increase of about 25 % additional transactions for the fully-cellular containerships over 2002, when 135 ships were sold. The progression by size range is even more significant. Sales of ships of 3,000 teu and more have been multiplied by 3.6 going from 13 to 47 transactions, whereas those of 2,000 to 3,000 teu have more or less stagnated (28 this year against 30).

There has been a slight increase in the sale of units of 1,000 to 2,000 teu, moving from 50 up to 60 deliveries. Finally, there were 46 ships with a capacity of less than 1,000 teu which changed hands in 2003 (against 42 the previous year).

In terms of teu capacity, we have moved from about 220,000 teu in 2002 to 384,000 teu this year, a progression of 57 %!

  • 47 ships of more than 3,000 teu

  • 28 ships between 2,000 and 3,000 teu

  • 60 ships between 1,000 and 2,000 teu

  • 46 ships below 1,000 teu.

Numerous 'en bloc' sales are to be noted such as those of Sovcomflot to MSC and Zodiac (10 ships of 3,005 teu each) or again Sinotrans for 6 ships sold to Papathomas and to MSC, with respectively 4 ships of 2,480 teu and 2 ships of 2,227 teu. Entreprises S&T released their only containerships, namely 5 units of 2,200 teu to Ahrenkiel.

The most active owner in 2003 was without any doubt MSC who acquired some thirty second-hand ships for a total of nearly 70,000 teu this year (some are to be delivered at the end of their charters in early 2004). This owner touched all sectors of the market from 1,000 up to 8,000 teu! The rule for MSC seems to be simple: if a line requires a ship for more than one or two years, why not buy it? This policy has so far paid off.

Outside MSC some operations were done directly with line operators such as PIL or Cosco, but the second-hand market was once again dominated by the usual investing owners such as the German KGs, Zodiac, Costamare, Danaos, etc.
 

Ships under 1,000 teu

 It is in this category that we find the largest number of ships sold to regular line operators. No buyer stands out in particular, but at a regional level, it is clearly the Far East that is the winner with nearly half of the market. For instance we can mention the en-bloc sale of the 969 teu, built in 1983, 'Noble River' and 'Precious River' from Coscon to Chao Yang at $2.8 million apiece. With little speculative element, ships' values in this sector of the market only went up between 10 to 15 %.
 

Ships of 1,000 to 2,000 teu

After a rather good year in 2002 with 50 ships sold, the 2003 vintage can boast of 60 transactions and an increase in values of 20 to 25 %. The highlight of transactions in this category was certainly that of 8 ships built between 1994 (2 units), 1998 and 1999 by the bankrupt owner Kien Hung Shipping, to PIL and Scholler at the incredible price, at the time, of respectively $ 13.5 million and $ 18.1 million at auction. The other interesting sale concerns the 4 'Sietas 170' of 1,680 teu, built in 2002, by Marlow Navigation to Kartig Shiffspool/V ship, at a price of $ 24.0 million each reflecting the 5-year charter attached to Maersk/Sealand at a rate of $ 12,950 per day. This year, unlike the precedent, combined sales (sales and time-charters back) were less numerous.
 

Ships of 2,000 to 3,000 teu

The phenomenon which we described last year concerning ships in this size has again been prevalent this year. Is it the fear to see this category of ship be progressively taken over by the bigger sizes, or is it simply the delivery to come of 118 giant ships currently under construction which is provoking this situation? Whatever the reason is, only 28 sales compared to 30 last year were concluded. This size of ship remains the 'reserved ground' of the German KGs who know how to profit from the popularity of these ships with their clients.

We can mention the sale of the 2,518 teu, 1986 built, 'Ambassador Bridge' to MSC at $ 15.5 million $ and the sale of the 2,602 teu, 2002 built, 'P&O Nedlloyd Barossa Valley' to Schulte for $ 33.75 million.
 

Ships over 3 000 teu

Two figures suffice to resume the activity in this sector of the fleet: 39 against 13. This is the comparison between the number of acquisitions this year and that of last year. Without counting the 428 ships which will be delivered to their owners between 2004 and 2007! As Bill Gates said several years ago about computing, 'it is neither the beginning nor the end but certainly the end of the beginning'. The Panamax and over-Panamax are indubitably at the sharp end of this market in which the price of ships continually rise in the same manner as freight rates. For reference we can mention the en-bloc sale of the 8-ship 'Berlin Senator' series, 3,007 teu, 1990 to 1993 built, to MSC at a price of $ 22.5 million apiece, and the en-bloc resale of the 'HS Columbus' and 'HS Barents', 4,994 teu, delivery 2005, at $ 57 million each to German buyers.

During the course of the year 2003 the appreciation in values has been in the order of 30 to 35 %. Ships available for sale have been scarce, and the strong demand for tonnage has helped to fill up the shipyards already fully occupied.
 

* * *

Always more! The 'little box' is again progressing and knows how to impose itself as a sure and efficient means of transport, and in most economic sectors. There are some pockets of resistance in some areas notably in the transport of reefer goods. Despite heavy investments, containers are finding it hard to take a definitive control over this sector which is putting up a good resistance! After several years of applying a policy of price dumping, the majority of line operators have decided to readjust their tariffs, and by doing so helping to favour the resurgence of the conventional reefer market.

 We can already announce that 2004 will carry on with the trend towards higher prices of containerships which started last year, as shipbuilding yards are currently saturated, and will remain so for the next three years.
 

›››Archivo
DESDE LA PRIMERA PÁGINA
Los armadores se unen en la OMI: "Se necesitan regulaciones mundiales sobre gases de efecto invernadero para brindar seguridad a las inversiones".
Londres/Washington
Nueve asociaciones que representan a la flota mercante mundial instan a los gobiernos a llegar a un acuerdo en la 85.ª reunión del MEPC que se celebrará en Londres.
Nova Marine Carriers adquiere el 25% de Terminal Nord Spa.
Rávena
La terminal portuaria de Ravenna del Grupo Sapir está especializada en la manipulación de áridos.
Ríos secos y una flota más grande: el tercer trimestre del grupo de cruceros Viking en medio del crecimiento y el aumento de los costos.
Los Ángeles
La crisis hídrica en Europa reduce los ingresos y el margen bruto ajustado en aproximadamente 100 millones de euros, mientras que la expansión de la flota aumenta los gastos operativos de los buques en un 17,6 %.
Foro Marítimo de Malta: El actual sistema de comercio de derechos de emisión marítimos de la UE es defectuoso y perjudicial.
Floriana/Bruselas
Una solución propuesta: aplicar el ETS a la carga, ya sea en contenedores o no, en lugar de al buque que la transporta. La MBB propone exenciones para las conexiones insulares.
Los armadores griegos critican duramente a Bruselas: la inflexibilidad de la UE pone en peligro las negociaciones de la OMI sobre la descarbonización del transporte marítimo.
El Pireo
En vísperas de las reuniones de Londres, la UGS denuncia el estancamiento y pide flexibilidad.
EU ETS, ESPO, FEPORT, WSC y Assarmatori piden que se refuercen los incentivos para el transbordo.
Más allá de la automatización: El trabajo portuario que aún queda por hacer
Río de Janeiro
En Río, la IDC analiza el año 2030, y un estudio brasileño se pregunta cuánto cuesta hoy en día, de forma saludable, el trabajo portuario.
Puerto de Civitavecchia: El número de pasajeros de cruceros aumentó un 10,8% en el tercer trimestre; disminuyen los retrasos en la carga y el tráfico de buques ro-ro.
Civitavecchia
En el tercer trimestre, los ingresos de la empresa francesa CMA CGM crecieron un +31,1%.
Marsella
El beneficio neto se triplicó. La flota transportó un número récord de contenedores.
Los puertos de Nápoles y Salerno registraron un aumento en el volumen de contenedores durante el segundo trimestre.
Nápoles
Se gestionaron 283.000 TEU (+7,8%). El total de carga aumentó un 4,7%. El tráfico de buques ro-ro se ralentizó y el tráfico de cruceros disminuyó.
Evergreen y WHL registran un fuerte crecimiento de sus ganancias trimestrales.
Taipéi
Las dos empresas taiwanesas han encargado 83.300 y 110.050 contenedores nuevos, respectivamente.
Los operadores de terminales se enfrentan: HHLA se ralentiza en el tercer trimestre, ICTSI acelera.
Hamburgo/Manila
La empresa alemana registró una caída del 8,5% en el tráfico de contenedores. ICTSI informó de un aumento del 8,1% (-1,8% en términos comparables).
Puerto de Hamburgo: El movimiento de contenedores se mantuvo estable en el tercer trimestre.
Hamburgo
Disminución del transporte de carga a granel. En los primeros nueve meses de 2026, el tráfico ascendió a 84,5 millones de toneladas (-2,6%).
Los pedidos de Fincantieri ascendieron a 3.570 millones de euros en el tercer trimestre, lo que supone un aumento del 180%.
Trieste
Los ingresos disminuyeron un 6%, hasta los 2.020 millones de euros, pero el EBITDA aumentó un 7%, hasta los 161 millones de euros.
Hapag-Lloyd registra un crecimiento trimestral de los ingresos del 27,9%, con un volumen de contenedores prácticamente sin cambios.
Hamburgo
La tarifa media de flete aumenta un 27,9% y respalda los resultados de la empresa alemana, que mejora aún más sus previsiones anuales.
HMM registra un tercer trimestre muy positivo tanto en el segmento de contenedores como en el de graneles.
Seúl
Durante ese período, la flota transportó 1,1 millones de contenedores (+8,4%).
La reforma que debía reducir la fragmentación de los puertos
Taranto
Desde la transición de 24 autoridades portuarias a 15 proveedores de servicios de publicidad (AdSP) hasta la entrada de Gallipoli en el sistema de Taranto: Italia continúa sumando puertos.
El puerto de Génova cerró el tercer trimestre con crecimiento, mientras que el tráfico de mercancías se mantuvo estable en Savona-Vado.
Génova
Puerto de Ravenna, septiembre ralentiza el ritmo
Rávena
En los primeros nueve meses de 2026, el tráfico de mercancías se mantiene por encima de los niveles del año pasado.
Estrecho del Bósforo: El tránsito de buques se desploma un 23,2%.
Ankara
El tráfico de buques graneleros se redujo a la mitad en el tercer trimestre. El descenso en los Dardanelos fue más moderado (-12,8%), mientras que el de buques portacontenedores se mantuvo estable.
En el tercer trimestre, las terminales de Eurokai gestionaron un tráfico récord de 3,9 millones de contenedores (+9,4%).
Hamburgo
En los primeros nueve meses de 2026, el total superó los 11,3 millones de TEU (+8,7%).
Sistema de comercio de derechos de emisión marítimos: Bruselas afirma que el sistema funciona. Los puertos temen la fuga de tráfico.
Bruselas
El último informe de la Comisión correspondiente a 2025 recoge una caída del 4 % en las emisiones y un cumplimiento superior al 99 %. Sin embargo, no aporta nuevos datos sobre el riesgo de evasión fiscal.
Los ingresos de Yang Ming crecieron un 52,4% en el tercer trimestre.
Keelung
Se prevé que las condiciones favorables para el transporte marítimo continúen durante la segunda mitad de 2026.
La flexibilización de las relaciones comerciales entre Estados Unidos y China también incluye puertos y astilleros.
Pekín
Pekín prorroga la suspensión de las tasas portuarias a los buques estadounidenses y la investigación sobre el impacto de las medidas estadounidenses en su industria marítima.
Alfa Laval adquiere Navtor por 700 millones de dólares.
Lund/Egersund
La empresa noruega que ofrece soluciones digitales para el transporte marítimo se integrará en la división Ocean del grupo sueco.
Boluda Towage adquiere la empresa holandesa de remolque Muller Dordrecht.
Dordrecht/Valencia
Cuenta con una flota de 16 remolcadores y ocho barcazas.
El mes pasado, el tránsito de buques por el Canal de Suez aumentó un 32,1%.
El Cairo
Crecimiento del +86,8% en tonelaje y del +94,1% en derechos de tránsito.
El ferrocarril, el espacio y el medio ambiente figuran entre las prioridades que surgen de las reuniones sobre el nuevo Plan de Ordenación Portuaria para los puertos de Génova y Savona-Vado.
Génova
La primera fase del proceso de consulta del AdSP ha concluido con 65 audiencias y la participación de más de 120 partes interesadas.
Fincantieri firma acuerdos con JA Solutions, Navantia y Naval Group.
París
Colaboración intensiva con la empresa danesa en el campo de los sistemas modulares y en contenedores avanzados para unidades navales reconfigurables.
Menos contenedores, más ingresos: la división marítima de Maersk crece al ritmo de las tarifas de flete.
Copenhague
En el tercer trimestre, los volúmenes cayeron un -0,8%, pero las tarifas y la congestión elevaron el EBIT de Ocean a 2.600 millones.
De Egipto a Marruecos, pasando por Gioia Tauro: ¿el ETS desvía los contenedores a puertos fuera de la UE?
Bruselas
Un estudio promovido por Assarmatori detecta indicios de transferencia ya en marcha y exige correcciones.
ONE buques transportaron volúmenes récord de contenedores en el tercer trimestre.
Singapur
Los ingresos aumentaron un 36,5%. Este desempeño se vio impulsado por la demanda de envíos transpacíficos.
Wallenius Wilhelmsen registra un tercer trimestre con ingresos récord que, sin embargo, crecen menos que los costos.
Lysaker
Ligera disminución en el volumen de vehículos transportados por la flota.
Canal de Suez: Señales de recuperación del tráfico marítimo en septiembre
Ismailia
Sin embargo, las repercusiones de la crisis en el Mar Rojo persisten.
En Taranto, la crisis del acero sigue lastrando el puerto.
Taranto
El transporte de carga líquida a granel está manteniendo los volúmenes, pero el tráfico general ha disminuido un 5,7 % en los primeros nueve meses de 2026. El tráfico de contenedores sigue siendo volátil.
Aranceles portuarios estadounidenses a buques chinos, coalición comercial pide suspensión permanente
Washington
Cientos de asociaciones han escrito a Greer antes de la fecha límite del 9 de enero de 2027. Entre ellas se encuentra el Consejo Mundial del Transporte Marítimo.
T&E: El ETS debería convertirse en el motor de las inversiones en combustibles sintéticos para aeronaves y buques.
Bruselas
Las exigencias de la organización para la reforma del ETS: más recursos europeos, un fondo específico y subastas bilaterales.
En el primer semestre de 2026, el tráfico de mercancías en el puerto de Livorno cayó un -3,6%.
Livorno
Los puertos de Elba también experimentaron un descenso (-3,3%). El puerto de Piombino, en cambio, se desmarcó de esta tendencia con un aumento del +5,7%.
El volumen de carga disminuyó en los puertos del sur del Adriático durante el primer semestre de 2026.
Bari
El sistema pierde 676 mil toneladas en comparación con 2025, casi todas entre los dos puertos más grandes.
En el tercer trimestre, el tráfico marítimo en el Canal de Panamá se mantuvo estable.
Panamá/Balboa
Sin embargo, el tonelaje de los buques y el volumen de mercancías en tránsito están aumentando.
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
El sistema marítimo de comercio de derechos de emisión (ETS) y FEPORT apoyan las medidas contra la evasión fiscal relacionadas con la carga.
Bruselas
Es la solución más eficaz —afirma la federación de operadores de terminales europeos— para proteger la competitividad de los puertos de la UE.
COSCO Shipping, ingresos +29% y beneficios +82%: el mérito se debe a las tarifas de flete, más que a los volúmenes.
Hong Kong
El mercado transpacífico es el motor que impulsa las cuentas del grupo chino.
Norwegian Cruise Line Holdings registra un aumento en sus ingresos netos, pero una disminución en sus márgenes durante el tercer trimestre.
Miami
APM Terminals firma una nueva fase de expansión para el puerto marroquí de Tánger Med.
Rabat
Se prevé una inversión de más de 800 millones de dólares para construir 1,2 kilómetros de muelles.
El puerto de Barcelona lanza un proyecto para reducir las terminales de cruceros de siete a cinco.
Barcelona
Revisión de la concesión de Creuers del Port de Barcelona
Boluda y Samskip, una nueva fusión en el transporte marítimo de corta distancia europeo.
Valencia/Róterdam
El grupo español ha firmado un acuerdo para adquirir todas las actividades del grupo holandés y ampliar su plataforma multimodal.
Astilleros indios en la lista de reciclaje de buques de la UE, ECSA pide a los eurodiputados que la aprueben.
Bruselas
Llamamiento para rechazar una moción que se opone a la propuesta de la Comisión.
CVC DIF ha adquirido una participación mayoritaria en el astillero español Cernaval.
Schiphol
La empresa ibérica emplea aproximadamente a 275 personas.
Contship Italia adquiere el grupo Tarros.
Melzo/La Spezia
Todas las actividades y activos que conforman el sistema de servicios integrados del grupo La Spezia cambian de manos.
El crucero residencial de Villa Vie Residences fue suspendido.
Fort Lauderdale/Sihanoukville
La compañía atribuye el encallamiento del buque al aumento del precio del combustible y está trabajando en un plan de reestructuración y recapitalización.
Wallenius Wilhelmsen encarga cuatro PCTC de 9.900 CEU más ocho opciones.
Lysaker
Acuerdo con el astillero chino Jinling Shipyard (Jiangsu)
Royal Caribbean registra ingresos trimestrales récord de 5.590 millones de dólares. Se revisan al alza las previsiones para el año completo 2026.
Miami
EBITDA de 2.530 millones y 2,68 millones de pasajeros en el período julio-septiembre
La seguridad marítima, el sistema de transporte de emisiones (ETS), los pabellones y el empleo son los temas centrales del informe del presidente de Confitarma.
Roma
Zanetti aboga por una alianza europea para la libertad de navegación, un pacto nacional para la transición y menos burocracia para la bandera italiana.
Global Ports Holding firma un acuerdo de concesión para el puerto de cruceros de San Vicente.
Estanbul
El acuerdo tiene una duración de 30 años.
La familia Sunde vende Color Line a Stena.
Gotemburgo
Un grupo sueco de ferris adquiere la mayor compañía de ferris de cruceros de Noruega.
Puertos chinos, la carrera se está ralentizando.
Pekín
Tras 25 años de crecimiento, el tráfico de mercancías está prácticamente paralizado, pero los contenedores siguen batiendo récords.
Lorenzo Sanna es el nuevo presidente de ANPAN
Sestri Levante
Parmigiani: En lo que respecta al Protocolo de Alta Mar, deberíamos retomar la declaración escrita del comandante.
2027 volverá a ser un año récord para la industria italiana de cruceros.
Livorno
Se prevé la llegada de aproximadamente 16 millones de pasajeros, con un crecimiento del +4%.
Reforma portuaria: la Comisión debate la posibilidad de reservar y rechazar únicamente buques.
Roma
La Cámara de Diputados no ha aprobado ninguna enmienda en tres semanas. La única excepción es el personal de la Autoridad Portuaria.
Transporte por carretera, tregua inminente. El gobierno libera fondos para combustible diésel y reformas estructurales.
Roma
Se aprueba un decreto de emergencia con créditos fiscales, prohibición de arrendamiento y protección contra el recargo por combustible.
Conferencia "Haciendo volar al país: el transporte aéreo de mercancías, el motor del Made in Italy"
Roma
Organizado por ENAC, se celebrará el 24 de noviembre en Roma.
Hupac ha reintroducido el tren lanzadera Busto Arsizio/Gallarate - Barcelona.
Assago/Chiasso
Se elabora con tres rotaciones semanales.
Saipem se adjudica dos nuevos contratos de perforación en alta mar en Egipto y Surinam.
Milán
Pedidos con un valor total aproximado de 181 millones de dólares.
UPS firma un acuerdo para adquirir la empresa australiana Smartways Logistics.
Atlanta
La empresa presta servicios de logística sanitaria en Australia y Nueva Zelanda.
Demolidos 20 silos en el puerto de Catania
Catania
Algunos fragmentos de los murales se transformarán en obras de arte.
El volumen de carga contenerizada que se movió en el puerto de Barcelona aumentó un 14,3% en octubre.
Barcelona
El tráfico de transbordo va en aumento.
El tráfico de contenedores en el puerto de Long Beach creció un 11,7% el mes pasado.
Long Beach/Nueva York
El número de contenedores en Nueva York disminuyó un -1,7% en el tercer trimestre de 2026.
SRI Global adquiere The Italian Sea Group por 220 millones de euros.
Marina di Carrara
El próximo lunes se reunirá el Consejo de Administración de la empresa náutica en Marina di Carrara.
CEVA Logistics abre un nuevo almacén en Castel San Giovanni
Milán
50.000 metros cuadrados de espacio dedicados a las actividades de Daikin
El tráfico de contenedores en el puerto de Hong Kong aumentó un 12,9% en octubre.
Hong Kong
En los primeros diez meses de 2026 se gestionaron 11,15 millones de TEU (+3,5%).
Gulftainer y TiL construirán una terminal de contenedores en el puerto indonesio de Marunda.
Sharjah
Acuerdo con el PT indonesio Karya Citra Nusantara
Rosetti Marino firma un nuevo contrato para operaciones en alta mar en el mar Mediterráneo.
Rávena
El contrato está valorado en más de 400 millones de euros.
El sistema portuario de Liguria con Liguria International en Logitrans en Estambul
Estanbul
Se destacan servicios y proyectos para fortalecer las conexiones logísticas entre Turquía y el sur de Europa.
Boluda Towage adquiere la empresa ecuatoriana de remolque Cititug.
Valencia
La transacción incluye la transferencia de propiedad de cinco remolcadores.
El puerto de Los Ángeles establece un récord de tráfico de contenedores en octubre.
Los Ángeles
En los primeros diez meses de 2026 se gestionaron 9,11 millones de TEU (+5,1%).
En 2027, el puerto de Rávena prevé recibir 365.000 pasajeros de cruceros.
Rávena
Hasta la fecha, hay programadas 115 escalas de cruceros.
Giosuè Vezzuto nombrado director general de RINA Services
Génova
Los resultados financieros trimestrales de Finnlines muestran un fuerte crecimiento.
Helsinki
Los ingresos aumentaron un 26,2% en el período de julio a septiembre. Las ganancias aumentaron un 81,6%.
El Puerto de Tarragona ha ganado el Premio ESPO 2026.
Bruselas
El área que rodea la sede de la Autoridad Portuaria se ha convertido en un espacio sostenible, resiliente e intergeneracional.
En el tercer trimestre, el tráfico de carga en los puertos croatas creció un +18,5%.
Zagreb
El número de pasajeros de vuelos regulares se mantuvo estable, mientras que el de pasajeros de cruceros aumentó un 6,2%.
Tardino ha sido nombrado presidente del Comité de la ESPO para las Regiones Ultraperiféricas e Islas
Palermo
En Bruselas, reunión con Raffaele Fitto sobre cuestiones estratégicas de los puertos italianos.
La empresa danesa DFDS registra ingresos trimestrales récord
Copenhague
En el período julio-septiembre, los buques del grupo transportaron 10,1 millones de metros lineales de material rodante y 2,1 millones de pasajeros (-3,6%).
En los puertos montenegrinos, el volumen de carga está disminuyendo mientras que el de pasajeros está aumentando.
Podgorica
El tráfico con Italia está disminuyendo.
Ansis Zeltins ha sido reelegido presidente de la Organización Europea de Puertos Marítimos.
Bruselas
La Asociación de Puertos de Islandia se ha unido a ESPO.
Este año, Blu Navy registró un crecimiento del +12% en el número de pasajeros transportados.
Portoferraio
El número de vehículos transportados también aumentó (+11%).
El 17 de noviembre tendrá lugar en Rávena una conferencia sobre el presente y el futuro de las Autopistas Marítimas en Italia.
Rávena
En 1991 comenzó la línea marítima Ravenna-Catania.
Se celebra el compromiso del Partido Demócrata con las enmiendas relativas a las obras portuarias y marítimas.
Roma
Es la única fuerza política —subraya el sindicato— que ha respondido hasta ahora a nuestras solicitudes de reunión.
En los primeros nueve meses de 2026, el tráfico de contenedores en el puerto de Gioia Tauro creció un +1,7%.
Roma
Actualización económica del Banco de Italia sobre la economía de Calabria
FS Engineering y Sogesid han firmado un acuerdo para desarrollar proyectos de infraestructura en Italia y en el extranjero.
Roma
Enfoque nacional en la infraestructura portuaria, los sistemas logísticos y la infraestructura relacionada con la movilidad.
El Tribunal Administrativo Regional (TAR) del Lacio ha suspendido el aumento de las tasas de los centros de formación marítima.
Roma
Se ha concedido la solicitud de medidas cautelares presentada por CONFORMAR y ANIFORMAR. La audiencia sobre el fondo del asunto está programada para el 16 de marzo.
Los ingresos de Global Ship Lease aumentaron un 4,5% en el tercer trimestre de 2026.
Atenas
Nueva línea de crédito de 1.000 millones de dólares para financiar 15 nuevos buques portacontenedores.
El curso Papagno de Assagenti ha formado a más de mil jóvenes agentes y corredores marítimos.
Génova
Se ofrece a nivel nacional desde 2017.
AIRIDEA, una nueva conexión aérea entre Génova y Marsella con el apoyo de Genova Industrie Navali.
Génova
Servicio diseñado para facilitar los viajes relacionados con el trabajo entre las dos ciudades.
Fincantieri y Republikorp forman una empresa conjunta para fortalecer la industria de construcción naval de Indonesia.
París
El Propeller Club Port of Sardinia se fundó hoy en Cagliari.
Génova
Es el club número 27 de la asociación nacional, que cuenta con más de 1.600 miembros.
La empresa india Adani Ports adquiere al operador de terminales holandés Evos.
Ahmedabad/Ámsterdam
Transacción por valor de 2.560 millones de euros.
Hapag-Lloyd ha completado la adquisición de una participación del 25% en APM Terminals Maasvlakte II.
Hamburgo
La junta directiva de Interferry ha sido renovada.
Victoria
Nombramientos en la conferencia del 50 aniversario de la asociación en Bangkok.
DIS reporta un crecimiento en sus ganancias durante el tercer trimestre de 2026.
Luxemburgo
Tras el auge del segundo trimestre, la rentabilidad se mantiene en niveles altos.
Arsenio Domínguez seguirá al frente de la OMI hasta finales de 2031.
Londres
El Consejo ha tomado una decisión. El nombramiento debe ser ratificado por la asamblea.
DHL experimentó un crecimiento en el tercer trimestre, impulsado por los servicios de mensajería urgente y transporte de mercancías, que generaron ingresos y beneficios.
Bonn
Ingresos de 22.700 millones de euros (+12,6%) y EBIT de 1.700 millones de euros (+16,2%).
El Tribunal General de la UE ha anulado la retirada del reconocimiento del registro naval ruso.
Luxemburgo
La prohibición de inversiones y la prohibición de transacciones siguen vigentes.
El bioGNL italiano busca hacerse un hueco entre el ETS, FuelEU y los incentivos nacionales.
Rimini
Assogasliquidi solicita procedimientos de certificación más sencillos y medidas para que la producción nacional sea competitiva.
Fincantieri y Leonardo llegan a un acuerdo para reforzar el papel de Orizzonte Sistemi Navali.
Trieste/Roma
Las empresas pretenden consolidar el papel industrial y comercial de la empresa conjunta.
Puerto de Rijeka: Diversas cargas impulsan el avance de Luka Rijeka, mientras que la terminal de contenedores Adriatic Gate pierde terreno.
Rijeka
En los primeros nueve meses de 2026, el tráfico total cayó un -15% hasta los 3,83 millones de toneladas.
Confetra: El gobierno quiere abolir el impuesto sobre las parcelas pequeñas.
Roma
Satisfacción con las decisiones del gobierno en el proyecto de ley de presupuesto.
Se ha establecido una comunidad portuaria de energías renovables en Taranto.
Taranto
Entre los objetivos, destaca el desarrollo del puerto de Apulia como centro energético.
Filt y Uilt, el sistema de trabajo portuario temporal no es anacrónico.
Roma
Definirlo de esta manera —denuncian los sindicatos— significa distorsionar la naturaleza y la función del artículo 17 de la Ley 84/94.
Nuevo récord trimestral de tráfico de mercancías en los puertos albaneses.
Tirana
En el período julio-septiembre, el número de pasajeros disminuyó un -5,4%.
PROXIMAS SALIDAS
Visual Sailing List
Salida
Destinación:
- orden alfabético
- nación
- aréa geogràfica
Los beneficios de FedEx están aumentando, pero el beneficio neto cae un 68%.
Memphis
La pérdida de capital no monetaria relacionada con la escisión de FedEx Freight pesa mucho
Kalmar registró un crecimiento del 22% en nuevos pedidos en el tercer trimestre.
Helsinki
Facturación estable. Beneficio neto un 14% inferior.
En el tercer trimestre, las ventas de contenedores producidos por CIMC aumentaron un 30%.
Hong Kong
La actividad comercial se vio impulsada por los contenedores secos (+36%). Las unidades refrigeradas disminuyeron un 28%.
Puertos, nuevas inversiones en Toscana y Cerdeña
Livorno/Cagliari
Se han aprobado los presupuestos para 2027 de las dos autoridades portuarias. Entre los proyectos más destacados se incluyen el muelle de Piombino, las obras en Livorno y los proyectos de dragado y electrificación en los puertos de Cerdeña.
Encontrar personal cualificado en los puertos italianos es cada vez más difícil.
Nápoles
Un análisis realizado por Randstad Research de 13 perfiles profesionales también pone de manifiesto un marcado desequilibrio de género.
COSCO Shipping Ports registra ingresos récord en el tercer trimestre.
Hong Kong
En el período de julio a septiembre, el beneficio neto fue de 102,5 millones de dólares (+3,4%).
Aprobación del presupuesto previsto para 2027 y del Plan Operativo de Transporte (POT) para el periodo 2027-2029 de la Autoridad Portuaria del Sur del Mar Tirreno y Jónico.
Gioia Tauro
El documento de previsiones muestra unos ingresos de aproximadamente 24 millones de euros y unos gastos de aproximadamente 88 millones.
Bongiovanni, natural de Ravenna, ha sido confirmado como presidente del Comité Juvenil de la Federación.
Roma
Renovación de la junta directiva de la federación
Se ha aprobado el Plan Operativo Trienal 2027-2029 para el Sistema Portuario del Adriático Central.
Ancona
Se prevén inversiones por valor de 308 millones de euros, de los cuales 218 millones se destinarán a la región de Las Marcas y 91 millones a Abruzzo.
Se ha aprobado el presupuesto previsto para 2027 de la Autoridad Portuaria de Liguria Occidental.
Génova
El nuevo recargo sobre los productos se pospone hasta 2028.
DP World inaugura un almacén con temperatura controlada cerca de Bolonia.
Bolonia
Superficie de 22 mil metros cuadrados
Saipem gana dos nuevos contratos de perforación en alta mar.
Milán
El valor total de los pedidos asciende a aproximadamente 121 millones de dólares.
Hanwha pone el astillero naval de Filadelfia bajo el control de la División de Defensa.
Arlington
El objetivo es integrar la construcción de buques comerciales y militares.
Los puertos de La Spezia y Carrara aprueban el Programa Trienal de Obras Públicas 2027-2029 y el Presupuesto 2027.
La Spezia
Pisano: PTLP concreto y coherente con los recursos actualmente disponibles.
Concesiones portuarias: El Tribunal Administrativo Regional (TAR) bloquea el aumento de tarifas de 2025.
Roma
Se ha aceptado el recurso presentado por Assiterminal y dieciséis empresas portuarias.
Wärtsilä registra aumentos trimestrales en los pedidos, pero no en el segmento marítimo.
Helsinki
En el periodo julio-septiembre la empresa registró un beneficio neto de 125 millones de euros (-31%).
Montaresi fue nombrado secretario general de la Autoridad Portuaria del Mar de Liguria Oriental por otros cuatro años.
La Spezia
Renovación del mandato a propuesta del Presidente Pisano
Doble ceremonia para dos barcos de Explora Journeys en el astillero Fincantieri en Génova.
Génova
Lanzamiento del "Explora V" y ceremonia de colocación de la primera moneda del "Explora VI".
La empresa italiana CMD pasa a estar bajo el control del grupo emiratí EDGE.
Abu Dabi/Roma
Los primos Mariano y Giorgio Negri conservan una participación significativa.
La Autoridad Portuaria del Tirreno Septentrional presenta el nuevo diseño del puerto de Piombino.
Livorno
Gariglio: Un paso concreto hacia la reconversión industrial y el futuro de Piombino.
FS Logistix ha adquirido seis nuevas locomotoras CZ LOKO para servicios de transporte de mercancías y maniobras.
Roma/Praga
Este es el cuarto pedido de este tipo que recibe la empresa checa en diez años.
Puerto de Bremerhaven: El crucero Mein Schiff 3 colisionó con dos buques portacontenedores.
Bremen
No hubo heridos. El crucero fue cancelado.
Paolo Moretti ha sido nombrado consejero delegado de RINA Spa.
Génova
Giosuè Vezzuto ha asumido el cargo de director ejecutivo de RINA Services.
HD Hyundai y Kiewit establecerán una empresa conjunta en un nuevo astillero en Estados Unidos.
Houston/Seúl
Está prevista la construcción de buques tanto militares como comerciales.
Los pedidos trimestrales de equipos portuarios de Konecranes disminuyen a medida que aumentan los ingresos.
Helsinki
El tercer trimestre de Kuehne+Nagel fue muy positivo.
Schindellegi
Crecimiento de los resultados económicos y operativos en todos los segmentos de negocio.
La apuesta de Wildcat por la defensa estadounidense: acuerdo exclusivo con el histórico astillero de Fraser.
Superior
El funcionamiento del fondo de Miami Beach forma parte del plan del gobierno para relanzar la industria naval estadounidense.
Puerto de Ancona: Se emite la primera autorización ZES individual.
Ancona
Se ha desbloqueado una inversión de tres millones de euros en la construcción de yates.
PUERTOS
Puertos italianos:
Ancona Génova Rávena
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Liorna Taranto
Cagliari Nápoli Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venecia
Interpuertos Italianos: lista Puertos del mundo: Mapa
BANCO DE DATOS
Armadores Reparadores navales y astilleros
Expedicionarios Abastecedores de bordo
Agencias marítimas Transportistas
MEETINGS
Conferencia "Haciendo volar al país: el transporte aéreo de mercancías, el motor del Made in Italy"
Roma
Organizado por ENAC, se celebrará el 24 de noviembre en Roma.
El 17 de noviembre tendrá lugar en Rávena una conferencia sobre el presente y el futuro de las Autopistas Marítimas en Italia.
Rávena
En 1991 comenzó la línea marítima Ravenna-Catania.
››› Archivo
RESEÑA DE LA PRENSA
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Reseña de la Prensa Archivo
FORUM de lo shipping y
de la logística
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› Archivo
El acceso al puerto de Ravenna está autorizado para buques con un calado máximo de 11,00 metros.
Rávena
Benevolente: es un paso fundamental para el desarrollo económico y estratégico del aeropuerto.
El puerto de Génova extiende la autorización de inspección de alimentos a la terminal PSA SECH.
Génova
La disposición del Ministerio de Salud amplía las categorías de productos que pueden estar sujetos a control.
El jueves, la Unione Interporti Riuniti presentará el proyecto ELODIE en la Cámara de Diputados.
Roma
El objetivo es crear una federación digital de interpuertos.
ABB registra pedidos récord por valor de 12.000 millones de dólares en el tercer trimestre.
Zúrich
Los ingresos y las ganancias también aumentaron, mientras que el grupo anunció una empresa conjunta con Mitsubishi Electric.
En el tercer trimestre de 2026, el volumen de contenedores en el puerto de Barcelona disminuyó un -9,2%.
Barcelona
El descenso se debió a una reducción del 19,9% en el tráfico de transbordo.
Las terminales de COSCO Shipping Ports establecen un nuevo récord trimestral de procesamiento de contenedores.
Hong Kong
En el período julio-septiembre también los volúmenes manejados por CMPort
En agosto, los puertos de Liguria Occidental gestionaron 5,2 millones de toneladas de mercancías (+1,6).
Génova
En Génova se registró un aumento del +6,1%, mientras que Savona-Vado Ligure sufrió un descenso del -10,0%.
Raben Italia abre un nuevo almacén en Pomezia.
Milán
El objetivo es consolidar el posicionamiento y la expansión territorial en el transporte por carretera.
- Via Raffaele Paolucci 17r/19r - 16129 Génova - ITALIA
tel.: +39.010.2462122, fax: +39.010.2516768, e-mail
Partita iva: 03532950106
Registrazione Stampa 33/96 Tribunale di Genova
Director: Bruno Bellio
Prohibida la reproducción, total o parcial, sin el explicito consentimento del editor
Búsqueda en inforMARE Presentación
Feed RSS Espacios publicitarios

inforMARE en Pdf
Móvil