testata inforMARE Home Page
Cerca
19 November 2026 - Year XXX
Independent journal on economy and transport policy
04:11 GMT+1
LinkedInXFacebook
FORUM of Shipping
and Logistics


Shipping and Shipbuilding Markets in 2002

I N D E X


The dry bulk market in 2002


The freight market:
     Capesize - Panamax - Handymax & Handysize
The second-hand market:
     Capesize - Panamax - Handymax & Handysize
 

The dry bulk shipping market finished the year 2002 taking all sizes into account at levels that had not been seen since the end of 2000, at a time when the overall economic conditions were far more favourable. At the beginning of the year nothing indicated such a sprightly resurgence, and few analysts would have stuck their necks out to predict freight rates around $25,000 per day for modern Capesizes. As in other sectors of the shipping market, everyone was betting on a recovery of the American economy, and in its wake that of countries in the European Union, occurring during the course of the second half of 2002. This was by no means the case, and the uncertainties linked to the American intervention and their allies in Iraq, more than ever casts a pall over the world economy and the confidence necessary for a rebound. Japan is for its part still stuck in its quagmire which has been going on for several years.

The factors that have contributed to the rise in freight rates during the year, mainly with effect from September, are essentially:

  • a significant increase in raw materials into China, Japan and other South East Asian countries ; whilst total world growth has been flat the exception is China which registers annual increases in GNP of the order of 7,5 %.

  • a decrease in the number of newbuildings coming onto the market compared to previous years, at least as concerns the Capesizes and Panamaxes.

  • a steady increase in the cost of bunkers, which was caused initially by the policy of reducing OPEC production, and secondly by the fear of conflict in the Gulf.

  • at the end of the year, shutdown for maintenance of some Japanese nuclear power stations, resulting in a sizeable increase of steam coal imports.

We will attempt a rapid tour of the main events in the dry bulk market over the course of the past 12 months. For reference, the Baltic Dry index which began the year at 876 points ended at 1739, the highest level since November 2000.

Based on the statistics published by IISI at the end of January 2003, world crude steel production has totalled slightly over 900 million tons in 2002, an increase of 6,4 % over 2001. The lion's share of this rise is due to China producing 181 million tons, compared to 150 million in 2001, or an increase of 20,3 %. For comparison, in 1995 Chinese steel production was 95 million tons and was below that of Japan's 101 million tons. In 2002, Japanese production reached 107 million, an increase of 4,7 % compared to 2001, an impressive achievement if we consider the lethargy of the Japanese economy. Production in the E.U. only increased by 0,1 %, and to illustrate the contrasting situations, French production increased by 5,6 %, whereas Germany was only able to come up with a modest rise of 0,4 %. The restrictive measures taken by the U.S. seem to be taking effect since after months of declining production, American steel figures for 2002 finished with an increase of 2,5 % over 2001 with 92 million tons. Japanese and Korean steel producers who fed the Chinese market throughout the year, helped alleviate the American and European markets, thus allowing steel prices to find their levels of the first quarter 2000 after two years of decline. With steel production being the driving force of the Capesize market, the higher production levels were bound to have an influence on freight rates.

The healthy standing of the Capesize market was partly due to the growth in Chinese imports of iron ore. Based on provisional figures these should exceed 110 million tons in 2002, 20 million more than in 2001. In addition, the share of Chinese imports coming from Brazil should represent 27,1 % of the 2002 total, compared to 17,3 % in 1998, thereby stretching the ton/miles. If this trend continues, in a short time Chinese imports of iron ore will surpass that of the E.U. and of Japan. Still in the realm of raw materials, Japan was obliged to import nearly 6 million tons of additional steam coal over the period September 2002 to April 2003, following the shutdown of 9 nuclear power stations out of a total of 18, run by Tokyo Electric Co. which helped to sustain the Panamax market in the Pacific during the fourth quarter. In the case of cereals, Australia suffered one of its worst droughts in history and its crop was halved, thus redirecting imports from the South East Asian countries. Grain trade according to the International Grain Council should remain stable for the 2002-2003 season around 207 million tons.

In the industrial sector new mergers were formed in 2002. In Japan, NKK and Kawasaki Steel united forces in a new entity, JFE Steel, which initiates the first merger in the steel industry in the country and follows the example within the European scene which underwent a profound restructuring two years earlier. The combined production of the two companies totals some 28 million tons. At the same time, NSC, Sumitomo Metals and Kobe Steel have entered negotiations in view of getting together. And still within the steel sector, US Steel made a proposal to take over National Steel for $750 million but as yet unconfirmed. Also to be noted is the intended acquisition of the aluminium division of Corus by Pechiney.

Finally, at the end of the year, the IMO against the better judgement of certain countries, decided to impose double-hulls on vessels over 150 meters for all newbuildings. This ruling still has to be ratified within the context of the SOLAS convention by January 2004 at the latest. Certain owners having anticipated this decision, placed orders for double-hulled ships already during the course of the 2002.


Parallel to the increase in freight rates over the year, one should not forget the rise in bunker prices. The price of IFO 380 cst went from $100 per ton in January, basis delivery Rotterdam, to over $150 per ton in December, which corresponds for a Capesize to an increase of 50 cents on an average freight rate of $ 8,15 on a voyage Brasil ' Rotterdam.
 

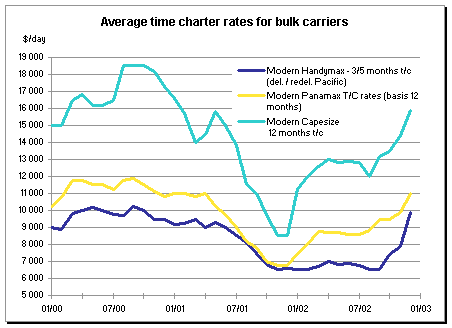
To appreciate the movement of freight increases in the Atlantic we can cite a few examples. On the iron ore route from Brazil to China, rates went from $ 6/ton in January to $ 7,50 on average from March to August, to finish the year at $ 13,50. Transatlantic cargoes took off from $ 4 at the beginning of the year to fix at over $8 twelve months later. This hike was also repeated within the coal market out of South Africa. At the start of 2002, cargoes were fixed to North Europe at under $ 5 per ton, to achieve $ 8 at the end of September, and finish the year at above $10. In the Pacific, there was a similar phenomenon despite the fact that the Atlantic market benefited with a premium over the Pacific basin. Freights on the iron ore route from Australia to China doubled between January and December. Backhaul routes however suffered from the drop in liftings of minerals from Australia to Europe. This strong rise in rates was even more pronounced on the time-charter market. Modern large ships, fixed for fronthaul trips with delivery Rotterdam to the Far East via Brazil were achieving $ 8,000 in January and ended the year above $ 26,000. Modern ships of 170,000 dwt chartered for 12 months witnessed their rates reach over $ 18,000 at the end of the year, some $ 7,000 more than they could expect in January 2002.
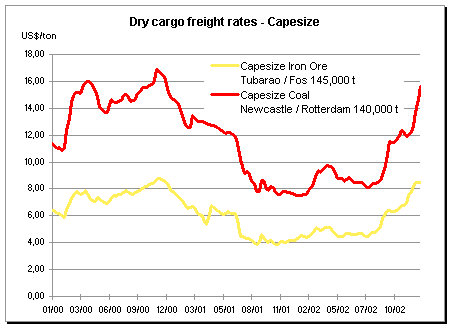

 
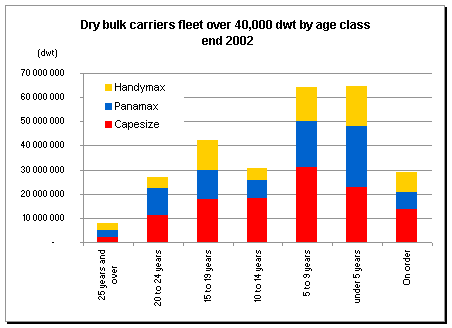
The Capesize fleet has remained relatively stable and delivery of new tonnage was limited in 2002. Twenty-five ships for 4 million dwt were delivered, against 34 in 2001, whereas 17 ships were scrapped (of which 8 were combined carriers). In 2003 additions to the fleet will stay limited, despite a small growth, due to the fact that there were very few major orders during the period 2000-2001. Thirty-two additional ships, for 5 million dwt, should come into service in the course of this year. However the sudden upsurge in freight rates during the second half of last year, linked to low construction costs, and the availability of early slots in certain Japanese shipyards, plus the creation of new building docks in China has contributed to a flood of orders to be delivered as from 2004. No less than 50 ships have been ordered in 2002, including several big carriers of 200,000 dwt for Japanese account.

In 2001 in line with large tanker owners, some of the principal players in the Capesize market have created the pool Cape International which combined some 80 ships. This unit had its difficulties in getting formed, since in October 2002 Zodiac who had the biggest contribution to the pool decided to withdraw. Elsewhere, the Capesize and Panamax fleet of two other major players in the dry bulk scene Coeclerici and Ceres Hellenic joined forces. At the end of the year the Belgian Cobelfret strengthened its position within the Capesize market by acquiring the 50 % held by BHP-Billiton in its affiliate Cobam.

The Panamax market began the year 2002 at depressed levels. Inter-zone rates for modern ships did not surpass $5,500-6,000 per day. The spread between the two basins, Atlantic and Pacific, have progressively widened. All newbuildings were delivered into the Pacific area, and the reduction of voyage times (ton/miles), quickly repositioning these ships into their original area of operation, weighed heavily on freight levels. As with the Capesizes, levels from the Atlantic to the Pacific rose during the first three quarters, with modern vessels obtaining daily returns rising from about $ 7,500 in January to nearly $13,000 end December. This situation lasted until the beginning of the fourth quarter when volumes of coal coming out of China primarily for Japanese destination helped push rates even higher. At the end of the year however the Pacific market went along with its alter ego in the Atlantic. Backhaul rates stayed low throughout the year, with owners having tonnage in the zone being prepared to make sacrifices in order to return to the more advantageous Atlantic.
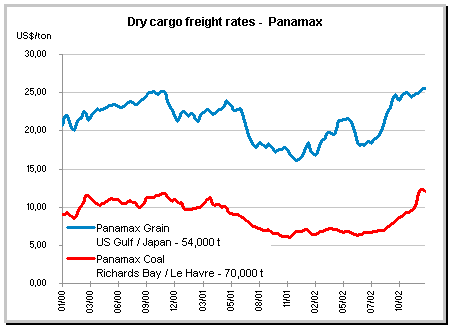
 

As with the Capesize fleet, the number of Panamaxes delivered in 2002 was down compared to the previous year. Fifty-five ships for 4,1 million dwt entered service, as against 116 in 2001. This drop in deliveries will be even more marked in 2003, as only 26 new ships for less than 2 million dwt, will come out of the Asian shipyards. For the same reasons as with the Capes, orders burgeoned during the second half, mainly with the Japanese yards and to a lesser extent with the Chinese. As a result, 76 orders were placed in 2002, with deliveries being spread out over 2004 and 2005. Scrappings remained modest, with only 29 units of which 4 combined ships removed from the fleet. Finally a new type of Panamax should be noted, the Kamsarmax, its name being derived from a port in Guinea and developed by the Japanese shipyard Tsuneishi, with a deadweight of 82,000 (length of 229 meters, width of 32,26 meters, draught of 14,35 meters) and capacity of 97,000 cbm and of which seven units have been ordered.

The bulk carrier market of Handymax and Handysize offers a more contrasted picture. On the one hand, the Pacific market has suffered for a long time from the high level of newbuildings being delivered, since on average nearly 3 ships per week have been coming onto the market in 2002. Conversely the Atlantic market has been well supported mainly with traffic to the Far East. Important volumes of steel, fertilisers, and cereals leaving the Black Sea, the Mediterranean and North Europe helped sustain freight rates for a good part of the year. Consequently large, modern Handymaxes have been able to obtain rates reaching up to $14,000 per day for voyages to the Far East. Satisfactory levels were seen throughout the year, with levels never falling below $10,000 per day after April. As with the Panamax, Handymax owners not wishing to go off into the Pacific zone at any price, were able to get premiums on these destinations. At the start of the year the Atlantic market was hesitant, with the grain trade out of South America being slow to get off the mark. For ships between 43,000 ' 45,000 dwt, daily returns for inter-Atlantic business averaged at $8,500 per day, the lowest being in January at below $7,000 per day, and the highest in December at around $10,000 per day. The Indian Ocean and the Middle East Gulf zones also benefited from a generally favourable market due to traffic into India or China. The Pacific market remained depressed for the first three quarters of 2002, with levels for inter-zone voyages rarely going over $ 6,000 per day. During the last quarter freight rates firmed up steadily to the point of reaching Atlantic levels right at the end of the year.

Handysize ships traditionally enjoy a less volatile market and started the year below $6,000 per day for short periods reached levels near $7,000 during the last quarter. The Handysize fleet is old and should therefore diminish progressively over the coming years, and with no new units coming in to replace those leaving the fleet bringing about changes mainly in the sugar and fertiliser trade.

The decrease in deliveries of Handymax and Handysizes in 2002 compared to 2001 had less of an affect on the large size of dry bulk carriers, but the persistent flow of nearly 3 ships per week coming out of the Asian yards put continuous pressure on the Pacific market. 148 ships for 6,2 million dwt came into service compared to 155 the previous year. With the same causes producing the same effects, orders were extremely high in 2002.

About 160 new contracts were signed with confirmation this year of the attraction for Super Handymaxes, ships over 50,000 dwt, for which an increasing number was ordered with Japanese and Chinese shipyards. Against these deliveries, there was an offset of 123 old units which went to scrap. But contrary to the Capesize and Panamax, the volume of deliveries will continue to be felt in 2003 since nearly 130 ships should be delivered.

The new year's prospects are similar to those at the end of 2002. Iron ore and coal volumes are on an upward trend. Moreover, concerning the Capesize and above all Panamaxes, new deliveries will be very restricted in 2003, giving a welcomed respite for owners. Two uncertainties remain however : during the course of the year will the hopes of a world economic revival, repeatedly delayed, give an additional stimulus to the dry bulk movements? Will China, the driving force in the dry bulk market, continue to charge ahead at full speed and for how long? The American military intervention in Iraq, even of short duration, will put back this recovery and would bring about repercussions which nobody can precisely foresee.

* * *

The future is always right!


The second-hand market
 
The Capesize second-hand market (80,000 dwt and over)

Following as always the freight market with a certain variation both in time as well as intensity, the second-hand Capesize market globally tracked the drop in the last months of 2001 before picking up at the beginning of 2002.

This increase continued until March / April. Prices then remained stable before firming up significantly again as from September. The year finished on a very strong upbeat.
We have noted some 36 sales for further trading (17 comprising ships delivered between 1990 and 2002, and 19 Capesize built between 1981 and 1989). Nine ships built between 1971 and 1982 were scrapped this year, roughly 1.14 million dwt, whereas 26 ships were delivered amounting to 4.25 million dwt.

Owners lured by a modest orderbook (about 9.3% of the existing fleet at the end of 2001), reasonable prices for construction and historically low dollar interest rates, were unable to resist the temptation to order on a massive scale.

There have been about fifty firm orders placed in the course of the year 2002, for a total capacity of 8.5 million dwt, figures which are worth comparing with the 20 orders of 2001 representing a total tonnage of 3.37 million dwt.

The strong rise in freight rates during the last quarter has however benefited primarily to second-hand ships available on a prompt basis.

Based on construction in a good shipyard, fully classed and in good condition, the following prices apply:


January 2002


December 2002

150 000 dwt

built in 1990

about $14 / 14.25 m

about $ 17.25 / 17.5 m

150 000 dwt

built in 1995

about $18.5 / 19 m

about $ 24.5 m

There are some encouraging signs at the end of 2002 and optimism is in the air, even if some of uncertainties cloud the market, such as the collateral effects of the war in Iraq, new regulations being studied for the introduction of double-hulls for bulk carriers, etc.

One should also not forget that the tonnage on order has to be absorbed by the market. In 2003, there will be some 5.0 million dwt added, followed by a further 6.4 million dwt in 2004 and with the firm orders recorded so far, over 2.0 million for 2005.
  

The Panamax, Handymax & Handysize bulk carriers second-hand market

Predicting what the future may bring can be dangerous, whereas if a prediction proves to be correct then whoever was bold enough to make it, can but refer to it.

In our last year's annual review covering these sizes we were of the opinion that 'values had bottomed out' and that anyone interested in investing in these sizes should be inspecting and offering as soon as possible as we felt that in the near future prices would increase. In the case of Panamax and Handymax size we were in fact cautioning prospective buyers of a possible 'stampede', which would in turn cause prices to climb faster and without any real logic.

It seems that this is what more or less happened.

Freight rates were rather stable for the first part of the year but the feeling that prices had reached the bottom fuelled competition amongst prospective buyers resulting in higher prices than the last comparable sales. Then as soon as buyers started to cool down the freight markets started to firm-up resulting in very good chartering returns for dry bulk owners, which was the perfect reason for any potential buyer to go out hunting again.

Prices across the board increased about 10 / 15 % within a few months, whereas the overall price increase at the end of 2002 reached a very healthy 25 % and in some cases has exceeded 30 % when compared to the beginning of 2002 / end of 2001. Once this trend was firmly established in buyer's minds, it caused a flurry of activity in the sale & purchase market.

A total of about 330 ships reportedly changed hands during 2002, this is about double the number of ships when compared to 2001. A 100 % increase in the number of transactions.
Looking closer at the three size segments, we note that when compared to the previous year there was an increase in the reported number of sales as follows:

75 % more Panamax sales

(2002 : 70 ships / 2001 : 40 ships)

144 % more Handymax sales

(2002 : 117 ships / 2001 : 48 ships)

86 % more Handysize sales

(2002 : 143 ships / 2001 : 77 ships)

It would seem that the Greek shipping community was quick to realise this trend and actively participated in purchasing vessels thus keeping the leading role amongst the buyers of second-hand bulk tonnage. Greek buyers bought about 165 vessels representing about 50 % of the reported sales in the three size categories under consideration.

Favourite amongst the Greek buyers proved to be the Panamax size for which they picked up about 64 % of the ships sold during the year, the Handymax category coming second with about 58 % of all transactions reported to Greek buyers, leaving the Handysize in the third place but with a respectable 35 % of the sales being reported to Greeks.

Chinese buyers were always present especially in the Handymax and Handysize segments the latter being their favourite 'hunting ground'.

Korean buyers where more active than in the past few years, especially in the latter part of 2002 going after ships in all three categories, although early 1980's built Panamax and Handymax ships seemed to have been what they were most keen on.

As one would expect when looking at sales for demolition, the number of ships reported sold for recycling during 2002 is significantly less than those sold during the previous year.

  • Panamax: about 0.9 million dwt was removed this year, 13 vessels, representing a decrease of about 60 % over 2001 figures.

  • Handymax: about 0.86 million dwt was removed during 2002, 20 vessels, representing a decrease of about 24 % over 2001 figures.

  • Handysize: about 2.12 million dwt were removed this year, 78 vessels, representing a decrease of about 15 % over 2001 figures.

Less ships going for recycling resulted in a sharp increase of prices obtained per light ton displacement from buyers of such tonnage which at the end of 2002 for a bulk carrier stands at about US$ 170-175 per ton.
 

  • Panamax

    A total of 70 ships were reported sold during 2002 and among these:

    • 1 ship was built in 1977 - she was sold for further trading to Indian buyers,

    • 49 ships were built in the 1980's (70 % of the reported sales), of which 14 were over 20 years old, 28 were 15-20 years old, 7 were 10-15 years old,

    • 19 ships were built in the 1990's (27 % of the reported sales), of which 14 were less than 10 years old,

    • 1 vessel was built in 2000 ' she was sold to Greek buyers.

    At the end of 2002 a 10 years old Panamax bulk carrier worth about US$ 11.75 / 12.0 million, representing an increase of about 30 / 33 % over a period of 12 months, a 5 years old Panamax bulk carrier worth about US$ 17.0 / 17.25 million, which represents about 28 % appreciation when compared to the value one year earlier in December 2001.

  • Handymax (35 000 ' 52 000 tpl)

    A total of 117 ships were reported sold during 2002 and among these:

    • 11 ships were built in the 1970's (about 9.5 % of the total Handymax sales), the oldest being a 1976-built vessel sold for further trading to Turkish buyers,

    • 67 ships were built in the 1980's (about 57 % of the total Handymax sales),
      ' 3 ships were over 20 years old,
      ' 59 ships were 15-20 years old,
      ' 5 ships were built 1988-1989,

    • 35 ships were built in the 90's (about 30 % of the total Handymax sales),
      ' 27 ships were 5-10 years old,
      ' 8 ships were 5 years old or younger,

    • 4 ships were built in 2000 representing about 3.5 % of the total Handymax sales.

At the end of 2002 a 10 years old Handymax bulk carrier worth about US$ 10.5 / 11.0 million, representing an increase of about 20 / 22 % over a period of 12 months, a 5 years old Handymax bulk carrier worth about US$ 14.25 / 14.5 million which represents a 16 % appreciation when compared to one year earlier in December 2001.

  • Handysize (18 000 ' 35 000 tpl)

    A total of 143 ships were reported sold during 2002 and among these:

    • 28 ships were built in the 1970's (about 19.6 % of the total Handy sales).

    • 86 ships were built in the 1980's (about 60 % of the total Handy sales)

    • 26 ships were over 20 years old,

    • 55 ships were 15-20 years old,

    • 5 ships were built 1988 / 89.

    • 28 ships were built in the 1990's (about 19.6 % of the total Handy sales)

    • 3 ships were over 10 years old,

    • 18 ships were 5 / 10 years old,

    • 7 ships were 5 years old or younger.

    • 1 ship was built in 2001, she was sold to Cuban interests.

    At the end of 2002 a 10 years old Handy bulk carrier worth about US$ 8.0 / 8.25 million, representing an increase of about 15 % over a period of 12 months, a 5 years old Handy bulk carrier worth about US$ 11.25 million, which represents a 7 % appreciation when compared to one year earlier in December 2001.

* * *

Concluding this review of the second-hand Panamax, Handymax and Handysize bulk carrier market and looking ahead, a lot will obviously depend on which way the freight markets will be heading for, but at the end of the year the feeling is that the dry bulk market maintains it's momentum and this should be felt on vessels' prices.

We would therefore expect values to remain firm with a slight upward trend over the next few months.
 

›››File
FROM THE HOME PAGE
ZIM's third quarter is a highlight. But the merger with Hapag-Lloyd remains on hold.
Haifa
Revenues at 2.71 billion (+53%) thanks above all to transpacific freight
Switzerland: Government proposes extending support for rail freight traffic through the Alps until 2035
Bern
A total of 486 million francs has been allocated for unaccompanied combined transport.
Shipowners unite at the IMO: "Global greenhouse gas regulations are needed to provide certainty for investments."
London/Washington
Nine associations representing the world's commercial fleet are calling on governments to agree at MEPC 85 in London.
Nova Marine Carriers acquires 25% of Terminal Nord Spa
Ravenna
The Sapir Group's Ravenna port terminal specializes in the handling of aggregates
Dry rivers and a larger fleet: Viking cruise group's third quarter amid growth and rising costs
Los Angeles
The water crisis in Europe reduces revenues and adjusted gross margin by approximately €100 million, while fleet expansion increases vessel operating expenses by +17.6%.
Malta Maritime Forum: The current EU maritime ETS is flawed and damaging.
Floriana/Brussels
A proposed fix: apply the ETS to cargo, whether containerized or not, rather than to the vessel carrying it. The MBB proposes exemptions for island connections.
Greek shipowners slam Brussels: EU inflexibility jeopardizes IMO negotiations on shipping decarbonization
Piraeus
On the eve of the London meetings, the UGS denounces the stalemate and calls for flexibility
EU ETS, ESPO, FEPORT, WSC and Assarmatori call for strengthening incentives for transhipment
Beyond Automation: The Port Work That Remains
Rio de Janeiro
In Rio, the IDC discusses 2030, and a Brazilian study asks how much, in a healthy way, port work costs today.
Port of Civitavecchia: Cruise passenger numbers up 10.8% in the third quarter; cargo holdups and ro-ro traffic decline.
Civitavecchia
In the third quarter, revenues of French company CMA CGM grew by +31.1%
Marseille
Net profit tripled. The fleet transported a record number of containers.
Ports of Naples and Salerno saw container throughput growth in the second quarter.
Naples
283,000 TEUs were handled (+7.8%). Total freight increased by 4.7%. Ro-ro traffic slowed and cruise traffic declined.
Evergreen and WHL post strong quarterly earnings growth
Taipei
The two Taiwanese companies have ordered 83,300 and 110,050 new containers respectively.
Terminal Operators Face Off: HHLA Slows in Third Quarter, ICTSI Accelerates
Hamburg/Manila
The German company saw an 8.5% drop in container traffic. ICTSI reported an 8.1% increase (-1.8% on a like-for-like basis).
Port of Hamburg: Container throughput stable in third quarter
Hamburg
Bulk cargo decline. In the first nine months of 2026, traffic amounted to 84.5 million tons (-2.6%).
Fincantieri's orders totaled €3.57 billion in the third quarter, up 180%.
Trieste
Revenues down 6% to €2.02 billion, but EBITDA rises 7% to €161 million.
Hapag-Lloyd reports quarterly revenue growth of 27.9% with container volumes virtually unchanged.
Hamburg
Average freight rate rises by 27.9% and supports the results of the German company, which further improves its annual estimates
HMM records a very positive third quarter in both the container and bulk segments
Seoul
During the period the fleet transported 1.1 million containers (+8.4%)
The reform that was supposed to reduce the fragmentation of ports
Taranto
From the transition from 24 Port Authorities to 15 AdSPs to the entry of Gallipoli into the Taranto system: Italy continues to add ports
The port of Genoa closed the third quarter with growth, while freight traffic remained stable in Savona-Vado.
Genoa
Port of Ravenna, September slows down
Ravenna
In the first nine months of 2026, freight traffic remained above last year's levels
Bosphorus Strait: Ship transits plummet by 23.2%.
Ankara
Bulk carrier passages halved in the third quarter. The decline in the Dardanelles was more moderate (-12.8%), while container ships held steady.
In the third quarter, Eurokai terminals handled a record traffic of 3.9 million containers (+9.4%)
Hamburg
In the first nine months of 2026 the total was over 11.3 million TEUs (+8.7%)
Maritime ETS: Brussels says the system is working. Ports fear traffic flight.
Brussels
The Commission's latest report for 2025 reports a 4% drop in emissions and compliance above 99%. However, it provides no new data on the risk of tax evasion.
Yang Ming's revenues grew by 52.4% in the third quarter
Keelung
A continuation of favorable conditions for shipping is expected in the latter part of 2026
US-China trade easing also involves ports and shipyards
Beijing
Beijing extends suspension of port charges on US vessels and investigation into the impact of the US measures on its maritime industry
Alfa Laval Acquires Navtor for $700 Million
Lund/Egersund
The Norwegian company providing digital solutions for shipping will be integrated into the Ocean division of the Swedish group
Boluda Towage acquires Dutch towing company Muller Dordrecht
Dordrecht/Valencia
It has a fleet of 16 tugboats and eight barges
Last month, vessel transits through the Suez Canal increased by +32.1%
Cairo
Growth of +86.8% in tonnage and +94.1% in transit rights
Rail, space, and the environment are among the priorities emerging from meetings on the new Port Planning Scheme for the ports of Genoa and Savona-Vado.
Genoa
The first phase of the AdSP's listening process has concluded with 65 hearings and over 120 stakeholders involved.
Fincantieri signs agreements with JA Solutions, Navantia, and Naval Group
Paris
Intensive collaboration with the Danish company in the field of advanced modular and containerized systems for reconfigurable naval units
Fewer containers, more revenue: Maersk's maritime division grows with freight rates
Copenhagen
In the third quarter, volumes fell by -0.8%, but tariffs and congestion raised Ocean's EBIT to 2.6 billion
From Egypt to Morocco, passing through Gioia Tauro: does the ETS shift containers to non-EU ports?
Brussels
A study promoted by Assarmatori sees signs of transfer already underway and calls for corrections
ONE vessels carried record container volumes in the third quarter
Singapore
Revenues increased by 36.5%. Performance driven by demand for transpacific shipments.
Wallenius Wilhelmsen records a third quarter with record revenues which, however, grow less than costs
Lysaker
Slight decrease in the volumes of vehicles transported by the fleet
Suez Canal: Signs of a recovery in ship traffic in September
Ismailia
However, the repercussions of the crisis in the Red Sea persist
Taranto, the steel crisis continues to weigh on the port.
Taranto
Liquid bulk cargoes are supporting volumes, but overall traffic is down 5.7% in the first nine months of 2026. Container traffic remains volatile.
US port tariffs on Chinese ships, trade coalition calls for permanent suspension
Washington
Hundreds of associations have written to Greer ahead of the January 9, 2027, deadline. Among them is the World Shipping Council.
T&E: The ETS should become the driving force behind investments in e-fuels for aircraft and ships.
Brussels
The organization's demands for the overhaul of the ETS: more European resources, a dedicated fund, and two-sided auctions
In the first half of 2026, freight traffic in the port of Livorno fell by -3.6%
Livorno
Ports on Elba also experienced a decline (-3.3%). The port of Piombino bucked the trend with a +5.7%.
Cargo volumes down in Southern Adriatic ports in the first six months of 2026
Bari
The system loses 676 thousand tons compared to 2025, almost all between the two largest ports
In the third quarter, ship traffic in the Panama Canal remained stable
Panama/Balboa
However, the tonnage of ships and the volume of goods in transit are growing
Le Aziende informano
Ufficiali di Macchina: l'Accademia Italiana della Marina Mercantile apre le selezioni per il corso ITS triennale gratuito. Scadenza 26 ottobre
Maritime ETS, FEPORT supports cargo-related anti-avoidance measure
Brussels
It is the most effective solution - claims the federation of European terminal operators - to protect the competitiveness of EU ports
COSCO Shipping, revenues +29% and profits +82%: the credit goes to freight rates, rather than volumes
Hong Kong
The trans-Pacific market is the driving force behind the Chinese group's accounts
Norwegian Cruise Line Holdings reports increased net income but declining margins in the third quarter.
Miami
APM Terminals signs further expansion phase for the Moroccan port of Tangier Med
Rabat
An investment of over 800 million dollars is planned to build 1.2 kilometers of docks
Port of Barcelona launches project to reduce cruise terminals from seven to five
Barcelona
Review of the concession held by Creuers del Port de Barcelona
Boluda and Samskip, a new merger in European short-sea shipping.
Valencia/Rotterdam
The Spanish group has signed an agreement to acquire all the activities of the Dutch group and expand its multimodal platform
Indian shipyards on EU ship recycling list, ECSA asks MEPs to approve
Brussels
Call to reject a motion opposing the Commission's proposal
CVC DIF has acquired a majority stake in the Spanish shipyard Cernaval
Schiphol
The Iberian company employs approximately 275 people
Contship Italia acquires the Tarros group
Melzo/La Spezia
All the activities and assets that make up the integrated service system of the La Spezia group are changing hands
Villa Vie Residences' residential cruise ship suspended
Fort Lauderdale/Sihanoukville
The company attributes the ship's grounding to rising fuel costs and is working on a restructuring and recapitalization plan.
Wallenius Wilhelmsen orders four 9,900 CEU PCTCs plus eight options
Lysaker
Agreement with the Chinese shipyard Jinling Shipyard (Jiangsu)
Royal Caribbean posts record quarterly revenue of $5.59 billion. Full-year 2026 forecasts are raised.
Miami
EBITDA at 2.53 billion and passengers at 2.68 million in the July-September period
Maritime safety, ETS, flags, and employment are the focus of the Confitarma president's report.
Rome
Zanetti calls for a European alliance for freedom of navigation, a national pact for the transition, and less bureaucracy for the Italian flag.
Global Ports Holding signs concession agreement for Saint Vincent cruise port
Istanbul
The agreement has a duration of 30 years
Sunde family sells Color Line to Stena
Gothenburg
Swedish ferry group acquires Norway's largest cruise ferry company
Chinese ports, the race is slowing down
Beijing
After 25 years of growth, freight traffic is almost at a standstill, but containers are still breaking records.
Unions approve joint platform for renewal of the Ports National Collective Bargaining Agreement.
Rome
The centrality of port work was strongly reaffirmed
Conference "Making the Country Fly: Air Cargo, the Engine of Made in Italy"
Rome
Organized by ENAC, it will be held on November 24th in Rome
Hupac has reintroduced the Busto Arsizio/Gallarate - Barcelona shuttle train.
Assago/Chiasso
It is made with three weekly rotations
Saipem wins two new offshore drilling contracts in Egypt and Suriname.
Milan
Orders with a total value of approximately 181 million dollars
UPS signs agreement to acquire Australian Smartways Logistics
Atlanta
The company operates healthcare logistics services in Australia and New Zealand.
20 silos at the port of Catania demolished
Catania
Some fragments of the murals will be transformed into works of art
Containerized cargo throughput at the port of Barcelona increased by 14.3% in October.
Barcelona
Transhipment traffic on the rise
Container traffic at the Port of Long Beach grew by 11.7% last month.
Long Beach/New York
Containers in New York decreased by -1.7% in the third quarter of 2026.
SRI Global acquires The Italian Sea Group for €220 million.
Marina di Carrara
Next Monday the Board of Directors of the nautical company in Marina di Carrara
CEVA Logistics opens a new warehouse in Castel San Giovanni
Milan
50,000 square meters of space dedicated to Daikin's activities
Container traffic in the port of Hong Kong increased by 12.9% in October
Hong Kong
In the first ten months of 2026, 11.15 million TEUs were handled (+3.5%)
Gulftainer and TiL to build container terminal at Indonesian port of Marunda
Sharjah
Agreement with Indonesian PT Karya Citra Nusantara
Rosetti Marino signs new contract for offshore operations in the Mediterranean Sea.
Ravenna
The contract is worth more than 400 million euros
The Ligurian port system with Liguria International at Logitrans in Istanbul
Istanbul
Services and projects highlighted to strengthen logistics connections between Turkey and Southern Europe
Boluda Towage acquires Ecuadorian towing company Cititug.
Valencia
The transaction includes the transfer of ownership of five tugboats
Port of Los Angeles Sets Container Traffic Record for October
Los Angeles
In the first ten months of 2026, 9.11 million TEUs were handled (+5.1%)
In 2027, the port of Ravenna expects 365,000 cruise passengers.
Ravenna
To date, 115 cruise ship calls are scheduled
Giosuè Vezzuto appointed CEO of RINA Services
Genoa
Finnlines' quarterly financial results show strong growth.
Helsinki
Revenues increased by 26.2% in the July-September period. Profit increased by 81.6%.
The Port of Tarragona has won the ESPO Award 2026.
Brussels
The area surrounding the Port Authority headquarters has become a sustainable, resilient and intergenerational space
In the third quarter, cargo traffic in Croatian ports grew by +18.5%
Zagreb
Regular service passengers remained stable, while cruise passengers increased by 6.2%.
Tardino appointed President of the ESPO Committee for the Outermost Regions and Islands
Palermo
In Brussels, a meeting with Raffaele Fitto on the strategic issues of Italian ports.
Denmark's DFDS posts record quarterly revenue
Copenhagen
In the period July-September the group's ships transported 10.1 million linear metres of rolling stock and 2.1 million passengers (-3.6%)
In Montenegrin ports, cargo volumes are decreasing while passengers are increasing.
Podgorica
Traffic with Italy is declining
Ansis Zeltins has been re-elected president of the European Sea Ports Organisation.
Brussels
The Icelandic Ports Association has joined ESPO
This year Blu Navy recorded a growth of +12% in passengers transported
Portoferraio
Transported vehicles also increased (+11%)
A conference on the present and future of Motorways of the Sea in Italy will take place in Ravenna on November 17th.
Ravenna
In 1991 the Ravenna-Catania maritime line began
Uiltrasporti, the Democratic Party's commitment to amendments for port and maritime work is welcomed.
Rome
It is the only political force - the union underlines - that has responded to our requests for a meeting so far.
In the first nine months of 2026, container traffic in the port of Gioia Tauro grew by +1.7%
Rome
The Bank of Italy's economic update on Calabria's economy
FS Engineering and Sogesid have signed an agreement to develop infrastructure projects in Italy and abroad.
Rome
National focus on port infrastructure, logistics systems, and mobility-related infrastructure
The Lazio Regional Administrative Court (TAR) has suspended the increases in maritime training center fees.
Rome
CONFORMAR and ANIFORMAR's request for precautionary measures has been granted. The hearing on the merits is scheduled for March 16.
Global Ship Lease revenues up 4.5% in the third quarter of 2026.
Athens
New $1 billion credit line to finance 15 new container ships
The Papagno Course at Assagenti has trained over a thousand young maritime agents and brokers
Genoa
It has been provided nationally since 2017
AIRIDEA, a new Genoa-Marseille air link with the support of Genova Industrie Navali
Genoa
Service designed to facilitate work-related travel between the two cities
Fincantieri and Republikorp form joint venture to strengthen Indonesia's shipbuilding industry.
Paris
The Propeller Club Port of Sardinia was established today in Cagliari
Genoa
It is the 27th Club of the national association which includes over 1,600 members
India's Adani Ports acquires Dutch terminal operator Evos
Ahmedabad/Amsterdam
Transaction worth 2.56 billion euros
Hapag-Lloyd has completed the acquisition of a 25% stake in APM Terminals Maasvlakte II.
Hamburg
Interferry's board of directors has been renewed.
Victoria
Appointments at the association's 50th anniversary conference in Bangkok
DIS reports earnings growth in the third quarter of 2026
Luxembourg
After the boom in the second quarter, profitability remains at high levels
Arsenio Dominguez will continue to lead the IMO until the end of 2031.
London
The Council has decided. The appointment must be ratified by the assembly.
DHL grows in the third quarter, with Express and Forwarding driving revenue and profits.
Bonn
Revenue of 22.7 billion euros (+12.6%) and EBIT of 1.7 billion (+16.2%)
The EU General Court has annulled the withdrawal of recognition from the Russian naval register
Luxembourg
The investment ban and transaction ban remain in force
Italian bioLNG seeks space among ETS, FuelEU, and national incentives
Rimini
Assogasliquidi calls for simpler certification procedures and measures to make domestic production competitive.
Fincantieri and Leonardo reach agreement to strengthen Orizzonte Sistemi Navali's role.
Trieste/Rome
The companies aim to consolidate the industrial and commercial role of the joint venture
Port of Rijeka: Various cargoes push Luka Rijeka forward, while the Adriatic Gate container terminal loses ground.
Rijeka
In the first nine months of 2026, overall traffic fell by -15% to 3.83 million tonnes
Confetra: The government wants to abolish the tax on small parcels.
Rome
Satisfaction with the government's choices in the budget bill
A Port Renewable Energy Community has been established in Taranto
Taranto
Among the objectives, the development of the Apulian port as an energy hub
Filt and Uilt, the temporary port labor system is not anachronistic
Rome
To define it in this way - the unions denounce - means distorting the nature and role of Article 17 of Law 84/94.
New quarterly record for freight traffic in Albanian ports
Tirana
In the period July-September passengers decreased by -5.4%
SAILING LIST
Visual Sailing List
Departure ports
Arrival ports by:
- alphabetical order
- country
- geographical areas
FedEx's earnings are rising, but net profit falls 68%.
Memphis
The non-cash capital loss related to the spin-off of FedEx Freight weighs heavily
Kalmar recorded a 22% growth in new orders in the third quarter
Helsinki
Turnover stable. Net profit down 14%.
In the third quarter, sales of containers produced by CIMC increased by +30%
Hong Kong
Commercial activity driven by dry boxes (+36%). Reefer units dropped by 28%.
Ports, new investments in Tuscany and Sardinia
Livorno/Cagliari
The 2027 budget estimates for the two Port Authorities have been approved. Highlights include the Piombino dock, works in Livorno, and dredging and electrification projects in Sardinian ports.
Finding qualified personnel in Italian ports is increasingly difficult.
Naples
An analysis by Randstad Research of 13 professional profiles also highlights a marked gender imbalance
COSCO Shipping Ports reports record third-quarter revenue
Hong Kong
In the July-September period, net profit was 102.5 million dollars (+3.4%)
Approval for the 2027 budget forecast and the 2027-2029 POT of the Southern Tyrrhenian and Ionian Sea Port Authority.
Gioia Tauro
The forecast document shows revenues of approximately 24 million euros and expenses of approximately 88 million
Ravenna native Bongiovanni confirmed as president of the Federagenti Youth Committee.
Rome
Renewal of the federation's board of directors
The 2027-2029 Three-Year Operational Plan for the Central Adriatic Port System has been approved.
Ancona
308 million euros of investments are planned, of which 218 million for the Marche region and 91 million for Abruzzo.
The 2027 budget forecast for the Western Liguria Port Authority has been approved.
Genoa
New surcharge on goods postponed to 2028
DP World opens a temperature-controlled warehouse near Bologna
Bologna
Surface area of 22 thousand square meters
Saipem wins two new offshore drilling contracts
Milan
The total value of the orders is approximately 121 million dollars.
Hanwha brings Philadelphia Naval Shipyard under Defense Division control
Arlington
The goal is to integrate the construction of commercial and military ships
The Ports of La Spezia and Carrara approve the 2027-2029 Three-Year Public Works Program and the 2027 Budget.
La Spezia
Pisano: PTLP concrete and consistent with currently available resources
Port concessions: Regional Administrative Court (TAR) blocks 2025 fee increase
Rome
The appeal of Assiterminal and sixteen port companies has been accepted.
Wärtsilä sees quarterly order increases, but not in the Marine segment
Helsinki
In the period July-September the company recorded a net profit of 125 million euros (-31%)
Montaresi appointed general secretary of the Eastern Ligurian Sea Port Authority for another four years.
La Spezia
Renewal of office on the proposal of President Pisano
Double ceremony for two Explora Journeys ships at the Fincantieri shipyard in Genoa
Genoa
Launch of "Explora V" and coin ceremony of "Explora VI"
Italian CMD passes under the control of the UAE group EDGE
Abu Dhabi/Rome
Cousins Mariano and Giorgio Negri retain a significant shareholding
The Northern Tyrrhenian Port Authority presents the new layout of the port of Piombino.
Livorno
Gariglio: A concrete step towards industrial reconversion and the future of Piombino.
FS Logistix has purchased six new CZ LOKO locomotives for freight and shunting services
Rome/Prague
This is the fourth order of this type for the Czech company in ten years.
Port of Bremerhaven: The cruise ship Mein Schiff 3 collided with two container ships.
Bremen
No injuries. The cruise was canceled.
Paolo Moretti has been appointed CEO of RINA Spa.
Genoa
Giosuè Vezzuto has assumed the role of CEO of RINA Services
HD Hyundai and Kiewit to establish joint venture at new shipyard in the US
Houston/Seoul
The construction of both military and commercial vessels is planned
Konecranes' quarterly port equipment orders decline as revenue increases
Helsinki
Kuehne+Nagel's third quarter was very positive
Schindellegi
Growth in economic and operating results in all business segments
Wildcat's race for US defense: exclusive agreement with historic Fraser shipyard
Superior
The Miami Beach fund's operation is part of the government's plan to relaunch the American shipbuilding industry.
Port of Ancona: First single ZES authorization issued
Ancona
A three million euro investment in yacht construction has been unblocked.
PORTS
Italian Ports:
Ancona Genoa Ravenna
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Leghorn Taranto
Cagliari Naples Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venice
Italian Interports: list World Ports: map
DATABASE
ShipownersShipbuilding and Shiprepairing Yards
ForwardersShip Suppliers
Shipping AgentsTruckers
MEETINGS
Conference "Making the Country Fly: Air Cargo, the Engine of Made in Italy"
Rome
Organized by ENAC, it will be held on November 24th in Rome
A conference on the present and future of Motorways of the Sea in Italy will take place in Ravenna on November 17th.
Ravenna
In 1991 the Ravenna-Catania maritime line began
››› Meetings File
PRESS REVIEW
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Press Review File
FORUM of Shipping
and Logistics
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› File
Access to the port of Ravenna is authorized for vessels with a maximum draft of 11.00 meters.
Ravenna
Benevolent: it is a fundamental step for the economic and strategic development of the airport
Port of Genoa extends food inspection authorization to PSA SECH terminal
Genoa
The provision of the Ministry of Health expands the categories of products that can be subjected to control
On Thursday, the Unione Interporti Riuniti will present the ELODIE project at the Chamber of Deputies.
Rome
The aim is to create a digital federation of interports
ABB reports record orders of $12 billion in the third quarter.
Zurich
Revenues and profits also increased, while the group announced a joint venture with Mitsubishi Electric
In the third quarter of 2026, containers in the port of Barcelona decreased by -9.2%
Barcelona
The decline was driven by a 19.9% reduction in transhipment traffic.
COSCO Shipping Ports terminals set new quarterly container throughput record
Hong Kong
In the period July-September also volumes handled by CMPort
In August, the ports of Western Liguria handled 5.2 million tons of goods (+1.6)
Genoa
In Genoa, an increase of +6.1% was recorded, while Savona-Vado Ligure suffered a decrease of -10.0%.
Raben Italy opens a new warehouse in Pomezia
Milan
The goal is to consolidate the positioning and territorial expansion in road transport
- Via Raffaele Paolucci 17r/19r - 16129 Genoa - ITALY
phone: +39.010.2462122, fax: +39.010.2516768, e-mail
VAT number: 03532950106
Press Reg.: nr 33/96 Genoa Court
Editor in chief: Bruno Bellio
No part may be reproduced without the express permission of the publisher
Search on inforMARE Presentation
Feed RSS Advertising spaces

inforMARE in Pdf
Mobile