testata inforMARE Home Page
Cerca
21 November 2026 - Year XXX
Independent journal on economy and transport policy
04:48 GMT+1
LinkedInXFacebook
FORUM of Shipping
and Logistics


The Liquefied Petroleum Gas shipping market
in 2003

A disappointing market overall despite some promising signs


Significant events 
Situation by ship size: 
   - VLGC
   - LGC
   - Mid-size
    - 8 000/22 000 cbm
    - 8 000 cbm and less
Perceptions
The second-hand market


Significant events

At the start of 2003 conditions in the LPG shipping market were still full of uncertainty and showed little prospect of improving in the months to come. This view however was quickly dispelled soon after the beginning of the year. The market caught a breeze and started moving within all sectors, irrespective of ship's sizes, while the price of LPG and derivatives was also on the rise. We seemed at last to be leaving the bad times and the year showed signs of a promising and happier climate'

Unfortunately, this wind of hope began to lose strength at soon as February and March saw the disturbing news of the Iraqi invasion. We were back to uncertainty, punctuated by short but strong variations up until the beginning of the summer, before the market was able to settle down and reach a cruising speed at first restrained then slightly more robust at the end of the year.

Certainly the high degree of volatility which came in short spells opened up arbitrage possibilities and inter-continental product movements, but overall within the different categories of ship sizes the year was disappointing and did not afford the recovery which was eagerly awaited by the various market players, of which 'some' owners are confined to LPG carriers (excepting LNG which has different criteria).

By 'some' we are referring to those specifically involved only in LPG trade and who have and continue to operate their fleet with rock-bottom returns now for a number of years. Others owners who are active in different sectors such as oil or dry bulk have at least had better luck, provided they did not cover all their positions under long term charters: here 2003 seems to have been a bonanza year.

One of the most striking events in the shipping market during the year 2003 is perhaps the clean break between the evolution of the different markets, with the scintillating performance of the oil and dry bulk sectors compared to the continuing lacklustre situation in the petrochemical and more particularly the LPG markets.

These few figures well illustrate the picture:
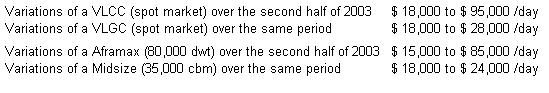

 
 A monthly variation of $ 20,000 to $ 50,000 with a LPG gas carrier on time charter or equivalent time charter, often leads to a feeling of uncertainty and concern from both sides (long term co-operation, uncertainty as regards losing their position and market share, etc.) whilst in the oil and bulk sector the same variations in amounts are realised but on daily rates! Business as usual!

The unstoppable surge forward in China and the skyrocketing of raw material imports has been a primary reason for the strong rise in rates. But other reasons which are more fundamental can be given to explain the gap that divides movements within the various sectors, some of which are:

  • LPG markets and movements are much more restricted and specialised thus less fluid and volatile than the other sectors of shipping,

  • a greater sensitivity and reaction to the variations in product prices,

  • increased production in closer proximity to consuming areas, such as the proliferation of petrochemical crackers in the Far East and S.E. Asia, etc.

Some other trends can be detected over the last twelve months:

  • Tonnage: a reduction in the number of ships going for scrap, which is the logical consequence of the strong increase in numbers last year when 26 units were demolished. By the end of November 2003 we have registered 18 units with a capacity of near half a million cbm, of which one 29,000 cbm built in 1968 was resold by the demolition yard to an operator in the Middle East, and the recent sale of a 25 years old 75,500 cbm! The strong rise in the scrap price, which went from $ 150/ldt in November 2002 to more than $ 250/ldt in November 2003, is obviously a consideration when contemplating whether to scrap! At the same time 29 newbuildings with a total capacity of 1,076 million cbm came into service during the year.

  • Mergers, de-mergers, and take-overs: on April 7th 2003, Oslo and the shipping world learnt that Bergesen DY was being taken over by World Nordic an affiliate of World-Wide Shipping, which is controlled by the Sohmen family and already strongly present in oil tankers. The same month the team of Stargas and Montanari in the 'Medgas Pool' broke up and the pool was restructured without Stargas who were facing financial difficulties. September saw the launching of MNGC (Maersk Norgas Gas Carriers), a new joint-venture between Norgas (IM Skaugen) and Maersk for the commercial management of their ships with a capacity between 5,000 and 12,000 cbm (37 units). This fleet is due to be operated in conjunction with the biggest ships between 15,000 and 20,000 cbm run by Scandigas / AP Moller. Also to be noted was the withdrawal by Tsakos from the joint venture set up in 2002 with Lauritzen Kosan on four 4,400 / 6,300 cbm, all now run by the latter.

  • Prices: the continuation of the upward movement in oil prices and derivatives followed an erratic but continuous trend. Although with less of an impact than China on the oil and bulk sectors, the US also exerted a significant pressure on the LPG and ammonia markets, with the strong surge in imports resulting from the hike in the price of natural gas. This price is now close to $ 7/mmbtu, a level which highly affects the price of propane and ammonia which are extracted from natural gas.

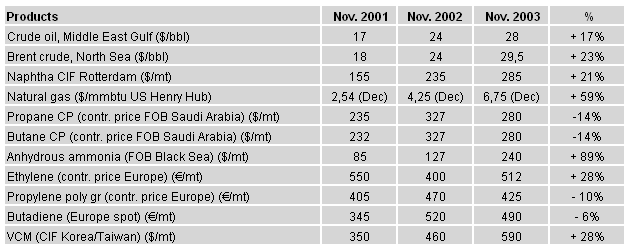
Our annual table with the evolution of prices over the last three years gives the following:


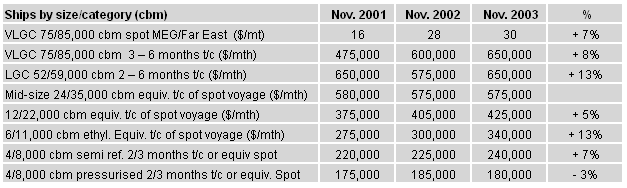
Together with the gas price, the freight market was rather disappointing throughout the year 2003, despite the progress seen in the larger size sectors of VLGC (78 / 84,000 cbm), LGC (52 / 59,000 cbm) and Mid-size (24 / 35,000 cbm) during the second half.

Some figures which illustrate this point:


It is always important to remember that the average rates exclude all eventual idle time of a ship due to inactive periods between voyages and are neither an indication of an owner's gross margin on the spot market nor representative of the level of transactions over period business (two years and more).


Situation by ship size

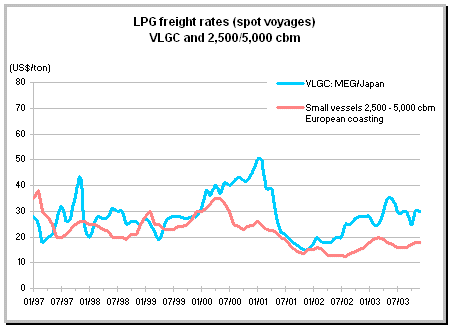
The average spot rates on the reference voyage Middle East Gulf / Japan for the year was higher than the previous year, despite some much more pronounced variations both higher and lower. Starting from a level of close to $ 30 per ton at the beginning of the year, the market then fluctuated between $ 23-30 per ton before reaching a peak of $ 40 in June.

These rates represent a time charter equivalent fluctuating between $ 550,000 and $ 900,000 per month, and an annual average of nearly $ 600,000 per month, from which figure a number of short and long term time charters were concluded at slightly higher levels.

Naphtha demand again largely contributed to keeping the VLGCs fully employed and nearly a third of the Bergesen fleet is employed on the naphtha market (7 to 10 VLGCs) with an average revenue which is very close to the LPG rates depending on the spot fluctuations of the naphtha market.

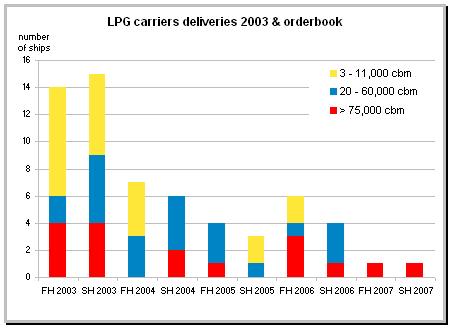
The price of scrapping, which was higher and well sustained at $ 250 per ton, attracted four VLGCs, including one 75,000 cbm of 26 years-old which is an unusual occurrence in this respect, whereas eight newbuildings were delivered in 2003. By end November 10 VLGC newbuildings were on order for which deliveries spread out between 2004 and 2007.

Some studies and statistics indicate that there will be an important deficit of VLGCs in the next years given the age profile of this sector and the foreseen growth in LPG production. If current growth were in fact to follow these estimates it is likely that a shortage could occur as from 2005 / 2006, but one must be careful of a possible reversal in the situation should the pace of new orders become too intense.

Despite the current buoyant climate and the important number of multiple orders placed with the main shipyards, some of them are still able to offer newbuildings of VLGCs before 2006!
 

This segment is going through a transitional phase due to the first deliveries of the new orders placed two years ago, but currently still strongly influenced by the age profile of the fleet. Of the 24 units which comprise this category and currently in service, eight are over 25 years-old and sixteen more than 20 years-old, whilst 7 new units are due to be delivered over the next two years.

Such a marked division in ages and ships' specifications has resulted in a freight differential being paid by the market to ships of the older generation, primarily engaged in the ammonia trade where the terminals are able to avoid the restrictions imposed by the oil Majors, compared to higher rates obtained by more modern ships.

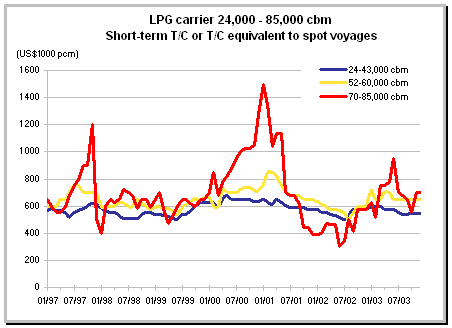
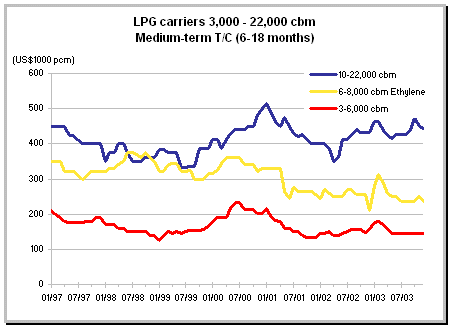
Despite the very small change in demand compared to the previous year and an idle period which is still considerable, the average level of short term time-charter rates (6 to 18 months) rose very slightly, moving up from a monthly rate of $ 500,000 to $ 550,000 at the beginning of the year to $ 600,000 to $ 625,000 in the last quarter of 2003 for the older units, whereas the more modern vessels were able to achieve $ 700,000 to $ 750,000 per month.

Some Majors have become owners in this segment size such as Sonatrach with three carriers to be delivered 2004 / 2005 and Hydro for two 60 000 cbm due 2005 / 2006, but the category remains relatively fragile and has to depend on the scrapping of the oldest units, which in all likelihood should occur imminently.
 

This category of vessel stands out from the other sectors by producing the best results and by their more consistent and regular performance, thanks to a demand which is shared between ammonia for a large part and LPG to a lesser extent.

As is the case for the VLGCs and the LGCs which have been reviewed above and which is dominated by one operator Bergesen, in the Midsize sector Exmar has the majority control.

Although still affected by an important idle time (11% in 2003, slightly below last year's level), the average revenues have increased over the year thanks to a more sustained demand for longer voyage movements (trans-Atlantic towards the US, cross Europe and East Med towards India for ammonia).

The flexibility in the size of these ships allows them to play between the two main markets of LPG and ammoniac, despite the additional costs of changing grades. The monthly level of 12 to 18 months time-charters for a 35,000 cbm vessel in January was roughly $ 585,000, whereas the current rate is $ 650,000 per month, and spot demand remains firm. That of a 24,000 cbm refrigerated was around $ 550,000 during the last quarter 2003.

As we somewhat suspected last year, this sector has seen an important rush of new orders: five 39,000 cbm shared between Bergesen, APMoller, and Exmar for delivery between 2005 and 2006, and one 39 000 cbm for Bibby, still associated with Exmar in the Midsize pool and which should be delivered early 2005. Still under construction for delivery during 2004, is the 35,000 cbm for Mitsubishi and two Qatari 23,000 cbm.

The current market is not really conducive to new orders, but the various players, already heavily involved in the quality regulations required by the LPG industry and probably also in ammonia in the near future, are doing their best to maintain their positions within their size categories and to respond to the quality improvements being exacted by the majority of oil Majors.


The recovery in petrochemicals has not allowed this sector to take off. What is even worse is that the results of the chemical industry overall are fairly negative with everyone looking to improve productivity. This shipping category is also affected by the weakness of this industry and has had to fall back and seek out business in other markets such as LPG and ammonia.

The results of the first three quarters were extremely disappointing without any real improvement over the previous year, situated within a bracket of $ 275,000 to $ 325,000 for the smaller sizes and $ 375,000 to $ 475,000 for the larger ones.

Only as from October there was a growth in demand, often supported by an increase in the volume of LPG and ammonia movements (inter North Europe, Middle East Gulf / Asia, trans-Atlantic) indirectly influenced by imports into the US and a sporadic demand from the Asian zone for chemical gas. This area in turn was highly affected by inter Asian movements to the detriment of inter-continental traffic.

A very wide East/West geographical dispersal of ships and an increase in the volume of COAs suddenly generated a rise in demand and consequently freight rates, both on the spot as well as the short and medium term time-charter contracts, with the level of $ 575,000 being broken for the 20,000 cbm sector during the last quarter.

This sector was marked by the concentration move between the fleet of the Scandigas pool operated by AP Moller and that of Norgas, which became official with the creation of the new pool 'MNGC' as previously stated.

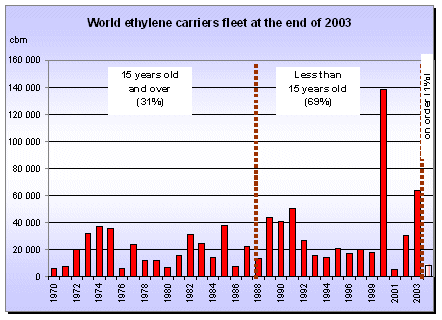
No new order for refrigerated vessels in this size category has been announced up till now, whereas in 2003 there was the delivery of three 8,500 cbm and two 10,200 cbm ethylene carriers for Norgas by the Chinese shipbuilders Zhonghua, as well as two 9,000 cbm ethylene carriers for Italian account and two 11,000 cbm pressurised taken on long term time-charter by Vitol. Still to be delivered is the 'Gaschem Baltic', 8 600 cbm ethylene carrier, for Gaschem.

And China? Are we going to witness the after-affects of the explosion in consumption already under way in this country, brought about by the 150 million Chinese who are already catching up with same level of consumption as among the western world? Without counting the numerous other millions that will follow in the coming years.

The phenomenal rise in strength of this part of the world should have repercussions on LPG demand and derivatives in the East of Suez, even taking into account the volumes and foreseen expansions on the various production sites being established in Asia these past few years.


Another very disappointing year for owners, more numerous in this sector. The efforts to concentrate operations which were made two years ago (breaking up of the Tarquin fleet, and the merger between Exmar and Lauritzen on the smaller pressurised vessels), has not produced any significant increases and levels have remained 'under pressure' during a large part of the year to average out on a monthly time-charter rate between $ 130,000 for the small 3,200 cbm and $ 275,000 for the larger size of 6,000 to 8,000 cbm, and a little bit more for the 8,000 cbm ethylene carriers. 

The petrochemical sector has nonetheless prevented a worsening of idle time and of rates obtained on the LPG market, with the development of some long haul movements from Europe to the US or S.E. Asia for propylene and ethylene. 

This sector has always suffered from an excess capacity of tonnage, but this should begin to rectify itself given the lack of orders for any newbuildings. A situation which is totally logical given the very low return on investment which owners are experiencing in this category. 

Most of the shipyards are in fact fully booked up until the end of 2006 and the other shipping sectors (oil, bulk, and LNG) should continue to keep them busy with new orders. 

This new situation risks to upset the balance between the supply and demand of ships of the refrigerated and semi-pressurised class, at a time when the need for new orders can no longer been satisfied with deliveries in one year and despite the existence of the smaller Japanese shipyards, which have always been specialised in this sector at competitive prices. 

The orderbook is limited to two 3,000 cbm semi-pressurised / refrigerated for Italian account for delivery at the beginning of 2004, two 4,000 cbm also semi-pressurised / refrigerated for Geogas with Japanese shipyards for delivery in 2005, and three other 7,200 cbm pressurised of which two are for Brazil and the other Japan with during delivery in 2004.


Prospects

As we have seen, the biggest carriers (VLGC down to Midsize) have survived during the course of the year slightly better with marginally higher results as compared to last year, but the other sectors have suffered again with still too long idle times and a decline in demand on certain trades.

In short, another unsatisfactory year for LPG and its derivatives in a feverish condition compared to the healthy excitements seen in the other markets, and in an economic environment which has been badly shaken by the drop in the dollar against the euro.

Nonetheless there are a few indications that could lead to an improvement in the situation:

The order book for newbuildings, especially of ships less than 30,000 cbm, has never been so slim and close to the critical level needed to replace the oldest ships. These latter are being more and more scrutinised by the new safety regulations of the oil Majors, as well as the new political measures being adopted by some countries with regards to the safety and age of ships. The vessels are classified as 'LPG tankers' and improperly being subjected to the same conditions as oil tankers. An immediate consequence of this development is that a ship's depreciation should be calculated on the basis of a shorter life-span. It is not unreasonable to think that the combined effect of a growing number of candidates for scrapping together with a reduced number of new orders will lead to a mini-shortage of tonnage by 2006.

At the same time we have recently seen that some owners who are already involved in other shipping sectors, are beginning to show a disinterest in gas carriers, especially within the smaller sizes. Given the poor returns on investment that they have been experiencing for a long time, some owners are now beginning to question any new investments in gas and preferring to look at other shipping sectors. We have here the possibility of a change in the market structure, together with a likely problem of renewing the fleet in a couple of years, which is perhaps more serious than the often quoted risk of the saturation of shipyards due to an overflow of orders.

The strong surge in American imports linked to the price of natural gas should continue, as long as the different LNG projects do not become operational. The energy 'bonanza' on the Asian continent, lead by China, is in full force and new requirements for gas and petrochemicals are to be expected. India, Japan, and China are all likely to see an increase in the import and export of products with other geographical zones.

The most serious forecasts sometimes miss their target due to some small unexpected elements, which nobody had foreseen but which changes the outlook (disease, terrorism, etc.). We only hope however that some of these new trends can develop in a calm and orderly mood so as to allow the market to steer and set sail towards a brighter horizon.


LPG carriers second-hand market

  • Carriers over 50,000 cbm

Nine sales were reported this year, of which four for scrapping at a rate between $ 200 and $ 260 per lightweight ton (which represents about $4 to 5 million per ship).

Four other sales concerned ships between 20 and 25 years old and were finalised at prices from $ 3.0 up to $ 8.5 million for the most recent (built in 1982).

Two modern candidates for sale came onto the market at the beginning and at the end of the year, but obtained similar prices. At the start to the year Naftomar bought the 'Gas Roman', 78,000 cbm, built in 1990 for around $ 32 million. Later in the year Bergesen purchased the 'Flanders Gloria', built in 1991, for $ 33 million. For reference the latter had been acquired by Exmar five years ago for $50 million.

  • Carriers between 20,000 - 50,000 cbm

No transaction for further trading has been reported this year. The episode of the 'Navigator' has still not come to an end and the story is still an open book.

  • Carriers between 10,000 - 20,000 cbm

 Three sales for scrapping have been concluded this year. As to sales for further trading, the London owner Zodiac has continued to strengthen his position in this category with the purchase of the 'Nelly Maersk', 14,700 cbm, built in 1990, for about $ 15.5 million in June. This vessel will join the five other ships of similar size acquired in 2001 and which remain employed in the 'Maersk NGC' pool.

  • Carriers between 3,000 and 10,000 cbm

Small pressurised ships remained at the low levels of last year. Most of the sales have been made between Far Eastern buyers and sellers, with the notable exception of 'Chemgas Mango' and 'Chemgas Durian', 3,200 cbm, built in 1997, and which were bought for $ 5.2 million each by Dorian Hellas, who continues to built up its position in the small size LPG market, after having purchased last year two ships of similar type and same age at comparable terms.

As to the semi-refrigerated market, only the oldest and cheapest ships were able to find a buyer other than for scrap. We can cite the 'Galp Faro', 5,000 cbm, built in 1982, and sold for $ 2.5 million.


Shipping and Shipbuilding Markets in 2003

I N D E X

›››File
FROM THE HOME PAGE
First meeting of the Administrative Board of the European Union Customs Authority
Lilac
Polish Malgorzata Krok was elected President
Fincantieri to build two new dual-fuel cruise ships for Carnival Cruise Line
Trieste
They will have a gross tonnage of approximately 130,000 tons
Brexit and ro-ro: after the decline in traffic, British shipping is focusing on the summit with Brussels
London
Fewer trade barriers and more certainty for ferries and short-sea shipping, with the ETS at the heart of the demands
PSA Singapore has started work on the second phase of the Tuas Port development.
Singapore
21 docks will be built with a depth of -23 metres and 8.6 kilometres of berths
Decline in cargo traffic volume in the port of Koper
Koper/Ljubljana
In the July-September quarter the decline was -6.0% (-15.2% according to the Statistics Office)
The first European strategic storage hub is centered around Porto Marghera
Rome/Venice
Urso: important recognition for Italy. Gasparato: areas, infrastructure, professional and industrial skills already exist here.
2027 French Presidential Election: Shipowners Ask Candidates to "Choose the Sea"
Paris
Armateurs de France presents seven proposals to bring France into the top 5 of European shipowning nations by 2040
ZIM's third quarter is a highlight. But the merger with Hapag-Lloyd remains on hold.
Haifa
Revenues at 2.71 billion (+53%) thanks above all to transpacific freight
Switzerland: Government proposes extending support for rail freight traffic through the Alps until 2035
Bern
A total of 486 million francs has been allocated for unaccompanied combined transport.
Shipowners unite at the IMO: "Global greenhouse gas regulations are needed to provide certainty for investments."
London/Washington
Nine associations representing the world's commercial fleet are calling on governments to agree at MEPC 85 in London.
Nova Marine Carriers acquires 25% of Terminal Nord Spa
Ravenna
The Sapir Group's Ravenna port terminal specializes in the handling of aggregates
Dry rivers and a larger fleet: Viking cruise group's third quarter amid growth and rising costs
Los Angeles
The water crisis in Europe reduces revenues and adjusted gross margin by approximately €100 million, while fleet expansion increases vessel operating expenses by +17.6%.
Malta Maritime Forum: The current EU maritime ETS is flawed and damaging.
Floriana/Brussels
A proposed fix: apply the ETS to cargo, whether containerized or not, rather than to the vessel carrying it. The MBB proposes exemptions for island connections.
Greek shipowners slam Brussels: EU inflexibility jeopardizes IMO negotiations on shipping decarbonization
Piraeus
On the eve of the London meetings, the UGS denounces the stalemate and calls for flexibility
EU ETS, ESPO, FEPORT, WSC and Assarmatori call for strengthening incentives for transhipment
Beyond Automation: The Port Work That Remains
Rio de Janeiro
In Rio, the IDC discusses 2030, and a Brazilian study asks how much, in a healthy way, port work costs today.
Port of Civitavecchia: Cruise passenger numbers up 10.8% in the third quarter; cargo holdups and ro-ro traffic decline.
Civitavecchia
In the third quarter, revenues of French company CMA CGM grew by +31.1%
Marseille
Net profit tripled. The fleet transported a record number of containers.
Ports of Naples and Salerno saw container throughput growth in the second quarter.
Naples
283,000 TEUs were handled (+7.8%). Total freight increased by 4.7%. Ro-ro traffic slowed and cruise traffic declined.
Evergreen and WHL post strong quarterly earnings growth
Taipei
The two Taiwanese companies have ordered 83,300 and 110,050 new containers respectively.
Terminal Operators Face Off: HHLA Slows in Third Quarter, ICTSI Accelerates
Hamburg/Manila
The German company saw an 8.5% drop in container traffic. ICTSI reported an 8.1% increase (-1.8% on a like-for-like basis).
Port of Hamburg: Container throughput stable in third quarter
Hamburg
Bulk cargo decline. In the first nine months of 2026, traffic amounted to 84.5 million tons (-2.6%).
Fincantieri's orders totaled €3.57 billion in the third quarter, up 180%.
Trieste
Revenues down 6% to €2.02 billion, but EBITDA rises 7% to €161 million.
Hapag-Lloyd reports quarterly revenue growth of 27.9% with container volumes virtually unchanged.
Hamburg
Average freight rate rises by 27.9% and supports the results of the German company, which further improves its annual estimates
HMM records a very positive third quarter in both the container and bulk segments
Seoul
During the period the fleet transported 1.1 million containers (+8.4%)
The reform that was supposed to reduce the fragmentation of ports
Taranto
From the transition from 24 Port Authorities to 15 AdSPs to the entry of Gallipoli into the Taranto system: Italy continues to add ports
The port of Genoa closed the third quarter with growth, while freight traffic remained stable in Savona-Vado.
Genoa
Port of Ravenna, September slows down
Ravenna
In the first nine months of 2026, freight traffic remained above last year's levels
Bosphorus Strait: Ship transits plummet by 23.2%.
Ankara
Bulk carrier passages halved in the third quarter. The decline in the Dardanelles was more moderate (-12.8%), while container ships held steady.
In the third quarter, Eurokai terminals handled a record traffic of 3.9 million containers (+9.4%)
Hamburg
In the first nine months of 2026 the total was over 11.3 million TEUs (+8.7%)
Maritime ETS: Brussels says the system is working. Ports fear traffic flight.
Brussels
The Commission's latest report for 2025 reports a 4% drop in emissions and compliance above 99%. However, it provides no new data on the risk of tax evasion.
Yang Ming's revenues grew by 52.4% in the third quarter
Keelung
A continuation of favorable conditions for shipping is expected in the latter part of 2026
US-China trade easing also involves ports and shipyards
Beijing
Beijing extends suspension of port charges on US vessels and investigation into the impact of the US measures on its maritime industry
Alfa Laval Acquires Navtor for $700 Million
Lund/Egersund
The Norwegian company providing digital solutions for shipping will be integrated into the Ocean division of the Swedish group
Boluda Towage acquires Dutch towing company Muller Dordrecht
Dordrecht/Valencia
It has a fleet of 16 tugboats and eight barges
Last month, vessel transits through the Suez Canal increased by +32.1%
Cairo
Growth of +86.8% in tonnage and +94.1% in transit rights
Rail, space, and the environment are among the priorities emerging from meetings on the new Port Planning Scheme for the ports of Genoa and Savona-Vado.
Genoa
The first phase of the AdSP's listening process has concluded with 65 hearings and over 120 stakeholders involved.
Fincantieri signs agreements with JA Solutions, Navantia, and Naval Group
Paris
Intensive collaboration with the Danish company in the field of advanced modular and containerized systems for reconfigurable naval units
Fewer containers, more revenue: Maersk's maritime division grows with freight rates
Copenhagen
In the third quarter, volumes fell by -0.8%, but tariffs and congestion raised Ocean's EBIT to 2.6 billion
From Egypt to Morocco, passing through Gioia Tauro: does the ETS shift containers to non-EU ports?
Brussels
A study promoted by Assarmatori sees signs of transfer already underway and calls for corrections
ONE vessels carried record container volumes in the third quarter
Singapore
Revenues increased by 36.5%. Performance driven by demand for transpacific shipments.
Wallenius Wilhelmsen records a third quarter with record revenues which, however, grow less than costs
Lysaker
Slight decrease in the volumes of vehicles transported by the fleet
Suez Canal: Signs of a recovery in ship traffic in September
Ismailia
However, the repercussions of the crisis in the Red Sea persist
Taranto, the steel crisis continues to weigh on the port.
Taranto
Liquid bulk cargoes are supporting volumes, but overall traffic is down 5.7% in the first nine months of 2026. Container traffic remains volatile.
US port tariffs on Chinese ships, trade coalition calls for permanent suspension
Washington
Hundreds of associations have written to Greer ahead of the January 9, 2027, deadline. Among them is the World Shipping Council.
T&E: The ETS should become the driving force behind investments in e-fuels for aircraft and ships.
Brussels
The organization's demands for the overhaul of the ETS: more European resources, a dedicated fund, and two-sided auctions
In the first half of 2026, freight traffic in the port of Livorno fell by -3.6%
Livorno
Ports on Elba also experienced a decline (-3.3%). The port of Piombino bucked the trend with a +5.7%.
Cargo volumes down in Southern Adriatic ports in the first six months of 2026
Bari
The system loses 676 thousand tons compared to 2025, almost all between the two largest ports
In the third quarter, ship traffic in the Panama Canal remained stable
Panama/Balboa
However, the tonnage of ships and the volume of goods in transit are growing
Maritime ETS, FEPORT supports cargo-related anti-avoidance measure
Brussels
It is the most effective solution - claims the federation of European terminal operators - to protect the competitiveness of EU ports
COSCO Shipping, revenues +29% and profits +82%: the credit goes to freight rates, rather than volumes
Hong Kong
The trans-Pacific market is the driving force behind the Chinese group's accounts
Norwegian Cruise Line Holdings reports increased net income but declining margins in the third quarter.
Miami
APM Terminals signs further expansion phase for the Moroccan port of Tangier Med
Rabat
An investment of over 800 million dollars is planned to build 1.2 kilometers of docks
Port of Barcelona launches project to reduce cruise terminals from seven to five
Barcelona
Review of the concession held by Creuers del Port de Barcelona
Boluda and Samskip, a new merger in European short-sea shipping.
Valencia/Rotterdam
The Spanish group has signed an agreement to acquire all the activities of the Dutch group and expand its multimodal platform
Indian shipyards on EU ship recycling list, ECSA asks MEPs to approve
Brussels
Call to reject a motion opposing the Commission's proposal
CVC DIF has acquired a majority stake in the Spanish shipyard Cernaval
Schiphol
The Iberian company employs approximately 275 people
Contship Italia acquires the Tarros group
Melzo/La Spezia
All the activities and assets that make up the integrated service system of the La Spezia group are changing hands
Villa Vie Residences' residential cruise ship suspended
Fort Lauderdale/Sihanoukville
The company attributes the ship's grounding to rising fuel costs and is working on a restructuring and recapitalization plan.
Wallenius Wilhelmsen orders four 9,900 CEU PCTCs plus eight options
Lysaker
Agreement with the Chinese shipyard Jinling Shipyard (Jiangsu)
Spaniard Duch is the new president of the Conference of Peripheral Maritime Regions
Brussels
Spaniard Duch is the new president of the Conference of Peripheral Maritime Regions
Valencia reduces transhipment burden, Algeciras remains a transhipment hub
Valencia/Algeciras
In October, container traffic at the Valencian port increased by +1.2%, while in the Andalusian port it decreased by -0.4%.
Porto Marghera: Work begins on laying the spans of the new railway bridge.
Venice
Infrastructure designed to make rail connections more efficient
Spanish ports will ban the discharge of ship scrubber wash water into the sea from July 1st.
Madrid
Prohibition valid for all types of civilian vessels, regardless of their flag
The Argentine Navy intends to acquire up to three corvettes developed by Fincantieri
Trieste
Letter of intent between the two defense ministers
Assagenti holds a single-issue meeting on the new seawall at the port of Genoa.
Genoa
It will be held on November 30th at the Italian Merchant Marine Academy Foundation
This year, Corsica Ferries ferries have handled record traffic in Vado Ligure.
Vado Ligure
Passengers exceeded 400,000, with a 14% increase over 2025
VM Holz and MSC abandon project to build intermodal terminal in Upper Austria
Vöcklamarkt
An investment of approximately 170 million euros was planned
GLS and Geopost to form joint venture for parcel shipping in Germany
Amsterdam/London
The new company is expected to have an annual turnover of over four billion euros.
Unions approve joint platform for renewal of the Ports National Collective Bargaining Agreement.
Rome
The centrality of port work was strongly reaffirmed
Conference "Making the Country Fly: Air Cargo, the Engine of Made in Italy"
Rome
Organized by ENAC, it will be held on November 24th in Rome
Saipem wins two new offshore drilling contracts in Egypt and Suriname.
Milan
Orders with a total value of approximately 181 million dollars
Hupac has reintroduced the Busto Arsizio/Gallarate - Barcelona shuttle train.
Assago/Chiasso
It is made with three weekly rotations
UPS signs agreement to acquire Australian Smartways Logistics
Atlanta
The company operates healthcare logistics services in Australia and New Zealand.
20 silos at the port of Catania demolished
Catania
Some fragments of the murals will be transformed into works of art
Containerized cargo throughput at the port of Barcelona increased by 14.3% in October.
Barcelona
Transhipment traffic on the rise
Container traffic at the Port of Long Beach grew by 11.7% last month.
Long Beach/New York
Containers in New York decreased by -1.7% in the third quarter of 2026.
SRI Global acquires The Italian Sea Group for €220 million.
Marina di Carrara
Next Monday the Board of Directors of the nautical company in Marina di Carrara
CEVA Logistics opens a new warehouse in Castel San Giovanni
Milan
50,000 square meters of space dedicated to Daikin's activities
Container traffic in the port of Hong Kong increased by 12.9% in October
Hong Kong
In the first ten months of 2026, 11.15 million TEUs were handled (+3.5%)
Gulftainer and TiL to build container terminal at Indonesian port of Marunda
Sharjah
Agreement with Indonesian PT Karya Citra Nusantara
Rosetti Marino signs new contract for offshore operations in the Mediterranean Sea.
Ravenna
The contract is worth more than 400 million euros
The Ligurian port system with Liguria International at Logitrans in Istanbul
Istanbul
Services and projects highlighted to strengthen logistics connections between Turkey and Southern Europe
SAILING LIST
Visual Sailing List
Departure ports
Arrival ports by:
- alphabetical order
- country
- geographical areas
Boluda Towage acquires Ecuadorian towing company Cititug.
Valencia
The transaction includes the transfer of ownership of five tugboats
Port of Los Angeles Sets Container Traffic Record for October
Los Angeles
In the first ten months of 2026, 9.11 million TEUs were handled (+5.1%)
In 2027, the port of Ravenna expects 365,000 cruise passengers.
Ravenna
To date, 115 cruise ship calls are scheduled
Giosuè Vezzuto appointed CEO of RINA Services
Genoa
Finnlines' quarterly financial results show strong growth.
Helsinki
Revenues increased by 26.2% in the July-September period. Profit increased by 81.6%.
The Port of Tarragona has won the ESPO Award 2026.
Brussels
The area surrounding the Port Authority headquarters has become a sustainable, resilient and intergenerational space
In the third quarter, cargo traffic in Croatian ports grew by +18.5%
Zagreb
Regular service passengers remained stable, while cruise passengers increased by 6.2%.
Tardino appointed President of the ESPO Committee for the Outermost Regions and Islands
Palermo
In Brussels, a meeting with Raffaele Fitto on the strategic issues of Italian ports.
Denmark's DFDS posts record quarterly revenue
Copenhagen
In the period July-September the group's ships transported 10.1 million linear metres of rolling stock and 2.1 million passengers (-3.6%)
In Montenegrin ports, cargo volumes are decreasing while passengers are increasing.
Podgorica
Traffic with Italy is declining
Ansis Zeltins has been re-elected president of the European Sea Ports Organisation.
Brussels
The Icelandic Ports Association has joined ESPO
This year Blu Navy recorded a growth of +12% in passengers transported
Portoferraio
Transported vehicles also increased (+11%)
A conference on the present and future of Motorways of the Sea in Italy will take place in Ravenna on November 17th.
Ravenna
In 1991 the Ravenna-Catania maritime line began
Uiltrasporti, the Democratic Party's commitment to amendments for port and maritime work is welcomed.
Rome
It is the only political force - the union underlines - that has responded to our requests for a meeting so far.
In the first nine months of 2026, container traffic in the port of Gioia Tauro grew by +1.7%
Rome
The Bank of Italy's economic update on Calabria's economy
FS Engineering and Sogesid have signed an agreement to develop infrastructure projects in Italy and abroad.
Rome
National focus on port infrastructure, logistics systems, and mobility-related infrastructure
The Lazio Regional Administrative Court (TAR) has suspended the increases in maritime training center fees.
Rome
CONFORMAR and ANIFORMAR's request for precautionary measures has been granted. The hearing on the merits is scheduled for March 16.
Global Ship Lease revenues up 4.5% in the third quarter of 2026.
Athens
New $1 billion credit line to finance 15 new container ships
The Papagno Course at Assagenti has trained over a thousand young maritime agents and brokers
Genoa
It has been provided nationally since 2017
AIRIDEA, a new Genoa-Marseille air link with the support of Genova Industrie Navali
Genoa
Service designed to facilitate work-related travel between the two cities
Fincantieri and Republikorp form joint venture to strengthen Indonesia's shipbuilding industry.
Paris
The Propeller Club Port of Sardinia was established today in Cagliari
Genoa
It is the 27th Club of the national association which includes over 1,600 members
India's Adani Ports acquires Dutch terminal operator Evos
Ahmedabad/Amsterdam
Transaction worth 2.56 billion euros
Hapag-Lloyd has completed the acquisition of a 25% stake in APM Terminals Maasvlakte II.
Hamburg
Interferry's board of directors has been renewed.
Victoria
Appointments at the association's 50th anniversary conference in Bangkok
DIS reports earnings growth in the third quarter of 2026
Luxembourg
After the boom in the second quarter, profitability remains at high levels
PORTS
Italian Ports:
Ancona Genoa Ravenna
Augusta Gioia Tauro Salerno
Bari La Spezia Savona
Brindisi Leghorn Taranto
Cagliari Naples Trapani
Carrara Palermo Trieste
Civitavecchia Piombino Venice
Italian Interports: list World Ports: map
DATABASE
ShipownersShipbuilding and Shiprepairing Yards
ForwardersShip Suppliers
Shipping AgentsTruckers
MEETINGS
Assagenti holds a single-issue meeting on the new seawall at the port of Genoa.
Genoa
It will be held on November 30th at the Italian Merchant Marine Academy Foundation
Conference "Making the Country Fly: Air Cargo, the Engine of Made in Italy"
Rome
Organized by ENAC, it will be held on November 24th in Rome
››› Meetings File
PRESS REVIEW
Cosco Shipping arm readies China IPO to capitalise on global shipbuilding wave
(South China Morning Post)
Rosatom expects cargo traffic along Northern Sea Route to rise 14% in 2026 - CEO
(Interfax)
››› Press Review File
FORUM of Shipping
and Logistics
Relazione del Presidente Mario Zanetti
Roma, 27 ottobre 2026
››› File
Arsenio Dominguez will continue to lead the IMO until the end of 2031.
London
The Council has decided. The appointment must be ratified by the assembly.
DHL grows in the third quarter, with Express and Forwarding driving revenue and profits.
Bonn
Revenue of 22.7 billion euros (+12.6%) and EBIT of 1.7 billion (+16.2%)
The EU General Court has annulled the withdrawal of recognition from the Russian naval register
Luxembourg
The investment ban and transaction ban remain in force
Italian bioLNG seeks space among ETS, FuelEU, and national incentives
Rimini
Assogasliquidi calls for simpler certification procedures and measures to make domestic production competitive.
Fincantieri and Leonardo reach agreement to strengthen Orizzonte Sistemi Navali's role.
Trieste/Rome
The companies aim to consolidate the industrial and commercial role of the joint venture
Port of Rijeka: Various cargoes push Luka Rijeka forward, while the Adriatic Gate container terminal loses ground.
Rijeka
In the first nine months of 2026, overall traffic fell by -15% to 3.83 million tonnes
Confetra: The government wants to abolish the tax on small parcels.
Rome
Satisfaction with the government's choices in the budget bill
A Port Renewable Energy Community has been established in Taranto
Taranto
Among the objectives, the development of the Apulian port as an energy hub
Filt and Uilt, the temporary port labor system is not anachronistic
Rome
To define it in this way - the unions denounce - means distorting the nature and role of Article 17 of Law 84/94.
New quarterly record for freight traffic in Albanian ports
Tirana
In the period July-September passengers decreased by -5.4%
FedEx's earnings are rising, but net profit falls 68%.
Memphis
The non-cash capital loss related to the spin-off of FedEx Freight weighs heavily
Kalmar recorded a 22% growth in new orders in the third quarter
Helsinki
Turnover stable. Net profit down 14%.
In the third quarter, sales of containers produced by CIMC increased by +30%
Hong Kong
Commercial activity driven by dry boxes (+36%). Reefer units dropped by 28%.
Ports, new investments in Tuscany and Sardinia
Livorno/Cagliari
The 2027 budget estimates for the two Port Authorities have been approved. Highlights include the Piombino dock, works in Livorno, and dredging and electrification projects in Sardinian ports.
Finding qualified personnel in Italian ports is increasingly difficult.
Naples
An analysis by Randstad Research of 13 professional profiles also highlights a marked gender imbalance
COSCO Shipping Ports reports record third-quarter revenue
Hong Kong
In the July-September period, net profit was 102.5 million dollars (+3.4%)
Approval for the 2027 budget forecast and the 2027-2029 POT of the Southern Tyrrhenian and Ionian Sea Port Authority.
Gioia Tauro
The forecast document shows revenues of approximately 24 million euros and expenses of approximately 88 million
Ravenna native Bongiovanni confirmed as president of the Federagenti Youth Committee.
Rome
Renewal of the federation's board of directors
The 2027-2029 Three-Year Operational Plan for the Central Adriatic Port System has been approved.
Ancona
308 million euros of investments are planned, of which 218 million for the Marche region and 91 million for Abruzzo.
The 2027 budget forecast for the Western Liguria Port Authority has been approved.
Genoa
New surcharge on goods postponed to 2028
DP World opens a temperature-controlled warehouse near Bologna
Bologna
Surface area of 22 thousand square meters
Saipem wins two new offshore drilling contracts
Milan
The total value of the orders is approximately 121 million dollars.
Hanwha brings Philadelphia Naval Shipyard under Defense Division control
Arlington
The goal is to integrate the construction of commercial and military ships
The Ports of La Spezia and Carrara approve the 2027-2029 Three-Year Public Works Program and the 2027 Budget.
La Spezia
Pisano: PTLP concrete and consistent with currently available resources
Port concessions: Regional Administrative Court (TAR) blocks 2025 fee increase
Rome
The appeal of Assiterminal and sixteen port companies has been accepted.
Wärtsilä sees quarterly order increases, but not in the Marine segment
Helsinki
In the period July-September the company recorded a net profit of 125 million euros (-31%)
Montaresi appointed general secretary of the Eastern Ligurian Sea Port Authority for another four years.
La Spezia
Renewal of office on the proposal of President Pisano
Double ceremony for two Explora Journeys ships at the Fincantieri shipyard in Genoa
Genoa
Launch of "Explora V" and coin ceremony of "Explora VI"
The Northern Tyrrhenian Port Authority presents the new layout of the port of Piombino.
Livorno
Gariglio: A concrete step towards industrial reconversion and the future of Piombino.
Italian CMD passes under the control of the UAE group EDGE
Abu Dhabi/Rome
Cousins Mariano and Giorgio Negri retain a significant shareholding
FS Logistix has purchased six new CZ LOKO locomotives for freight and shunting services
Rome/Prague
This is the fourth order of this type for the Czech company in ten years.
Port of Bremerhaven: The cruise ship Mein Schiff 3 collided with two container ships.
Bremen
No injuries. The cruise was canceled.
Paolo Moretti has been appointed CEO of RINA Spa.
Genoa
Giosuè Vezzuto has assumed the role of CEO of RINA Services
HD Hyundai and Kiewit to establish joint venture at new shipyard in the US
Houston/Seoul
The construction of both military and commercial vessels is planned
Konecranes' quarterly port equipment orders decline as revenue increases
Helsinki
Kuehne+Nagel's third quarter was very positive
Schindellegi
Growth in economic and operating results in all business segments
- Via Raffaele Paolucci 17r/19r - 16129 Genoa - ITALY
phone: +39.010.2462122, fax: +39.010.2516768, e-mail
VAT number: 03532950106
Press Reg.: nr 33/96 Genoa Court
Editor in chief: Bruno Bellio
No part may be reproduced without the express permission of the publisher
Search on inforMARE Presentation
Feed RSS Advertising spaces

inforMARE in Pdf
Mobile