|
The containership market in 2004
|
Huge
orderbook
Charter fortunes
The charter market
Slot charters follow the trend
Long term charters
The fleet
The operators
The second-hand market
|
| After the 2001 traumas, the year 2002 was a year
of convalescence and the full health was restored in 2003. As
for 2004, it has been the year of the superlatives. It has
witnessed a shipping boom unseen since the early 1970s oil-based
boom.
This time, the international trade is sitting on a much
larger base than 35 years ago, both in commodity variety and in
geographical pattern. One country has however become an
essential wheel: China. It is estimated that it is at the origin
of one third of the world trade growth last year.
With its economy growing at some 9 % a year and containerised
exports reaching a 30 % annual increase, China is itself at the
origin of the containership shortage and the concomitant
unprecedented levels of charter rates. But China is not alone to
fuel the shipping frenzy. First, and it is important, it is
inseparable from the purchasing power of the USA and of Europe.
Second, there are other countries which are also witnessing high levels
of exports, such as India, Thailand, Vietnam and Chile.
The rise of the Euro against the US Dollar and Asian
currencies has also implications on the containership demand. It
makes Asian products, and especially Chinese ones, cheaper
for Europe. All along the year, volumes have soared on the Far
East-Europe route, which needs more ships than the Asia-US route
because of the longer distances.
Shipowners, liner operators and port operators have been
taken by surprise by this surge. They can hardly cope with the
volumes. Ships are full to capacity out of Asia and there are
not enough of them to scoop up all the boxes that flow out from
this continent. The congestion of terminals, especially in
Europe and the US, compounds the problem, as they cause delays
to busy ships and disrupt the tight schedules of usually well
oiled weekly loops. This is a challenge for 2005.
In order to save ships, liner operators have rearranged loops
and have cut capacity on the comparatively stagnant
transatlantic trade in order to send ships on busiest routes.
The optimisation of a number of services has also led to a
better overall filling ratio, especially at each end of the
loops (even if it means filling with empty boxes, which cannot
be discounted as they have to be repositioned in one way or
another).
Owners of hired container tonnage are rewarded above all
expectations, with charter rates which are 50 % higher than the
historical peaks. Leading liner operators have anticipated a
further rise in demand for 2005 and beyond by chartering ships
for periods much longer than usual and have committed themselves
in huge newbuilding programmes.
During the second half 2004, there has been intense
chartering activity for ships to be delivered in 2005 so that
the pool of ships left available has shrunken fast, which could
in turn lead to a further round of charter rate rises once the
Chinese New Year festivities (February) end.
|
|
Huge orderbook matches strong trade growth
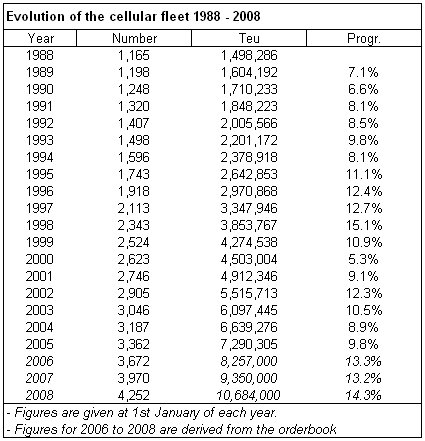
In early 2005, the cellular ships orderbook stood at 3.9
million teu, representing 53 % of the existing fleet. As big as
it is, it does not seem excessive, although it looks like
somewhat on the high side, especially for the year 2007. The huge
influx of capacity could reasonably be absorbed by the bullish
international trade, itself supported by a strong world economic
growth.
The world GNP growth has reached around 4-4.5 % in 2004
(against 2-3 % for the long term historical average). Although a
slight softening is expected in 2005, the GNP growth should
remain above the historical average, and this performance could
be repeated in 2006, in the absence of unpredictable events.
As for the international trade, it is estimated to have grown
by 7 % in US$ terms during 2004 (against 4-5 % for the long term
average). Alas no figures are available in volumes, as it is
difficult to assess because of the wide variety of goods.
The observation of long term trends shows that the cellular
fleet has grown, roughly, twice as fast as the trade growth. It
means that if the bullish trade growth of 7 % recorded for 2004
is to be prolonged during the next two or three years, then it
will generate containerised volumes needing to be moved by a
fleet growing at 14 % per annum. This is precisely the rate at
which the fleet is expected to grow during the next three years,
according to BRS-Alphaliner forecast.
Even in case of a softening, the supply-demand ratio of
containerships is to remain on the owners side, at least in 2005
and 2006, because of the catch up effect: the shortage which has
developed in 2004 must be compensated by deliveries higher than
the natural growth.
Given this, the capacity coming on stream should be swiftly
absorbed by the transportation demand during the coming months,
while a return to a balanced supply-demand ratio could occur in
2006. This should mark a turning point in box rates and charter
rates.
The situation in 2007 and beyond is another matter. Some
forecasters say that the world economic and trade growths are to
remain sustained for the remaining years of the decade, although
not at 2004 levels as a softening is expected. The question is:
what amplitude will take this softening ? The supply-demand
balance for 2007 is thus difficult to assess. Trade growth should
remain however higher than the historical average and it is a
reasonable bet.
As for 2008-2009, the orderbook has yet to be filled in. So,
orders of containerships for these two years may flow in the
coming months. Assuming that a 6 % growth in trade is maintained,
almost 1.3 million teu should be delivered in 2008 and 1.45
million teu in 2009 only to maintain the equilibrium.
If the omens for the second half of the decade are good, a
number of worries must not be overlooked, which could affect the
container shipping market. They are :
- the weakness of the US dollar and uncertainties on exchange
rates,
- a possible hard landing of the Chinese economy,
- a slowdown in the US consumption of imported products due to
a weak dollar combined with possible interest rate increases.
More immediate and foreseeable, problems will affect
container shipping in 2005 :
- the shortage of cellular ships,
- congestion in ports, leading to delays, accentuating the
ship shortage,
- strain on inland transportation networks.
|
|
Charter fortunes
Operators are living a strange paradox as they are rivalling
to fix ships at peak rates for periods of three or four years,
without knowing what the future has in store. Actually, the
charter market is not led by demand alone as far as long term
expectations are concerned. It is also propelled by skilled
operators who play the shortage game, locking up charterers for
years against discounts on rates. These discounts remain somewhat
limited when one considers the progression of charter rates over
the past two years.
With ships sometimes hired at twice their total operating
costs (including repayment of capital), owners enjoy an
unprecedented situation since container ships started to be
offered for charter, some 35 years ago.
Owners of containerships derive profits which are
reminiscent of those accumulated by oil tanker owners in the
early 1970s (Onassis, Niarchos, YK Pao, CY Tung and a crowd of
other more or less known names).
Indeed, a B-170 locked for three years at $ 27,000 per day
will raise enough profit to order a brand new ship of the same
size!
With this in mind, it is not surprising that charterers look
at buying ships. But with exceptional returns expected on hires,
sellers' conditions defy gravity and buyers think twice before
taking the plunge. Over the last 12 months, prices of second-hand ships
have roughly doubled!
Only a few operators have taken steps in order to be less
dependent on chartered ships. It concerned mostly MSC and, to
lesser extent, CMA CGM. Both have bought second-hand ships as well
as existing newbuilding contracts. Far behind, PIL and Simatech
have also bought second-hand tonnage. In another deal, Zodiac
Maritime has bought eight Panamax containership contracts for
assignment to the associated company Zim (which has sold ships as
well).
Although there is a trend among operators to order tonnage in
their name, they still rely heavily upon non operating owners,
which have relentlessly continued to book ships all along the
year.
There has been indeed a significant regular drop in the share
of chartered ships in the cellular ship orderbook, from 63 % in
January 2004 to 52 % January 2005. The lion's share of this
reduction concerns the VLCS orderbook: their chartered component
has shrunk from 58 % to 36 % (thanks, for a great part, to MSC
buying or exercising purchase options on chartered units).
Conversely, existing ships have been sold to non operating
owners. P&O Nedlloyd has sold en bloc 14 Panamax, while Zim
has sold five 3,000 teu units and Hanjin five 4,000 teu ones. All
these ships were sold with charters back to the sellers. However,
these deals have more to do with financial engineering than with
market play.
These diverging moves led actually to a slight increase in the
chartered component of the existing cellular fleet, which stands
at 47.4 %, against 47.0 % one year ago. German owners continues
to dominate the charter scene, as they control 63 % of the
chartered fleet, dwarfing Greek owners (11.5 %) and Japanese
owners (7.2 %).
A few operators are however taking advantage of peak charter
rates. As strange as it seems, they have been accepting, if not
actually welcoming, ever increasing rates for longer and longer
periods throughout the year. Maersk Sealand, MSC and CMA CGM have
been keen rivals in this race to land as many possible ships, at
the expense of others, who are either hesitant or simply do not
have a sufficiently strong financial base to follow.
These three carriers have swooped on as much ships as they
could (not to mention their unceasing order waves of
newbuildings) and are thus in a position to strongly improve their market
share.
Actually, with these peak charter rates, we are on the eve of
a new era of precipitating the concentration of the fleet in a
few hands with a new sort of natural selection. This may explain
why there has been no hurry in attempts to take control of other
operators last year. 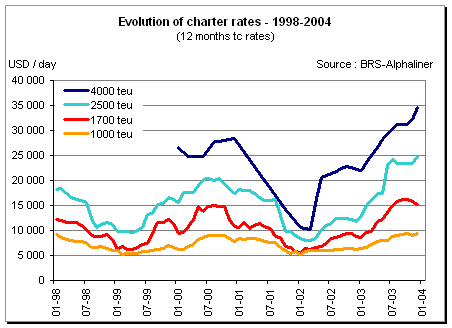
|
|
The charter market
We had speculated in our last annual report that the
highest rates observed in 2003 could well represent the average
rate for 2004. Not only they did, but they went much higher!
With ships as rare as ever, charter rates have exploded to
levels which are 50-60 % above the historical highs observed
during the summer 2000. Besides record rates, the year 2004 has
been characterised by a lengthening of charter periods and by
fixing ships six or twelve months in advance.
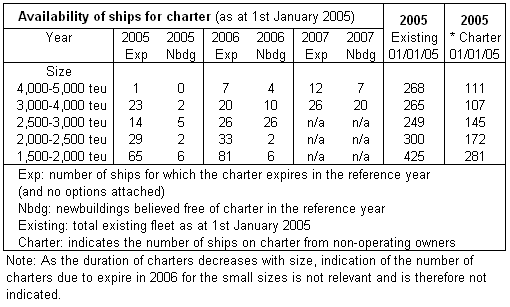
These two latter trends have dried up the pool of large ships
(both existing and newbuildings) available in 2005. Charterers
are now eating into the 2006 available fleet, and a market for
sublets has started to emerge.
The rally on the charter market continues and owners are
reaping the benefits of the shortage of tonnage. The lack of
adequate tonnage to launch new intercontinental loops has
thwarted the plans of several carriers.
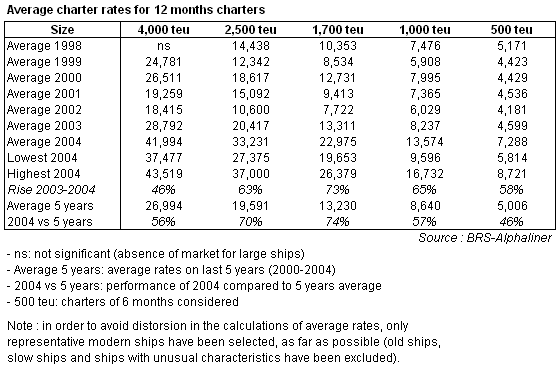
In December 2004-January 2005, 4,000 teu ships were hired at $
40-45,000 per day for 12 months period while 2,500 teu ships were
valued at $ 35-37,000. Ships of 1,700 teu peaked at $ 27,000 for
4 years periods. 1,000 teu ships were negotiated at $ 18,000 for
6-12 months.
The tonnage scarcity and the high demand on regional and
feeder trades have sent rates soaring for smaller ships as well.
Cellular ships of 800-850 teu are not cheap, as they reach now the
$ 15,000 mark for 12 months (against $ 8,000 end 2003). Modern
ships of 500 teu ended the year at $ 9,000 for 12 months (against
$ 4,400-4,800 during the three years pre-2004, and for periods of
3 to 6 months).
If top rates are good news for owners, carriers relying only
upon chartered tonnage do not share the same enthusiasm. Among
them are several niche regional carriers and feeder operators.
They use small ships (under 1,500 teu), which until early 2004
could still be hired at fair rates, but have since reached such
levels that services will have to be reviewed or cut.
|
|
Slot charters follow the trend
A little spoken aspect of the container trades concern slot
charter rates. As ship charter rates have soared, so have slot
charters. Some slot chartering agreements are referring to
charter market conditions, and the slot charter rates are
reviewed at regular intervals. Other ones are fixed for the
duration of the agreement which is usually not more than two
years.
Slot charter rates can be indexed on ship charter rates as
well as other operational costs, such as voyage costs, including
cost of bunkers, canal tolls or port dues. As the ship charter
rates item is the heaviest one, it is then not surprising that
slot charter hires have risen strongly, leading even to the
non-renewal of some agreements.
In this period of tonnage scarcity, those who run the
ships may find quite profitable to fill them at full capacity and may not wish to offer their precious earning space to others
(which are after all rivals), unless they pay the price.
Operators are now very careful when it comes to enter slot
exchange agreements with other lines, as they evaluate risks of
failure of partners, especially in the case of small operators
whose financial standing may not be strong enough to survive the
high charter hires.
There has been during the past year a number of changes in
partnerships and slot buyer participation, which may have been
caused by tensions created by space shortage on a background of
ship shortage and of peak charter rates. On the other side,
several operators are teaming up to launch new services with
chartered ships, thus sharing the burden of expensive charter
hires while being able to offer the needed weekly frequency. Such
a way of doing business is of course not new, but it is
exacerbated by current market conditions.
|
|
|
|
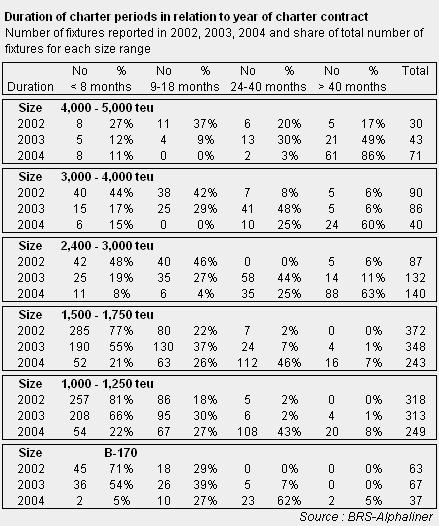
Long term charters dominate the market
Periods of four years and more for 4,000-5,000 teu ships
accounted for 86 % of the reported fixtures in 2004, against 49 %
in 2003 and 17 % in 2002, according to a BRS-Alphaliner analysis.
Smaller ships have also been fixed for much longer periods than
the usual 12 months. Periods of 24 to 40 months for 1,500-2,000
teu ships accounted for 46 % of the reported fixtures in 2004,
against 7 % in 2003 and only 2 % in 2002. The accompanying table
details how the duration of charter periods evolved from 2002 to
2004.
|
|
|
|
|
The fleet
At 1st January 2005, the cellular fleet reached 3,362 ships
for 7.29 million teu, in progression of 9.8 % on 12 months, a
relatively modest increase as the average annual progression
during the past 10 years has reached 10.7 %. The cellular fleet
accounts for 89 % of the total fleet deployed on liner trades in
teu terms.
The containership fleet counts 49 units of more than 7,500 teu
and there are 165 more of these giants on order, some of them
reaching the 10,000 teu mark. By the end of 2007, there will be
enough of these leviathans to run 15 Asia-Europe and 15 Asia-US
loops.
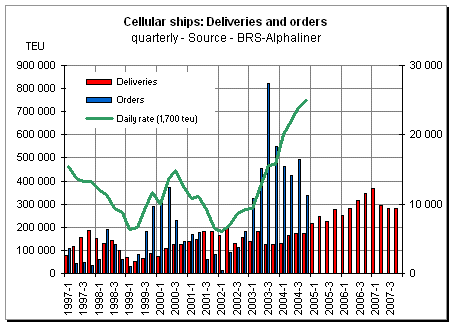
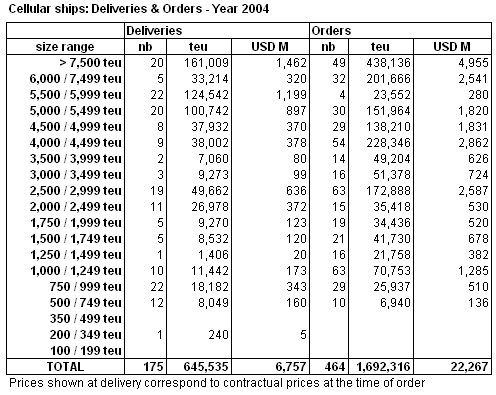
2004 deliveries stood at 175 ships for 645,000 teu (against
177 ships for 575,000 teu in 2003). Orders stood at 464 ships
for 1,692,000 teu, which is significantly less than the record
520 ships for 2,123,000 teu ordered in 2003.
The total value of cellular ships ordered in 2004 reached
almost $ 22.2 billion (using conversion rates at time of order),
a figure similar to 2003, reflecting the steep rise in
newbuilding prices ($ 13,150 per teu instead of $ 10,350 per teu
in 2003 - raw figures unadjusted for capacity).
The total orderbook reaches 3.9 million teu in early 2005,
representing 53 % of the existing fleet. It is dominated by large
ships, with ships over 4,000 teu accounting for 74 % of the total
orderbook. As for deletions, only five ships for 2,450 teu were
sold for scrap last year.
The teu capacity which will enter the market during the three
years 2005, 2006 and 2007 corresponds to 47 % of the existing
fleet. In other terms, the fleet is to rise by almost 14 % per
year, well above the 10 % average observed during the past 15
years. The cellular fleet is expected to reach 10.8 million teu
in January 2008 (assuming no scrapping)
|
|
The operators
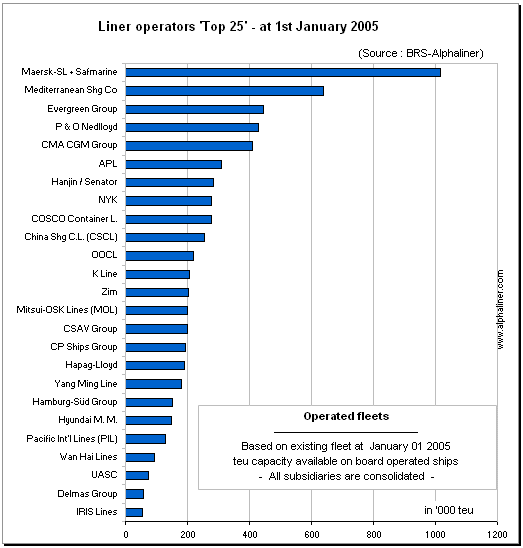
From 1st January 2004 to 1st January 2005, the combined fleet
of the Top 25 carriers has grown from 5,955,000 teu to 6,640,000
teu (+11.5 %). Its share of the world fleet deployed on liner
trades has risen from 79.6 % to 81.3 % in teu terms, confirming
the concentration trend.
The five largest carriers alone operate 39 % of the
capacity effectively deployed on liner trades.
The total teu capacity deployed on liner trades has grown by
9.1 % in 2004, reaching 8,168,000 teu st at 1st January 2005,
against 7,485,000 teu one year earlier. In deadweight terms, the
figure stands at 7.5 %, with 120 million dwt at 1st January 2005
against 111.5 million dwt one year earlier.
These figures take into account all the types of ships
deployed on liner trades (cellular, multipurpose, ro-ro). The
cellular fleet itself amounts to 7,290,000 teu (it represents
89.2 % of the total teu figure deployed on liner trades).
The two largest carriers, APM-Maersk and MSC contributed to 29
% of the fleet growth in teu terms, with 197,000 teu out of the
683,000 teu added (+101,000 teu for MSC and + 96,000 teu for
APM-Maersk).
APM-Maersk became last December the first teu millionaire, as
its fleet reached 1,016,000 teu on 1st January 2005. APM-Maersk
controls Maersk Sealand, Safmarine, Norfolkline and APMSS-MCC.
MSC comes at the second position with 637,000 teu.
These two leaders are however not among the top teu gainers in
relative terms. MSC grew by 18.9 % and APM-Maersk by 10.4 %. They
are distanced by four carriers (within the Top 25) which have
logged growths of 28-33 %: CSAV, CSCL, Yang Ming and CMA CGM.
Outside the Top 25, the emergence of two Chinese regional
companies is worth noting: SYMS (+24.4 %) and SITC (+20.2 %).
On the mergers & acquisition side, no large mergers or
takeovers occurred between rival carriers. The most significant
one has been the buying by Costa Container Line of its compatriot
Gilnavi. It appears that aggressive carriers (read: potential
buyers) have found ways to increase market share in securing as
many ships as they can, leaving conservative ones with what is
left, i.e. not much choice and pricey.
On the other side, some potential targets have protected
themselves from raiders, such as NOL-APL or TUI-Hapag-Lloyd, in
steering clear of market listing. Despite this, there is still a
choice of first class carriers which remain potential targets: CP
Ships, Royal P&O Nedlloyd, Hanjin-Senator and Hyundai M.M.
There has been however important initiatives on the corporate
side, such as Temasek Holdings, the Singapore state investment vehicle,
taking control of NOL, parent company of APL, in what can be seen
as a move to keep at home the Singapore historical carrier, until
then listed on the local Stock Exchange. Other large deals
concerned the purchase by Royal Nedlloyd of the whole stock of
P&O Nedlloyd and the takeover of Zim by the Ofer Group.
CSCL made the news with its listing on the Hong Kong Stock
Exchange in June, while intentions to list Hapag-Lloyd faded away
as parent company TUI changed its mind and preferred to keep the
full control of its Hamburg jewel.
There has been numerous smaller deals, which are summed up in
the accompanying table.
|
|
Operators : transactions and significant moves in 2004
Straight sales & mergers
- Temasek Holdings (Singapore) has taken full control of NOL,
parent company of APL.
- Royal Nedlloyd B.V. (Netherlands) has taken 100% control of
P&O Nedlloyd Containers Ltd (UK) through the purchase of
the 50 % stake held by the Peninsular and Oriental Steam
Navigation Co (i.e. P&O Group). The resulting company,
Royal P&O Nedlloyd Ltd, is listed on the Amsterdam Stock
Exchange.
- The Ofer Group (Israel) has taken control of Zim Navigation,
since renamed Zim Integrated Shipping Services Ltd.
- Costa Container Line took over the deep sea liner trades of
Gilnavi srl di Navigazione, the liner arm of the
Grimaldi-Genoa branch.
- The Carlyle Group has sold Horizon Lines to private equity
firm Castle Harlan. - STX Corp. (Korea) has bought 67 % of Pan
Ocean Shipping Co (Korea).
- Neptune Orient Lines (NOL - APL parent company), Singapore,
agreed to sell its 28.7 % stake in Lorenzo Shipping Corp to
National Marine Corp. (both Philippines).
- Neptune Orient Lines Ltd (NOL) has sold Neptune Associated
Shipping Pte Ltd (NAS) (tankers & bunkering).
- Eimskip (Iceland) and Faroe Ship (Faeroe Islands) have
merged.
- Euro Container Line AS (ECL) (Norwegian company co-owned by
Eimskip and Wilson Line) took over Norwegian operator CoNor
Line.
- Rickmers Reederei GmbH & Cie KG (Bertram Rickmers
Group), has taken over all of the shares in CCNI GmbH
(Deutschland) from Compa''a Chilena de Navegaci'n
Interoce'nica SA (Santiago).
- Egyptian company MISR Shipping has been absorbed by its
compatriot National Navigation Co (NNC).
- Trailer Bridge Inc. (USA) bought 100 % of Kadampanattu Corp.
(K. Corp.) from the Estate of Malcom P. McLean (USA)
Transfers and moves within operating groups
- NYK and its affiliate TSK have decided to spin off their
respective domestic liner service operations and related
businesses, to set up NYK Line Japan Ltd (effective April
2005).
- China Shipping Container Lines (CSCL) boosted its share in
the Shanghai Puhai Shipping Co, Ltd (SPS) from 50 % to 90 %
held by other China Shipping units.
- Hamburg-S'd abandoned its trade name Ellerman Line.
New operators of liner services
- Manson Shipping (Taiwan) - services Taiwan-Hong
Kong-Vietnam-Philippines.
- Winland Shipping Co, Ltd (China) - services Weihai-Japan.
- Dalian Beiliang Logistics Containers (China) - service
Dalian-Weihai-Japan.
- HAL Shipping (Halship) (Canada) - service Halifax-USEC.
- Delphis NV (Belgium) is incorporated (intra Europe
services).
- AC Forwarding (ACF) and Hudig Veder & Dammers (HVD) form
AC Ireland Line.
- Black Sea Container Shipping Co launches intra Black Sea
service.
Cessations of activity in liner shipping
- CT Navigation (Taiwan) closed its services (Taiwan-Hong
Kong-Vietnam-Philippines).
- Hong Kong Ming Wah (HKMW) has closed its only service (Hong
Kong-North China), marketed under the Chiu Lun Transportation
name.
- SPM Shipping (St Pierre & Miquelon) ceased its activity-
service Halifax-USEC.
- Armada Line closes its North Europe-Med service.
- Blue Container Line (Greece) closed its services (Intra Med
and Black Sea).
Significant other moves
- China Shipping Container Lines (CSCL) has been listed on
Hong Kong Stock Exchange.
- Norwegian shipowner John Fredriksen has bought stakes of 3
to 10% in Hanjin Shipping, Hyundai Merchant Marine, Royal
P&O Nedlloyd and NOL.
- EOX Group Bhd has been renamed HubLine Berhad.
- The liner division of Unicorn Lines has been renamed Ocean
Africa Container Line (OACL).
- TECO Lines is created by Samskip and Estonian Shipping Co.
- DAL left the West Africa trades.
- Steamers Maritime (Singapore - Keppel Group) has sold its
whole fleet of ten containerships.
|
|
|
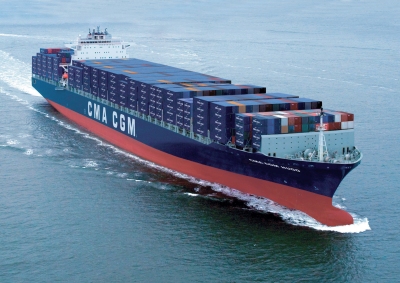 |
CMA CGM Hugo
100,400 dwt, delivered in 2004 by Hyundai, owned by Conti Reederei, operated by CMA CGM
(Copyright CMA CGM) |
|
|
|
|
The second-hand market for
containerships in 2004
|
|
2004, an exceptional vintage! This is certainly true for almost all
shipping markets. The year 2004, with no less than 265 sales of pure
containerships (of which 44 resales of ships under construction or
ordered) and 126 other ro-ro and multipurpose ships, compared to
respectively 181 and 104 ships last year. Nonetheless this leaves a
feeling of frustration for a number of buyers who were not able to
achieve all their intended investments.
This frustration is caused by the evident lack of tonnage for sale,
even at very high prices. Many owners, due to lack of prompt yard slot
availability, preferred to go on the charter market for periods
sometimes as much as 3, 4 or 5 years, but who can blame them'
A simple example illustrates the mood that reigned throughout the
second half of the year: the owner of the m/v 'Lissy Schulte' (B170 -
1,730 teu, built in 1995) refused an offer of no less than $ 30
million and has finally been fixed firm to P&O for 48 months at
level of $ 26,500 per day! According to our calculations the result of
this charter is equivalent to about $ 35 million. We now understand
why this ship has not been sold even at such a price level.
The other specificity of the second-hand market for containerships
in 2004 is, without any doubt, the number of sales in the 500 to 2,000
teu size range, and more precisely from 800 to 1,200 teu. There were
no less than 15 to 20 potential buyers who found themselves chasing
the rare units being put on the market. There was again this year an
outright winner in the person of Mr Aponte (MSC, Geneva), with a total
of some thirty ships bought in 2004, to which should be added the
purchase of some ten newbuilding contracts initially ordered by German
owners.
German owners bought some sixty ships. It is interesting to note in
this respect that it is virtually impossible to compete with a German
buyer on a modern ship offered on the market when it is controlled by
German interests. A good lesson in self-protection!
Also, whilst in the past ships already under long-term charter were
gaining popularity amongst buyers, this year ships that were
"time-charter free" were by far the most sought after. In
the absence of charter free tonnage in 2004,
a large number of buyers went after containerships still employed up
until the end of 2005.
Despite the high prices paid, buyers had to be patient for several
months before they were able to benefit from a chartering market for
which they hope it will stay at least as good as today's levels. As to
liner operators, purchases of this kind proved to be essential once
they had to ensure operating the necessary tonnage on their regular
services.
The principal "en-bloc" sales which can be reported this
year are:
- 5 x 3,500 teu and 9 x 4,200 teu (14 ships) built in 1991, 92,
93, 94 and 95 from P&O Nedlloyd to MPC Capital for a total of
$ 660 million.
- 4 x 2,824 teu Hyundai contracts for delivery between 2005 and
2006 resold by Erck Rickers to CMA CGM for $ 44 million each.
- 8 x 4,250 teu Dalian New contracts for delivery between 2006 and
2007 resold by Bertram Rickmers to Zodiac.
- 7 x 1,538 / 1,658 teu built between 1998 and 2000 by Jiangnan
and HDW, from clients of Silver Line (who bought the entire fleet
in 2001 for $ 100 million) to MSC for $ 130 million.
- 10 ships of 369 to 1,012 teu, sold by Keppel Group (Steamers) to
Interorient for $ 91 million.
- 4 x 5,050 teu, Hanjin shipyard contracts for delivery in 2006,
resold by Rickmers to MSC for $ 63.5 million each.
- 5 x 3,039 teu built between 1990 and 1992 by HDW, sold by Zim to
Torvald Klaveness and Icon Capital for $ 35 to $ 38 million each,
with a bare-boat charter back to Zim.
- 4 x 2,394 teu (20 knots) built in 1994 in Spain, sold by Zodiac
Maritime to MSC for just over $ 30 million each.
- 4 x 2,524 teu built by Kvaerner in 2003 and 2004, sold by an
Andreas Ugland-associated company to the bare-boat charterer of
the ships, Hamburg-Sud, for $ 35 million each.
|
Number of pure containerships sold by size:
| Less than 900 teu: |
82 |
| From 900 to 2,000 teu: |
83 |
| From 2,000 to 3,000 teu: |
42 |
| Over 3,000 teu: |
58 (of which 28 contract resales) |
|
|
| Total number of ships sold in 2004: |
265 |
| Total capacity of ships sold in 2004: |
500,145 teu |
Containerships under 900 teu
Together with the normal flow of activity this year, we have seen
a search by certain buyers for ships smaller than what they
originally needed. Prices for some ships have occasionally doubled
between mid-2003 and end 2004. Even ships that can hardly been
classified as "suitable" on this market, such as a
slow-speed vessels or those with gears unable to perform a standard
loading/unloading rate, have found buyers at more than favourable
conditions for their owners.
Buyers based in the Far East, Germany and Greece were, in this
order, the most active within this size category.
Interorient's deal of buying the feeder fleet of the Keppel Group
for $ 91 million fairly well reflects the mood of the market this
year. A fleet which has been on the market throughout the whole year
2003 and which was finally sold at the beginning of 2004. Since
then, one can estimate the theoretical gain in the value of each
ship to be at about 50 to 60 %.
Containerships of 900 to 2,000 teu
This has been by far the most active sector of the second-hand
containership market! A cascade of sales, dozens of buyers, ships
sometimes for sale, sometimes withdrawn, escalating negotiations
with the seller rising his price at each stage of the negotiation'..
in short a happy shambles within the context of euphoric freight
rates and second-hand prices.
This situation is particularly true since the summer of 2004. At
that time buyers were struggling with the steady disappearance of
charter-free ships. The few units still available in 2004 and 2005
will become targets for owners such as MSC, Zim or CMA CGM'
Containerships of 2,000 to 3,000 teu
This sector saw only a small progression this year with some
fifteen more ships sold compared to last year. At the end of the
year owners of newbuilding contracts for delivery in 2005 did not
hesitate to ask for ' 45 million ($ 60 million) for a gearless
ship of 2,700 teu. In short, the lack of tonnage explains some
excess in ship's valuations.
Containerships of 3,000 teu and more
Fifty percent of the 58 deals done this year were newbuilding
contract resales. This segment of the market was dominated by
Zodiac, MSC and above all the German KGs, always very keen about
ships of this size, which combine several favourable factors to
investors:
- a market predominately stable and secure,
- a popular size and already well-known in Germany, thus a
relatively good market knowledge by investors,
- a satisfactory "liquidity" of the assets and
reliable charterers.
One of the rare pure second-hand operation done this year was the
one involving the 3 ships of 3,187 teu controlled by Talcar, Israel,
built respectively in 1986, 1986, and 1988 at a price of $ 80
million en-bloc with delivery in 2005 to MSC.
|
| Demolition
Out of the 52 ships demolished in this category, only 5 were pure
containerships, the latter totalling a mere 2,450 teu. The others
were either multipurpose or conventional cargo ships. This low
scrapping level is a direct consequence of the firmness in the
freight market. Scrap metal price levels have been hovering in the
region of $ 400 per lightweight ton
|
| Conclusion
The world cellular fleet has increased this year by 9.8 % to
reach 3,362 ships (7,290,000 teu). This evolution is in line with
the annual average growth of the past 15 years. However we already
know by now that the shipyards will deliver a capacity of 47 % of
the existing fleet in the course of the next 3 years. This
represents a growth of about 14 % per year!
The demolition market usually hits ships of 27 years or more on
average, which in the best case will only shrink the world fleet by
3.2 % of its current capacity.
The question is therefore: will Asia, and especially China whose
strong export industry has continued to expand, be able to absorb
this additional tonnage? A large number of players, both on the
industrial as well as the shipping side, believe that it will. It is
however a very complex exercise to predict the strength of such a
market. As we all know, to simply maintain it at its present levels,
it depends upon China and its neighbours, whose growth in turn seems
to be in their own hands.
|
Shipping and Shipbuilding Markets in 2004
I N D E X
|







 - Via Raffaele Paolucci 17r/19r - 16129 Genoa - ITALY


