|
The containership market
in 2003
|
The
charter market
The fleet
The operators
The second-hand market
|
|
|
After the 2001 traumas, the year 2002
was a year of convalescence, and full health was restored in
2003. And what health! The seaborne containerised trades have
boomed, box rates have risen on most trades and virtually all
operators have renewed with profits. The year 2004 has opened on
a rare optimistic note, which has not been seen since the early
1970s boom.
Demand in containerships has reached
record levels. An unprecedented wave of orders has poured into
shipyards. Charter rates have soared and have yet to reach their
climax. Opinions differ depending of course who you ask, but as
one charterer puts it, 'The charter rates will probably be the
only cloud in the otherwise blue sky'.
This rise in container transportation,
and international trade as a whole, is explained by several
factors. First, the adjustment effect following a stagnant year
2002, then, a lot of countries saw their industrial production
booming again, and third, one of these countries is China, with
its already huge economy having logged a 9 % growth in 2003 and
is export-oriented.
The slump of 2001-2002 led to fears of
durable overcapacity. In fact, the strong growth in transport
demand observed over the past 18 months combines both the long
term growth and a post-slump adjustment in volumes carried,
although it owes much to the Chinese export boom.
Taking a long-term view, the planned
fleet expansion, in relation to the orderbook, will just match
the growth of the demand - at least until end 2005. The balance
is to remain in favour of owners for the whole of 2004 and for
most of 2005. In late 2005 or 2006, the pendulum could swing back
given the calendar of ship deliveries (the supply-demand balance
may reach a critical stage).
However, the depression -if any- could
be temporary should there be a drop in deliveries in 2007. And
with shipyards filling rapidly their 2007 building slots with
tankers and bulk carriers (also much in demand), less capacity
will be left to order big containerships in large quantities.
|
|
The China effect
In 2003, Chinese ports have handled 48
million teu, against 37 million teu in 2002, i.e. an increase of
some 30 % in one year (and daily movements of 100,000 teu). The
performance may be difficult to be repeated in 2004, but even
with a lesser rise, it will be a boon for carriers.
So, the big question for 2004 (and the
years to come) is: Will it go on?
China has benefited for several years
of a transfer of manufacturing activities from mature economies.
There is no doubt that this movement is far from being completed,
given China's large reservoir of cheap manpower. But it may slow
down at some point, and exports may not rise as fast as they
did.
On the other side, as Chinese citizens
get richer, they can afford more and more imported consumer
products, or industrial components needed to manufacture consumer
products. A side effect of these trends is that it would reduce
trade imbalances.
There are also uncertainties. It is too
early to know if the Asian Bird Flu will have an impact on trade,
but if the SARS epidemic is a guide, tourism could suffer, but
trade would not (except for the poultry business).
The Euro appreciation effect
Another key factor is the dramatic
evolution in currency rates, with the euro having appreciated by
20 % against the dollar during 2003, while most Asian currencies
did not appreciate at the same rate, far from it. 2004 will
witness the full year impact of the high purchasing power of the
euro vis-a-vis Asian currencies, which will boost the Asia-Europe
trade westbound, but may also deepens the eastbound-westbound
imbalance.
As for the Asia-US trades, the relative
weakness of the dollar against most Asian currencies may dampen
American buying of Asian products and may have a positive effect
on the trade imbalance. However, it does not work for the
China-US trade, as the Chinese yuan remains pegged to the dollar,
despite pressing US demands to re-evaluate it.
If trade remains as healthy as it is,
one can wonder how far charter rates can go if the 2004
transpacific summer season sees volume grow by 8-10 %, not to
mention the rises expected on Asia-Europe. It will lead to an
acute shortage of containerships. Contrary to other peak times
(such as the summer 2000), conbulkers will not be of great help
as they obtain still higher rates on the bulk market than on the
container market.
|
|
The charter market |
|
|
|
Keeping the market share in 2004
will be a costly exercise for the operators which have been
late to react. Those who have chartered ships several months
in advance for 2004 delivery, will be more at ease. MSC has
even gone further, buying 34 ships of 1,000 to 3,500 teu in
2003, which will allow savings on charter hires (despite the
relatively high price paid for some of them).
Of course, charterers react, but
they have not much room to manoeuvre. The main sweetener to
sky high rates is the length of charter periods. During the
second half 2003, duration of 36 months have become a rule
for ships of more than 2,500 teu, with owners conceding
10-15 % discount against the 12 months daily rates.
With only a very few large ships
left available in 2004, the most dynamic operators will have
no options but to accept ultra high rates to snatch ships
which arrive at the end of their charter from their current
operators, who will obviously be ready themselves to pay the
price to extend them.
For these latter ones, losing the
bid would lead to the disruption of well oiled weekly norias
- unless of course they receive a sufficient number of large
newbuildings or have covered their 2004 positions with
charters negotiated in 2003, which is the case for half a
dozen of the large operators.
A number of operators have indeed
covered their positions and protected themselves from
possibly sky-high rates in 2004. Operators with a high
component of owned ships in their fleet will be also in a
quite confortable position. Conversely, high charter rates
are a real burden for operators engaged with 100 % chartered
tonnage, and box rates are far from having risen at the same
pace.
The latter ones count niche
operators and some common feeder carriers. Now that their
previous, relatively cheap charters arrive at their term,
they have to extend the ships at the high rate. It may
effectively encroach on their margins, and some of them are
trying to rationalise their services in order to save one
ship or two. Happily enough, they run a lot of smaller ships
(under 1,500 teu) for which the rates remain reasonable.
Similarly, large operators may cut
down services for which the profitability is jeopardised by
high charter rates, opting instead for alternatives, such as
slot buying or partnership with rivals.
As ships of around 4,000 teu are
to remain a very scarce commodity during the year 2004, and
even beyond, owners are in a position to ask, and obtain,
rates of $ 40,000 for the few ships seeing their charter
periods expire this year. Charterers will have to accept
such high rates if cargo volumes dictate, to maintain their
market share.
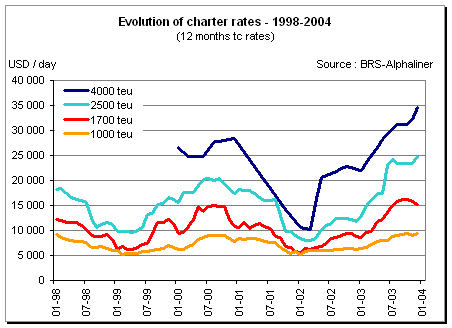
The charter market for 4,000 teu
ships took off in 1999 and peaked in the summer 2000 at
$ 29,000 before sinking in the 2001 gloom. It has since well
recovered.
In September 2003, an historical
high of $ 32,500 has been reached for a 4,158 teu ship
chartered for a period of six months. It is the first to be
known as having broken the psychological $ 30,000 level. Two
months later, a 4,038 teu ship went at the same $ 32,500
rate, but for a much longer period of 2.5 years (meaning
that, had the ship been fixed for a 12 months period, the
rate would have passed the $ 35,000 mark).
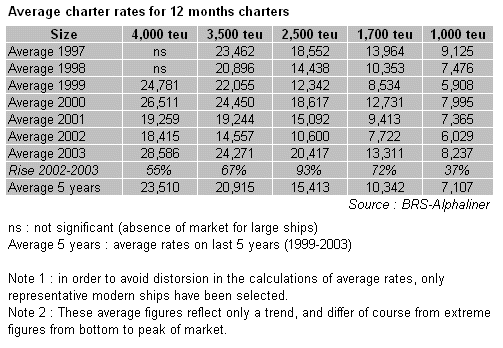
Ships of 2,500 teu have scored the
highest rate rise in 2003, with average rate levels 93 %
higher than in 2002, as can be seen from the accompanying
table. 2,500 teu ships closed the year with daily hires of
$ 24,750 for 12 months periods, up from the depressing lows
of early 2002, when owners had to accept a miserable
$ 8,000. And rates are still going up, with a 2,500 teu ship
having reached an historic $ 30,000 for 12 months in early
2004.
By comparison, the least
advantaged size, 1,000 teu, gained only 37 % to $ 8,237, and
is still well below the $ 10,500-11,000 averages observed in
the mid-1990s.
As for ships of 1,700 teu, they
are traded in the same way that tramp cargo ships were
traded 40 or 50 years ago, acting as stop gap ships and as
sweeping ships on east-west trades as well as playing a key
role on many secondary trades.
Ships of this size come and go,
with sometimes surprising movements in charter rates. This
trend was well illustrated in December-January: while rates
for B-170s (the 'barometer ship') fell just under $ 10,000
for 2 or 3 months periods, they remained above $ 15,000 for
ships fixed for 12 months periods, and going up once the
Chinese New Year festivities ended, with a all time record
of $ 20,000 recorded in February 2004 for a B-170 fixed for
3 months.
Rate rises have been much more
modest for ships of around 1,000 teu. But rates could be
pushed up in 2004 as charterers may be forced to charter
smaller ships than they wish if the scarcity effect reach
the 1,500-2,000 teu size.
Actually, the highest rates
observed in 2003 could well represent the average rate for
2004, if the world economy remains as sustained as it is,
especially the Chinese one, as far as seaborne
transportation is concerned.
As for ships above 5,000 teu, they
are not yet played on the daily charter market and are
contracted for long periods (above five years). Ships of
5,500 teu are negotiated at around $ 28,000 for 7-10 years
periods. As for charter rates for 8,000 teu ships hired for
long periods (10 to 12 years), they stood in the $ 29,500 to
$ 31,000 range in 2003, with a trend towards $ 32,000-33,000
in early 2004. Such ships could be ordered at a price of
$ 70 million in early 2003, rising to around $ 80 million in
early 2004.
|
|
|
|
Long-term
charters become the rule
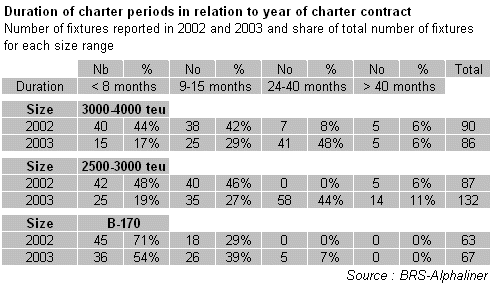
Periods of 24
to 40 months for 3,000-4,000 teu ships accounted for 48 % of
the reported fixtures in 2003, against 8 % in 2002,
according to a BRS-Alphaliner analysis, For 2,500-3,000 teu
ships, the figure stands at 44 % in 2003 while no charters
of such a duration was reported in 2002. The accompanying
table details how the duration of charter periods evolved
from 2002 to 2003.
|
 |
| The fleet |
|
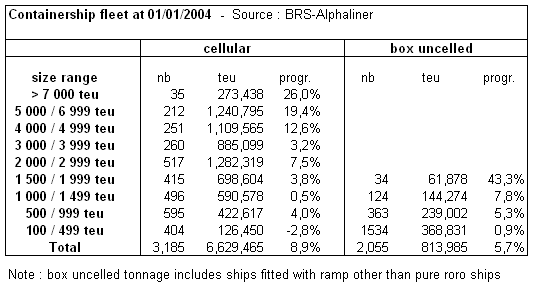
At 1st January 2004, the cellular
fleet reached 3,185 ships for 6.63 million teu, in
progression of 8.9 %, a relatively modest increase as the
average annual progression during the past 10 years have
reached 10.7 %. The cellular fleet accounts for 88.5% of the
total fleet deployed on liner trades in teu terms.
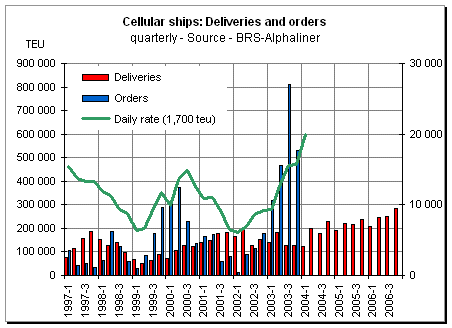
2003 deliveries stood at 177 ships
for 575,000 teu (against 201 ships for 646,000 teu in 2002).
Orders stood at a record number of 520 ships for 2,123,000
teu, sending the total orderbook to 2.7 million teu in early
2004, representing 41 % of the existing fleet. The total
value of cellular ships ordered in 2003 reached almost $ 22
billion. By comparison, in 2002, only 82 ships for 363,000
teu were ordered for $ 3.7 billion. As for deletions, 34
ships for 32,839 teu were sold for scrap last year (in 2002:
59 ships for 74,001 teu).
The cellular fleet is expected to
reach 9.15 million teu in January 2007 (assuming no
scrapping), i.e. an average annual progression of 11.3 %
within the three years to come. Furthermore, virtually all
the large ships are capable of speeds over 24 knots, meaning
that the transport potential will rise even faster.
Given the schedule of deliveries,
the size of the fleet may enter the 'danger zone' in the
second half of 2005, and 2006 could be a year of low charter
rates.
The value of such warnings is
however very relative, because it is impossible to forecast
the level of the demand with a sufficient accuracy in two or
three years time. After all, supposing that Chinese exports
remain sustained (even at a lower rate than observed in
2003) and that both the USA and Europe economies are
healthy, driving with them other countries as well, it could
lead to a transportation demand which could absorb the huge
capacity which is to come on stream.
But sooner or later, a political
or economic event of an unforeseeable nature will make the
bubble burst, with the resulting nightmare that nobody wants
to dream about.
|
|
|
The year of the 8,000 teu ship
Eighty percent of the capacity
ordered in 2003 concerned ships of more than 4,000 teu.
Among these large ships are 109 ships of over 7,500 teu,
boosting the order book for such ships to 126 units at 1st
January 2004, while only 30 ships above 7,500 teu are in
service.
VLCS (Very Large Container Ships)
of 8,000-10,000 teu will be the workhorses of the Asia-US
and Asia Europe route during the second half of the decade.
At the beginning of 2007, 140 ships of more than 7,500 teu
will ply the high seas. It will be enough to run 12
Asia-Europe loops and 12 Asia-US loops (offering a weekly
capacity of 100,000 teu on each of these two routes). In
2010, there could be as much as 300 of these giants in
service.
The injection of VLCS on high
volume routes will displace 5,000 teu tonnage on secondary
east-west routes, while 3,000-4,500 teu ships will be
displaced on niche east-west routes (such as those launched
in 2003 between Asia and Black Sea) and of course on
north-south routes.
This raises a question: what size
range will be the most affected by the cascading triggered
by massive deliveries of VLCS? Before trying an answer, it
must be considered that 2,400-2,700 teu ships have also been
much in favour in 2003, with 64 orders in this size range.
Actually, 2,500 teu ships are
expected to play in 2006-2007 the roles currently ensured
with 1,700 teu ships. There are already a lot of 2,500 teu
ships around. These existing ships and the new ones will
make redundant 1,700 teu ships on many trades.
In early 2007, there will be some
280 ships of 2,400-2,700 teu and there could be as much as
370 in the 1,500-1,750 teu range. It appears to be difficult
to displace as much ships on feeder trades or regional
trades. Thus the 1,500-1,700 teu ships will probably be the
size which will suffer most from the cascading effect.
General cargo
carriers tenfold increase in size
Back in the
1960s, when containers started to appear on the decks of
conventional cargo ships plying international routes, one
would have been more than sceptical of hearing of 100,000
dwt general cargo carriers plying the high seas. It would
have been interpreted as a year 2000 extravaganza.
Such giant
ships are today amongst us, with the generalisation of the
8,000 teu ship. Such ships allow a new step on the
productivity scale to be climbed. An Asia-Europe service
operated with eight ships of 8,000 teu plying at 25 knots
carries about the same cargo quantities than eight services
of conventional cargo vessels of the 1960s.
In these
pre-box times, a typical full scale Asia-Europe service
employed about 20 ships of 10,000 dwt and 16 knots. In other
words, a single 8,000 teu ship has a transport capacity
matching the capacity of some 20 cargo vessels of 1960s
vintage (taking into account dwt capacity, speed, and time
spent in port).
|
|
The operators |
|
In 2003, the total teu capacity
deployed on liner trades has grown by 9.3 %, reaching
7,485,000 teu as at 1st January 2004, against 6,850,000 teu
one year earlier, according to BRS-Alphaliner data.
In deadweight terms, the figure
stands at 7.3%, with 111.5 million dwt at 1st January 2004
against 104 million dwt one year earlier. These figures take
into account all the types of ships deployed on liner
trades. The cellular fleet itself amounts to 6,625,000 teu,
i.e. 88.5 % of the total teu figure deployed on liner
trades.
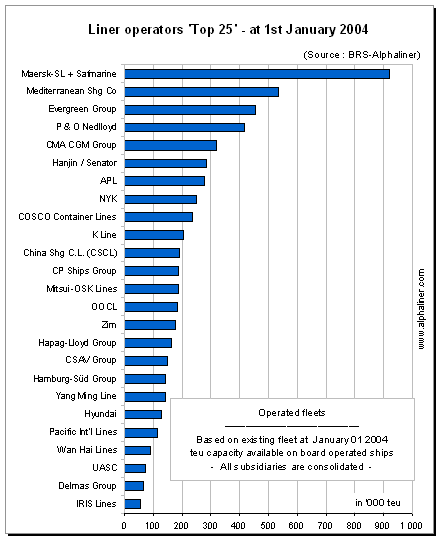
The capacity of the fleets of the
Top 25 operators has grown by 12.3 % during the year 2003,
which is in line with the average Top 25 growth rate
observed since 1997. From 1st January 2003 to 1st January
2004, the Top 25 fleet has grown from 5,302,000 teu to
5,955,000 teu.
Its share of the world fleet
deployed on liner trades has risen during the period from
77.4 % to 79.6 % in teu terms, confirming the concentration
trend. The five largest carriers alone concentrate 35 % of
the capacity effectively deployed on liner trades.
The largest of them,
Maersk-SeaLand, operates a capacity of 920,000 teu,
representing 12.2 % of the global active capacity in teu
terms. The next in size is MSC, with 536,000 teu and 7 % of
global market share.
Among the ten largest operators,
CMA CGM is the incontestable teu gainer, as it has seen its
fleet rise by 36 % in 2003. It has also logged the second
strongest growth in absolute teu terms, with the addition of
84,414 teu, boosting its capacity to 319,180 teu.
CMA CGM has climbed from rank 8 to
rank 5, passing Cosco, APL and Hanjin-Senator. While APL
logged a fleet growth of 13.6%, Cosco and Hanjin-Senator saw
their fleet decrease by 1.4% and 7.2% respectively.
On the mergers & acquisition side,
the largest transaction concerned the buying of the Kien
Hung Line services by Hamburg-S'd, enriching the already
consistent network developed by this company on South
America trades. The China Navigation Co, the shipping arm of
the UK-based John Swire Group, has bought two multipurpose
services, the Bank Line Europe-South Pacific service (bought
from Andrew Weir) and the Indotrans US Gulf-South Asia
service (bought from Oldendorff carriers). The other
transactions are summed up in the accompanying table.
A new US-based carrier is born,
U.S. Lines, which has launched a South China-California
service in December, with 1,500-1,700 teu ships.
2004 will see the emergence of two
new players on the Asia-Europe route, Pacific International
Lines (PIL - Singapore) and Wan Hai (Taiwan). Both lines
will offer a joint service employing eight ships averaging
2,500 teu (owned or chartered in 2003 for delivery in Q1 and
Q2 2004). Although they are to start from scratch on this
trade, both operators have strong trump cards to play
because of their vast networks east of Suez, which allows
them to offer much more than a mere east-west service.
2003 has been also marked by the
launching of fully fledged Asia-Med services dedicated to
regions usually feederised, such as Turkey and Black Sea or,
to a lesser extent Adriatic. These initiatives have been
launched by CMA CGM, MSC and Lloyd Triestino (all three
lines dealt already with large volumes via feeders in these
areas). These services employ a total of 22 ships of
2,000-3,000 teu,
These new services (to only
mention them) have of course exerted a significant pressure
on the charter market, and have helped to soak up the pool
of available ships in the 2,400-3,000 teu range.
It must also be added that, in
2003, the extra volumes carried during the transpacific
summer season have been dealt with in an orderly manner,
i.e. through the launching of well defined extra loops, in
contrast with 2002, when extra ships were chartered for
single trips or round voyages, out of any schedules, and
acting as sweeping ships.
|
|
|
Operators:
transactions and significant moves in 2003
Straight sales
-
Hamburg-S'd
bought the Kien Hung Liner services from the Kien Hung
Shipping Co.
-
The China
Navigation Co (Swire group) bought the Bank Line service
from Andrew Weir
-
The China
Navigation Co (Swire group) bought the Indotrans service
from Oldendorff Carriers.
-
H. Stinnes
Linien bought Ellerman share in the Beacon service from
Hamburg-S'd
-
Van Uden
Maritime bought the Baltic Express Line (BEL) from Kersten
Hunik.
-
Seawheel Ltd
was bought by its management from the Simons Group.
-
Samskip bought
50 % of T&E Esco Container Lines A/S from Tschudi & Eitzen.
-
Scandlines
Deutschland GmbH bought T&E Esco Roro Line A/S from Esco.
-
Mann & Son
Holdings Ltd (UK) bought Esco Eurolines from ESCO.
-
The P&O Group
sold its remaining 50 % interest in Associated Bulk Carriers
Ltd (ABC) to Eurotowers Holdings SA (Ofer Group) and wished
to sell its 50 % share in P&O Nedlloyd.
-
MISC bought
American Eagle Tankers (AET) from NOL - APL's parent
company.
-
Clipper Elite
Carriers (CEC) bought Tonnevold & Clausen A/S (T&C).
-
Spliethoff's
has taken control of Wijnne & Barendsz.
-
Beluga
Schiffahrt took over General Shipping & Chartering
(GenChart).
-
The Clipper
Group took control of 100% of Van Ommeren Clipper
Shipholdings (VOC) with the acquisition and of the one-third
share held by Vopak and of the one-third share held by
Fortis Private Equity Netherlands.
-
The Clipper
Group bought Lasco Shipping (USA), renamed Clipper Bulk
(Portland) Inc.
Transfers and
moves within operating groups
-
A.P.
M'ller has merged the two companies A/S D/S Svendborg and
D/S 1912 A/S into a single one: A.P. M'ller-Maersk.
-
Costa
Container Lines and Grimadi-Genoa (Gilnavi) form a joint
venture (with CCL as manager).
-
Hamburg-S'd
abandoned its trade names 'Columbus Linie' and 'Crowley
American Transport'.
Cessations of
activity
Significant
other moves
-
Foundation of
U.S. Lines, USA - New transpacific operator.
-
Melfi
Container Line, Cuba, launched a Med-Canada-Cuba service
(replacing Coral C.L. service)
-
Tolteca Feeder
Line (a jv of Wilh. Wilhelmsen and Mexican investors)
launched a Mexico-Los Angeles service - Closed after two
months of operation.
-
CSX Lines was
renamed Hoizon Lines following its purchase by the Carlyle
Group.
-
Ecomarine
International Seatrade launch a West Africa feeder service
-
Swan Container
Line Ltd., Isle of Man, is formed by Eurogate International,
D'hle Schiffahrts Agentur and Fesco (service Germany-St
Petersburg).
-
Kraftmar
Container Line, a new operator based in Cyprus, launch intra
Med services.
-
Smart Shipping
Co Ltd, Hong Kong, develops ship operating activities.
-
The two main
shareholders of Swedish Orient Line (SOL), Navalmar
Transportes Maritimos Ltda and Imperial Shipping won their
bid to took control of more than 75 % of the company, which
was de-listed.
-
Marconsult &
Thode Schiffahrt (MTC) split two years after the merger of
MarConsult and Johs. Thode
|
|
The containership second-hand
market in 2003 |
|
There were a total of 285 sales
concluded in 2003 of which 181 fully-cellular containerships, 63
multi-purposes, 21 ro-ros, 5 ro-los and 15 conbulkers, for a
total of nearly 460,000 teu. These figures show an increase of
about 25 % additional transactions for the fully-cellular
containerships over 2002, when 135 ships were sold. The
progression by size range is even more significant. Sales of
ships of 3,000 teu and more have been multiplied by 3.6 going
from 13 to 47 transactions, whereas those of 2,000 to 3,000 teu
have more or less stagnated (28 this year against 30).
There has been a slight increase in the
sale of units of 1,000 to 2,000 teu, moving from 50 up to 60
deliveries. Finally, there were 46 ships with a capacity of less
than 1,000 teu which changed hands in 2003 (against 42 the
previous year).
In terms of teu capacity, we have moved
from about 220,000 teu in 2002 to 384,000 teu this year, a
progression of 57 %!
-
47
ships of more than 3,000 teu
-
28
ships between 2,000 and 3,000 teu
-
60
ships between 1,000 and 2,000 teu
-
46
ships below 1,000 teu.
Numerous 'en bloc' sales are to be
noted such as those of Sovcomflot to MSC and Zodiac (10 ships of
3,005 teu each) or again Sinotrans for 6 ships sold to Papathomas
and to MSC, with respectively 4 ships of 2,480 teu and 2 ships of
2,227 teu. Entreprises S&T released their only containerships,
namely 5 units of 2,200 teu to Ahrenkiel.
The most active owner in 2003 was
without any doubt MSC who acquired some thirty second-hand ships
for a total of nearly 70,000 teu this year (some are to be
delivered at the end of their charters in early 2004). This owner
touched all sectors of the market from 1,000 up to 8,000 teu! The
rule for MSC seems to be simple: if a line requires a ship for
more than one or two years, why not buy it? This policy has so
far paid off.
Outside MSC some operations were done
directly with line operators such as PIL or Cosco, but the
second-hand market was once again dominated by the usual
investing owners such as the German KGs, Zodiac, Costamare,
Danaos, etc.
|
Ships
under 1,000 teu
It is in this category that we find the
largest number of ships sold to regular line operators. No buyer
stands out in particular, but at a regional level, it is clearly the
Far East that is the winner with nearly half of the market. For
instance we can mention the en-bloc sale of the 969 teu, built in
1983, 'Noble River' and
'Precious River' from Coscon to Chao Yang at $2.8 million apiece. With
little speculative element, ships' values in this sector of the market
only went up between 10 to 15 %.
|
|
Ships of 1,000 to 2,000 teu
After a rather good year in 2002 with
50 ships sold, the 2003 vintage can boast of 60 transactions and
an increase in values of 20 to 25 %. The highlight of
transactions in this category was certainly that of 8 ships built
between 1994 (2 units), 1998 and 1999 by the bankrupt owner Kien
Hung Shipping, to PIL and Scholler at the incredible price, at
the time, of respectively $ 13.5 million and $ 18.1 million at
auction. The other interesting sale concerns the 4 'Sietas 170'
of 1,680 teu, built in 2002, by Marlow Navigation to Kartig
Shiffspool/V ship, at a price of $ 24.0 million each reflecting
the 5-year charter attached to Maersk/Sealand at a rate of
$ 12,950 per day. This year, unlike the precedent, combined sales
(sales and time-charters back) were less numerous.
|
|
Ships of 2,000 to 3,000 teu
The phenomenon which we described last year
concerning ships in this size has again been prevalent this year. Is
it the fear to see this category of ship be progressively taken over
by the bigger sizes, or is it simply the delivery to come of 118 giant
ships currently under construction which is provoking this situation?
Whatever the reason is, only 28 sales compared to 30 last year were
concluded. This size of ship remains the 'reserved ground' of the
German KGs who know how to profit from the popularity of these ships
with their clients.
We can mention the sale of
the 2,518 teu, 1986 built, 'Ambassador Bridge' to MSC at $ 15.5
million $ and the sale of the 2,602 teu, 2002 built, 'P&O Nedlloyd
Barossa Valley' to Schulte for $ 33.75 million.
|
|
Ships over 3 000 teu
Two figures suffice to resume the activity
in this sector of the fleet: 39 against 13. This is the comparison
between the number of acquisitions this year and that of last year.
Without counting the 428 ships which will be delivered to their owners
between 2004 and 2007! As Bill Gates said several years ago about
computing, 'it is neither the beginning nor the end but certainly the
end of the beginning'. The Panamax and over-Panamax are indubitably at
the sharp end of this market in which the price of ships continually
rise in the same manner as freight rates. For reference we can mention
the en-bloc sale of the 8-ship 'Berlin Senator' series, 3,007 teu,
1990 to 1993 built, to MSC at a price of $ 22.5 million apiece, and
the en-bloc resale of the 'HS Columbus' and 'HS Barents', 4,994 teu,
delivery 2005, at $ 57 million each to German buyers.
During the course of the year 2003 the
appreciation in values has been in the order of 30 to 35 %. Ships
available for sale have been scarce, and the strong demand for tonnage
has helped to fill up the shipyards already fully occupied.
|
|
* * * Always more! The 'little box' is again
progressing and knows how to impose itself as a sure and
efficient means of transport, and in most economic sectors. There
are some pockets of resistance in some areas notably in the
transport of reefer goods. Despite heavy investments, containers
are finding it hard to take a definitive control over this sector
which is putting up a good resistance! After several years of
applying a policy of price dumping, the majority of line
operators have decided to readjust their tariffs, and by doing so
helping to favour the resurgence of the conventional reefer
market.
We can already announce that 2004 will
carry on with the trend towards higher prices of containerships
which started last year, as shipbuilding yards are currently
saturated, and will remain so for the next three years.
|
Shipping and Shipbuilding Markets in 2003
I N D E X
|






 - Via Raffaele Paolucci 17r/19r - 16129 Genoa - ITALY


